


QIAmini Launch Might Change The Case For Investing In Qiagen Stock (QGEN)
- Qiagen has launched QIAmini, a compact benchtop system that automates DNA and RNA extraction for up to eight samples per run, targeting more than 100,000 smaller research and academic labs that currently rely on manual workflows.
- The new instrument extends Qiagen’s 2026 automation push alongside QIAsprint Connect and QIAsymphony Connect. It aims to cut over 80% of hands-on prep time and shift more testing volume toward recurring consumables in budget constrained research settings.
- We will now assess how Qiagen’s push into compact automation with QIAmini might influence the existing investment narrative around automation scale.
Scan beyond Qiagen and see which lab automation and life sciences peers are already on our curated list of 92 robotics and automation stocks shaping the next wave of sample processing efficiency.
Qiagen Investment Narrative Recap
To own Qiagen, you need to be comfortable with a story built on automation, molecular testing platforms and consumables driven cash flow, while research and diagnostic budgets stay patchy. The QIAmini launch fits that script. However, the main near term swing factors still look tied to QuantiFERON volumes and how quickly laboratories adopt Qiagen systems already on the market.
For now, QIAmini looks additive rather than transformative. Management is targeting about US$20m of incremental second half 2026 revenue from the broader automation push, so the key upside catalyst is execution on these rollouts. The biggest risk remains prolonged weakness in academic and research funding, which could keep instrument demand subdued.
The most relevant recent development for QIAmini is the broader expansion of Qiagen automated sample preparation, including QIAsymphony Connect and QIAsprint Connect. Management has linked this family of systems with an expected US$20m revenue uplift in the back half of 2026. This is modest versus Qiagen’s US$2.1b in annual sales but still meaningful for mix.
For you as an investor, that cluster of launches creates a clearer operational catalyst. Better instrument placement and a larger installed base can support consumables usage, which matters for earnings quality. The flip side is straightforward. If funding delays slow lab purchasing cycles, the whole automation suite, including QIAmini, could take longer to reach scale.
Qiagen's current analyst storyline points to revenues of US$2.5b and earnings of US$563.2m by 2029, built on an assumed 6.0% yearly increase in sales and an earnings move of about US$154m from US$409.3m today to that 2029 consensus level.
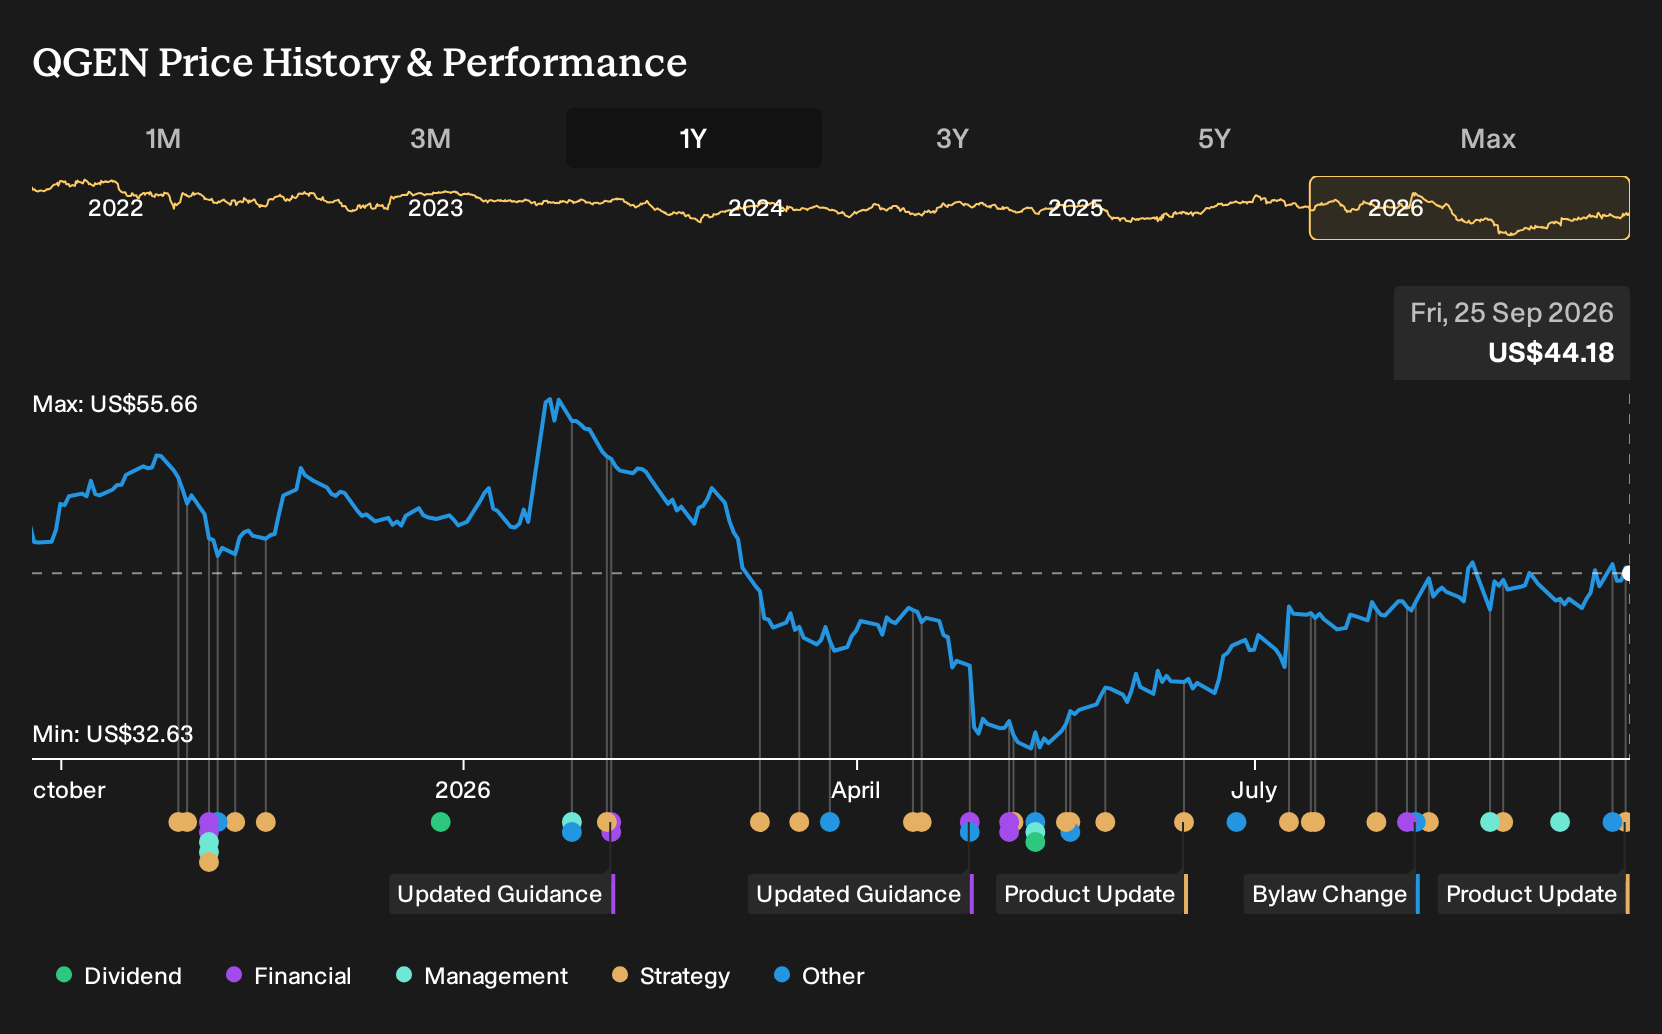
Uncover how Qiagen's fair value indicates a 5% potential change in its current price before crowding closes the discount.
Exploring Other Perspectives
One alternate view focuses on upside from Qiagen’s automation push rather than funding risk. The most optimistic analysts were already modeling about US$2.6b of 2029 revenue and US$764.6m of earnings before this QIAmini news. That is far above the consensus US$2.5b and US$563.2m. Those narratives may evolve as you reassess the stock.
Explore 4 other Qiagen fair value estimates, including one that suggests as much as 218293% upside from the current price!
Form Your Own Verdict
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Qiagen research is our analysis highlighting 2 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Qiagen. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Qiagen's overall financial health at a glance.
Looking For More Ideas Beyond Qiagen?
If the QIAmini story has you thinking more broadly about where to allocate capital next, it can help to line up a few different angles using the Simply Wall St Screener before committing fresh money.
- For investors hunting for quality at a sensible entry point, review companies on our 32 high quality undervalued stocks that might align with your return and risk preferences.
- If capital preservation sits high on your checklist, focus on businesses screened for resilience and steadier profiles through our 30 resilient stocks with low risk scores and compare how they stack up to Qiagen in terms of consistency.
- Those looking for potential bright spots that receive less attention can scan the 16 high quality undiscovered gems and see which stocks merit a place on your watchlist next to Qiagen.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com