


How Export Halt Will Impact BRP Stock Investors
- BRP has faced new U.S. trade measures in 2026 that led the manufacturer to stop shipping Canadian-made Can-Am Spyder and Can-Am Canyon vehicles to the United States, in addition to tariffs on steel, aluminum, and copper that affect costs and profitability.
- The halt in exports of key products and higher input costs directly affect BRP's production footprint, pricing flexibility, and near-term earnings capacity, even though the business had previously reported firm revenue trends and market share gains.
- We will now assess how BRP's investment narrative is affected by halted U.S. shipments of Canadian-made vehicles and new metal tariffs.
Broaden your watchlist beyond BRP by scanning our hand-picked 9 high quality undiscovered gems that may not be front-page news yet still have resilient fundamentals.
BRP Investment Narrative Recap
To own BRP, you need to be comfortable with a powersports business that leans heavily on discretionary spending, internal combustion products, and exposure to metal input costs. The biggest near term swing factor is how well production and pricing can absorb the halt of U.S. imports for Canadian made Can Am units while keeping dealers stocked.
The key risk right now is tariff volatility on steel, aluminum, and copper, layered on top of already thin net margins at 1.2% and high leverage. Trade actions that linger or broaden could weigh on earnings quality and delay any margin repair that analysts had been expecting over the next few years.
The most relevant recent data point is BRP’s prior decision to lift full year earnings guidance after reporting firm revenue and market share gains before the new U.S. measures. That update indicated that management was leaning into a story of gradual earnings recovery, supported by product launches and a more balanced dealer channel.
The halt of Canadian made Can Am shipments into the U.S. now tests that outlook directly. Any future commentary on guidance, electrified product rollout, or geographic mix will matter because it will show whether BRP can offset lost U.S. volume and higher metal costs with international growth, pricing, and mix, or whether margin pressure becomes the dominant factor.
BRP's current analyst story points to CA$10.4b in revenue and CA$653.6m in earnings by 2029, based on 3.7% yearly revenue growth and an earnings increase of about CA$538.6m from CA$115.0m today.
Uncover why BRP's fair value indicates a 27% potential upside to its current price before that discount closes.
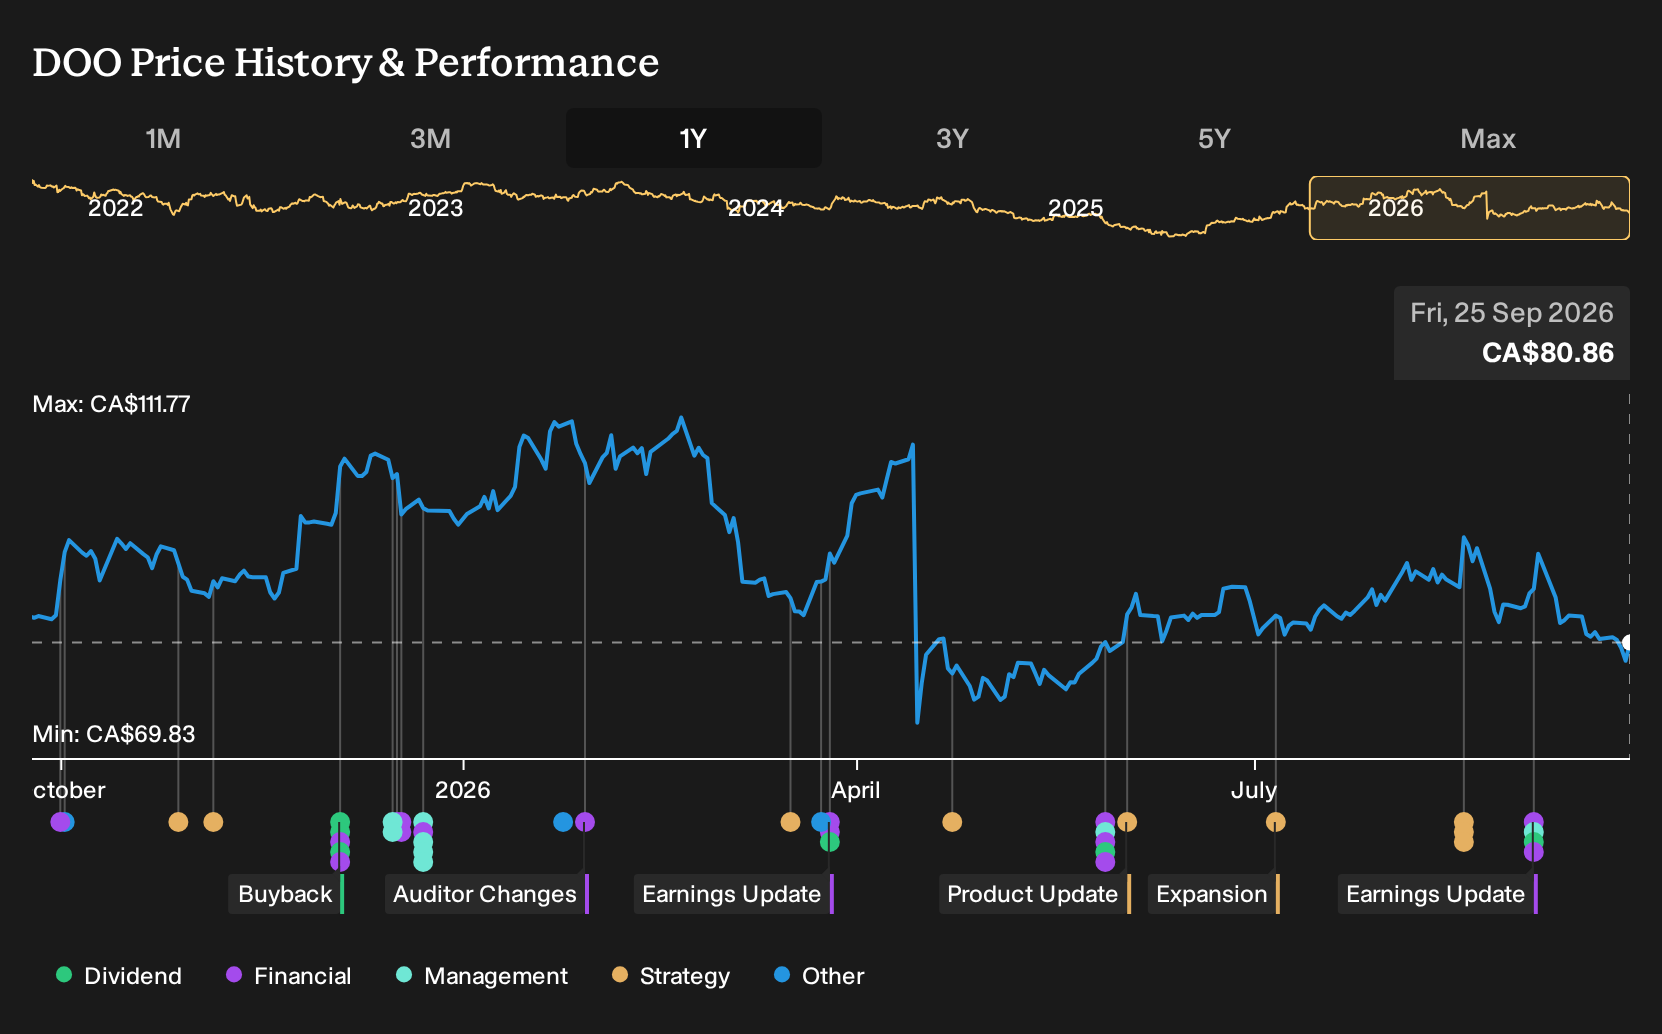
Exploring Other Perspectives
Some of the most optimistic analysts were leaning on international expansion as the bigger story for BRP, with forecasts of CA$10.8b in revenue and CA$689.8m in earnings by 2029. That contrasts with today’s trade shock. Use this as a reminder that opinions can differ widely and may now shift meaningfully.
Explore 4 other BRP fair value estimates, including one that suggests as much as 110% potential increase from the current price!
Decide For Yourself
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your BRP research is our analysis highlighting 3 key rewards and 3 important warning signs that could impact your investment decision.
- See our latest analysis for BRP. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate BRP's overall financial health at a glance.
Looking For More Ideas Beyond BRP?
If the BRP story has sharpened your thinking and you want to broaden your opportunity set, the Simply Wall St Screener can surface other businesses that fit the type of profile you are hunting for, from quality balance sheets to undervalued outliers.
- If you want potential value opportunities with solid fundamentals, start with a curated group of 5 high quality undervalued stocks that may line up better with your risk and return preferences.
- If capital protection matters more to you than chasing every upswing, focus on a 8 resilient stocks with low risk scores that screens for resilience first and upside second.
- If financial strength sits at the top of your checklist, concentrate on a list of solid balance sheet and fundamentals (7 results) that highlights companies with robust finances and cleaner balance sheets.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com