


Does Autonomous Coast To Coast Flight Change The Bull Case For Joby Aviation Stock?
- Joby Aviation reported that its autonomy equipped Cessna Caravan completed a 3,199 mile, fully autonomous coast to coast flight in the U.S., handling taxi, takeoff, routing and landing under remote supervision.
- The mission put Joby Aviation’s autonomy stack to work in real freight, medical and defense style operations, highlighting how software driven logistics could become a second business line alongside future passenger air taxis.
- We will now examine how Joby Aviation’s long term investment narrative could shift as autonomy moves from test flights into cross country operations.
Scan 92 robotics and automation stocks, which, like Joby Aviation’s autonomy program, is pushing real-world automation into freight, medical logistics and defense operations.
Joby Aviation Investment Narrative Recap
To own Joby Aviation, you need to believe that electric air taxis and autonomy can mature into real services across passengers, freight and defense. The first autonomous coast to coast flight supports that bigger story, but the near term hinge point is still FAA certification progress and proving that early routes like Dallas Fort Worth can operate reliably at scale.
The biggest risk has not changed. Cash use remains heavy, the business is unprofitable, and management is running several capital hungry projects at once. The cross country success showcases technology, yet it does not directly solve dilution concerns or shorten the time until commercial operations cover a meaningful slice of expenses.
The recent S 1 filing for up to US$750 million of new equity sits right next to this autonomy milestone in the real world. The transcontinental flight shows a path to a second line of activity in cargo and defense logistics. The proposed capital raise is about having the runway to push both passenger eVTOL and autonomy forward in parallel.
For you as a shareholder, that combination creates a clear trade off. More funding can support certification, manufacturing with Toyota and wider autonomy deployments, but new shares can weigh on existing holders. The operational catalyst is still regulatory approval and first paid flights in places like Dallas Fort Worth. Execution on those milestones will do more to change the story than any single headline tour.
Joby Aviation's narrative projects US$718.3 million revenue and US$44.9 million earnings by 2029. This assumes 83.5% yearly revenue growth and an earnings improvement of about US$923.1 million from a loss of US$878.2 million today.
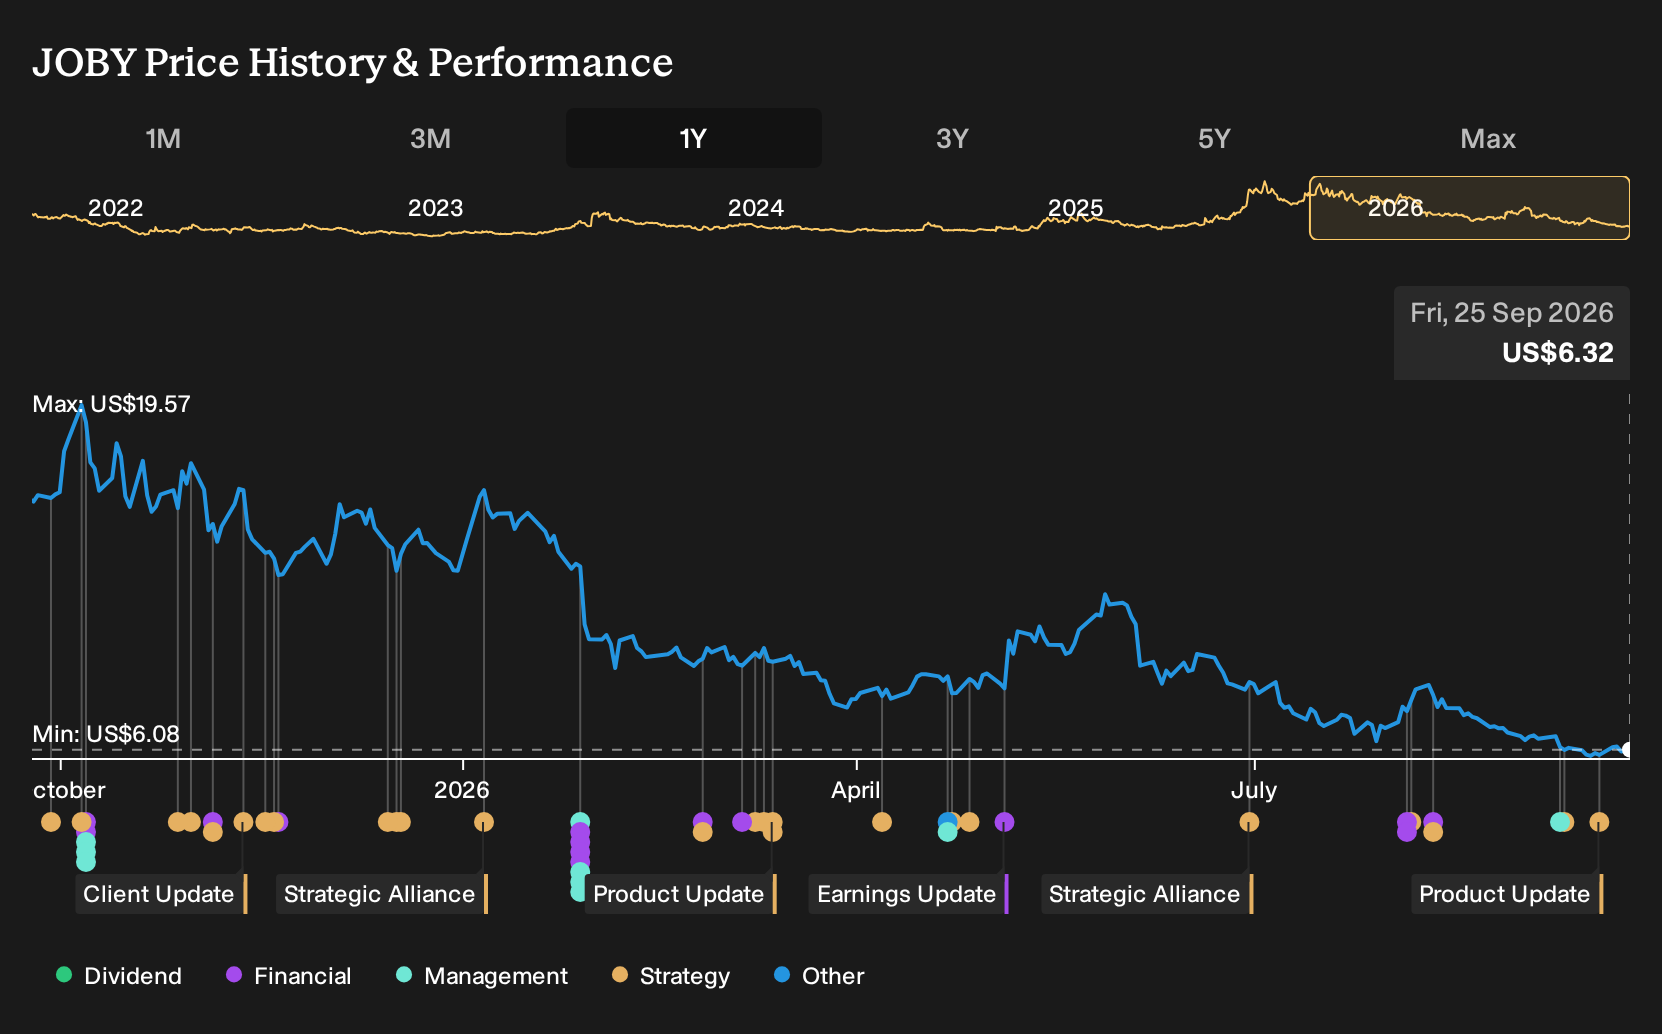
Discover how Joby Aviation's fair value points to a 69% potential upside to its current price before other investors respond and narrow that gap.
Exploring Other Perspectives
Some of the lowest analysts focus on autonomy risk. You see that in their January 2029 assumptions, with revenue at about US$319.0 million and earnings near US$20.9 million, plus a very high implied 403.6x P/E. Those numbers reflect a far more cautious view on Joby Aviation that the coast to coast flight could eventually challenge.
Explore 5 other Joby Aviation fair value estimates, including one that suggests as much as 88% downside from the current price!
Decide For Yourself
Don't just follow the ticker; dig into the data and build a conviction that's truly your own.
- A great starting point for your Joby Aviation research is our analysis highlighting 1 key reward and 2 important warning signs that could impact your investment decision.
- See our latest analysis for Joby Aviation. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Joby Aviation's overall financial health at a glance.
Looking For More Ideas Beyond Joby Aviation?
If you want to stress test your Joby Aviation thesis, it helps to compare it with other opportunities that share some of the same themes like capital intensity, risk profile or balance sheet strength. The Simply Wall St Screener can help you build that wider watchlist in a structured way.
- If you care most about financial resilience and clean balance sheets, start with a list of solid balance sheet and fundamentals (24 results) that can help you compare Joby Aviation with companies that carry less financial strain.
- If potential mispricing is your focus, line Joby Aviation up against a 32 high quality undervalued stocks and see how its market value stacks against businesses with stronger fundamentals on paper.
- If you prefer to cast a wider net and hunt for less crowded opportunities, broaden your shortlist with a 16 high quality undiscovered gems that surfaces under the radar companies with solid underlying numbers.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com