


Does Board Appointment Change The Bull Case For Talos Energy Stock (TALO)?
- Talos Energy appointed retired U.S. Air Force Major General Barbara J. Faulkenberry to its Board in October 2026, adding deep expertise in large scale global operations, logistics, risk management, and prior public company board roles across energy, hospitality, and transportation.
- Faulkenberry’s background overseeing tens of thousands of personnel and complex asset networks directly relates to Talos Energy’s operational execution needs in offshore production, decommissioning, and capital intensive projects.
- The focus will now turn to how Talos Energy’s investment narrative might reflect this board appointment, which highlights operational and risk oversight.
Talos Energy Investment Narrative Recap
For Talos Energy, the core belief is that concentrated offshore assets in the Gulf can still generate attractive barrels if operations stay tight and capital discipline holds. The major short-term swing factor is execution on high-margin Gulf projects, while keeping the US$100 million a year efficiency program on track. The new director adds experience in complex logistics and risk oversight, but this is more supportive than transformational to that thesis.
The largest near-term risk remains concentrated exposure to storms, decommissioning and cost inflation in a mature basin. Any uptick in unplanned downtime, regulatory burden or abandonment spending could offset gains from efficiency work and high-margin projects. Investors also need to stay comfortable with an unprofitable starting point and ongoing heavy capital needs.
The most relevant recent development around this board change is in the financing update. Talos Energy amended its credit agreement alongside a Gulf of Mexico acquisition, lifting the borrowing base from US$700 million to US$850 million and raising the letter of credit sublimit to US$300 million. Talos Ocho Energy LLC also guaranteed key second-priority senior secured notes.
For you, that combination points to a balance sheet structured to handle capital-intensive offshore work and future decommissioning obligations while still funding growth projects. It also increases sensitivity to execution. Missteps on drilling results, cost control or storm-related downtime could matter more now that the firm is tying a larger pool of secured debt to its producing asset base and new acquisition.
Talos Energy's narrative projects US$2.3b revenue and US$63.1 million earnings by 2029, based on the provided assumptions. This includes 5.2% yearly revenue growth and an earnings change of about US$468.1 million from a current loss of US$405.0 million.
Uncover why Talos Energy's fair value indicates a 19% potential upside to its current price, which could narrow quickly if sentiment shifts.
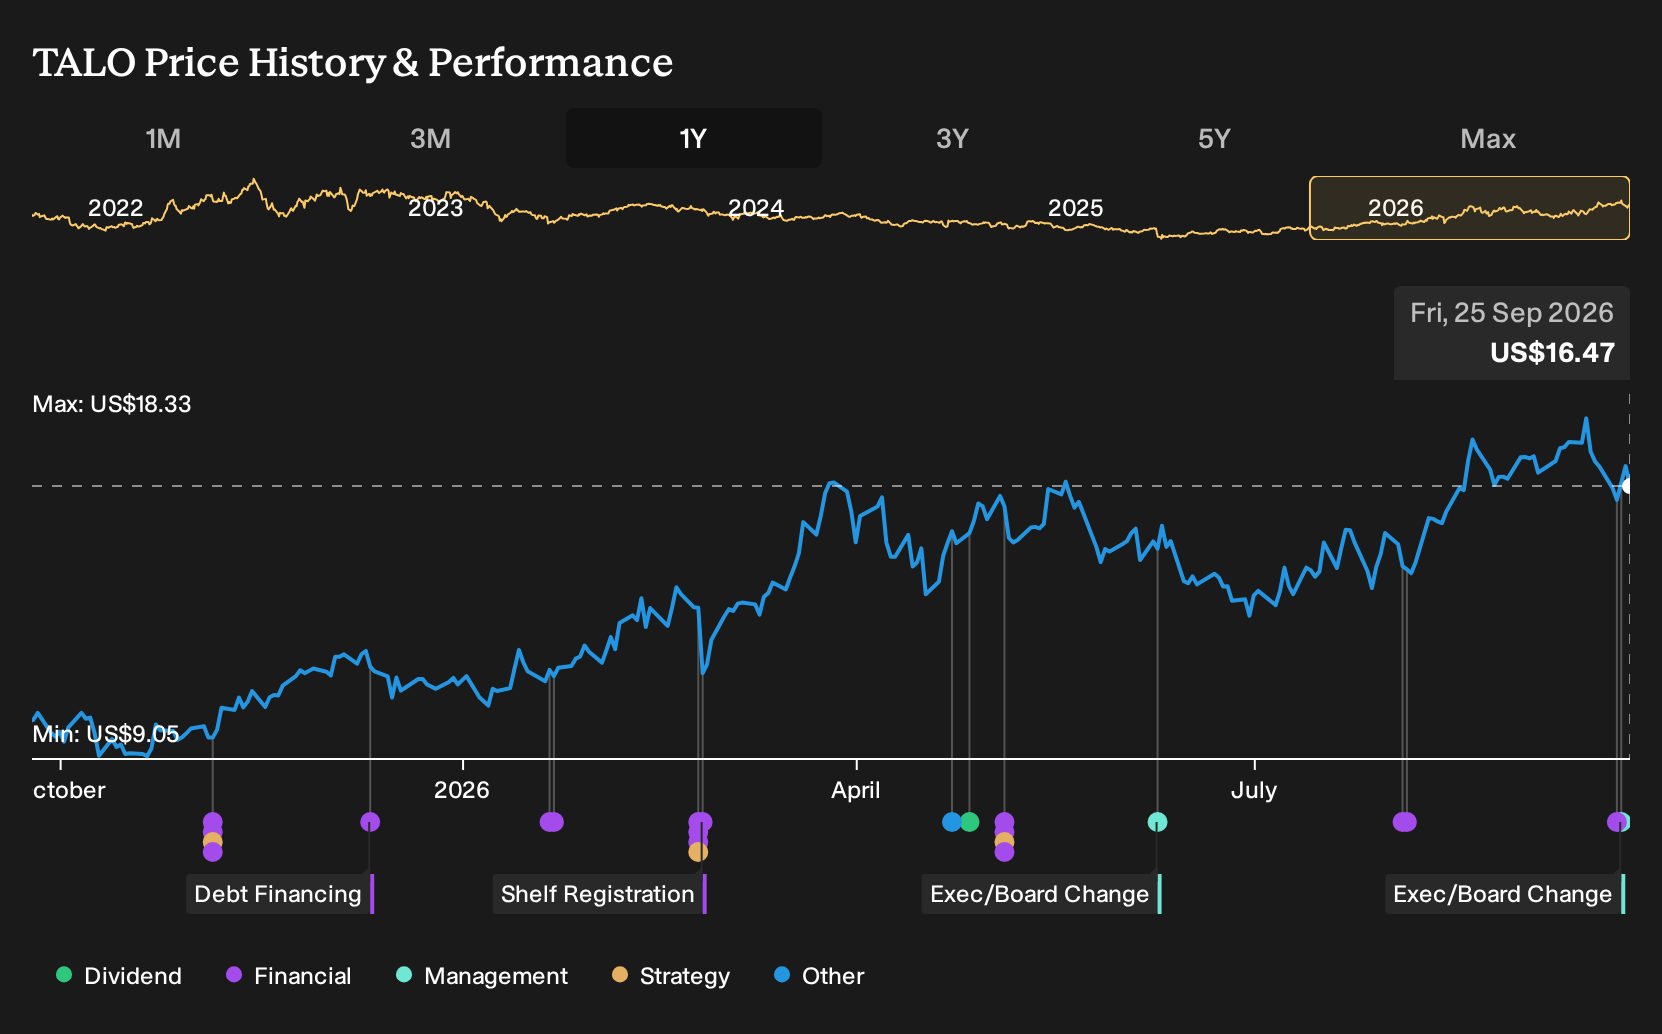
Exploring Other Perspectives
For Talos Energy, the most cautious analysts focus on weather and regional disruption risk rather than boardroom upgrades. Before this appointment, that group was working with slower 3.1% revenue growth and about US$1.9b of sales with US$227.5 million in earnings by 2029. You can treat this governance news as a reason to revisit both perspectives and stress test your own view.
Explore 3 other Talos Energy fair value estimates, including one that suggests as much as 27% downside from the current price.
Decide For Yourself
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your Talos Energy research is our analysis highlighting 4 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Talos Energy. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Talos Energy's overall financial health at a glance.
Looking For More Investment Ideas Beyond Talos Energy?
Once you have a view on Talos Energy, it can help to line it up against a few different types of opportunities to see where the risk and return trade off feels right for you. The Simply Wall St Screener lets you move from a single stock story to a curated set of companies that fit the traits you care about most.
- If you want potential upside without giving up balance sheet strength, start by reviewing companies on our 32 high quality undervalued stocks that pair solid fundamentals with more conservative pricing.
- For investors who lean toward lower volatility and capital protection, filter for businesses on the 30 resilient stocks with low risk scores that score well on financial resilience and risk metrics.
- If income matters to your plan, focus on payout potential by scanning the 8 dividend fortresses that combine higher yields with robust underlying cash flows.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com