


Is August Sales Decline Altering The Investment Case For J. Front Retailing Stock?
- J. Front Retailing reported that total consolidated sales for August 2026 declined 5.3% year over year, indicating softer trading conditions in its retail operations.
- The single-month sales drop raises questions about how renovation-related disruptions, consumer demand patterns, and inbound spending trends are affecting day-to-day performance.
- It remains to be seen how J. Front Retailing's investment narrative could be affected by the 5.3% year-on-year sales decline.
J. Front Retailing Investment Narrative Recap
To own J. Front Retailing, you need to be comfortable with a retail group in the middle of heavy renovation, cost pressure and a shift toward content and services. The 5.3% August sales decline sits right in that tension. It points to softer trading conditions but also to the real near term drag from floor closures and store refresh work.
The key short term swing factor is how quickly refreshed sites like Matsuzakaya Nagoya and Shibuya PARCO can stabilize tenant sales and inbound demand. The biggest immediate risk is that weaker duty free luxury spending and renovation related disruption keep margins under strain while SG&A and investment in AI, cards and new concepts remain elevated.
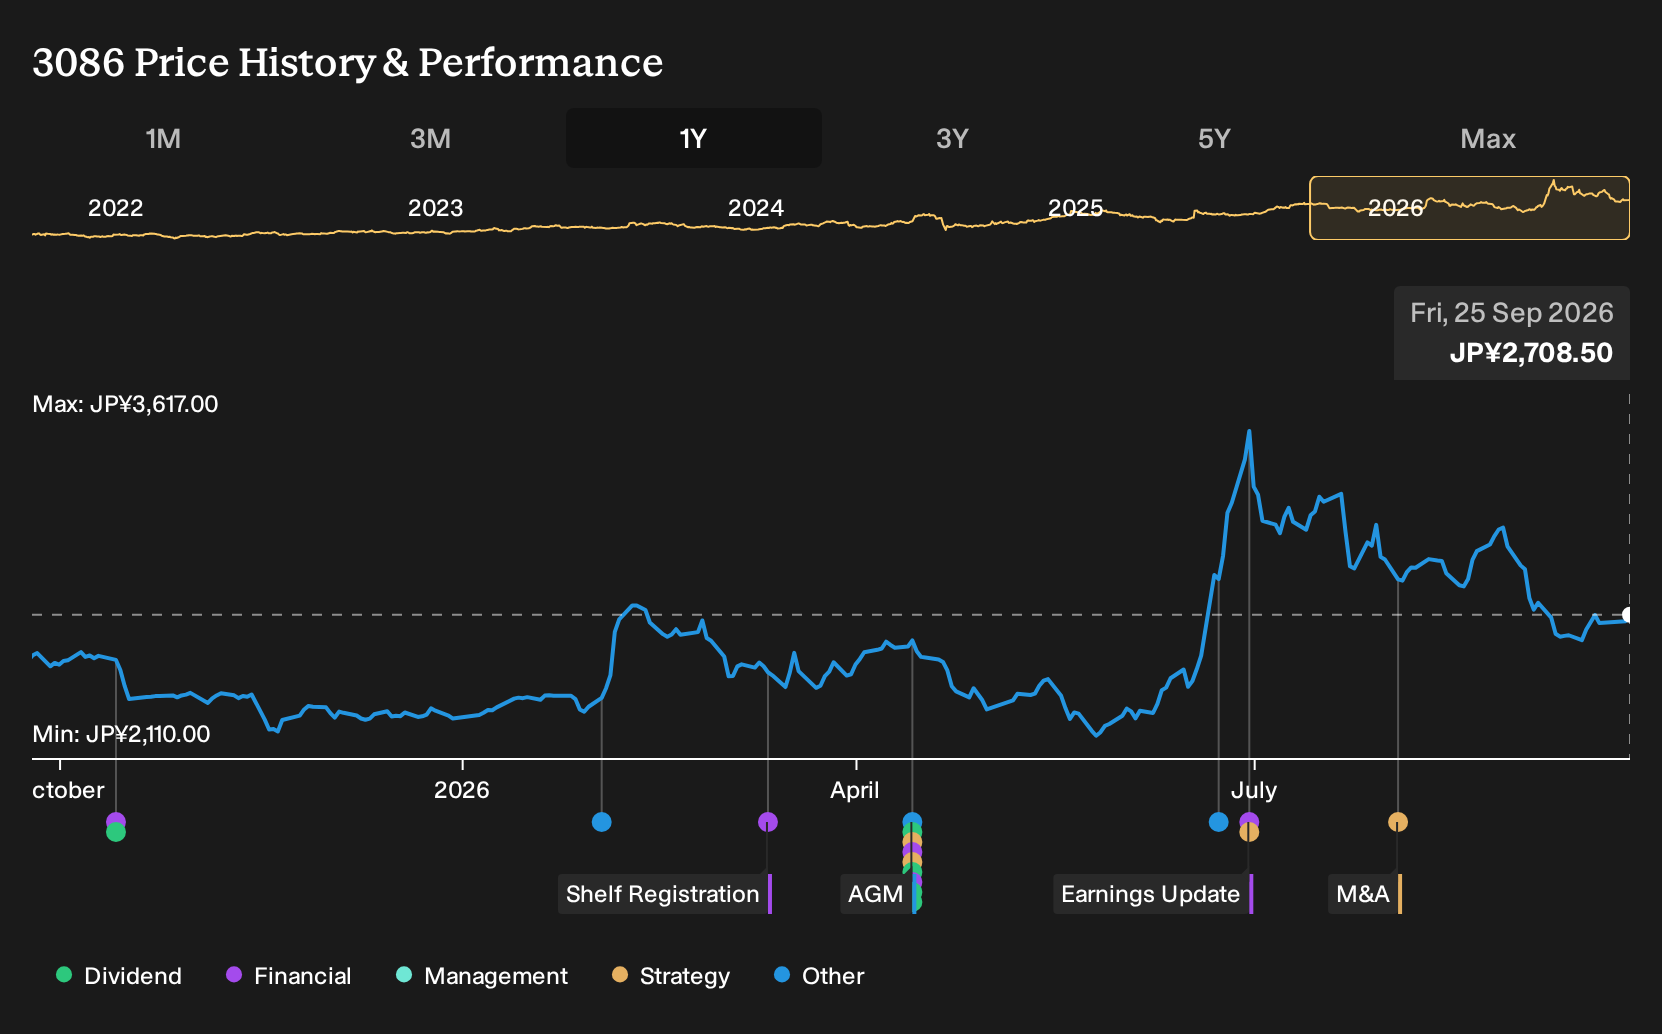
In that context, the August 2026 sales disclosure is the clearest recent update on J. Front Retailing’s operating pulse. A single month drop of 5.3% does not rewrite the long term thesis around inbound tourism, content businesses and card fee income, although it does underline that the path there is not smooth for department store heavy groups.
For catalysts, investors are still watching the roll out and ramp of renovated assets like Matsuzakaya Nagoya and the upcoming HAERA project in Nagoya Sakae, along with inbound CRM and card integration across Daimaru, Matsuzakaya, PARCO and GINZA SIX. The August weakness makes execution on those projects more important, because management is already carrying higher renovation spend, cost inflation and front loaded investment while profit growth expectations remain in place.
J. Front Retailing's current analyst storyline implies revenues of ¥477.0b and earnings of ¥35.2b by 2029, based on 2.7% yearly revenue growth and an earnings increase of ¥7.7b from ¥27.5b today.
Uncover why J. Front Retailing's fair value indicates a 13% potential downside to its current price, which could reflect a premium that may not hold.
Exploring Other Perspectives
For J. Front Retailing, the bearish twist comes from inbound tourism. While the base case leans on steady visitor spending, the lowest analysts worry that a 30% drop in average duty free spend lingers. They were already pencilling in slower revenue of ¥459.0b and earnings of ¥33.4b by 2029 before this August sales decline. You should expect that some of those views may shift as fresh data lands and use that spread in opinions as a cue to explore multiple scenarios yourself.
Explore another J. Front Retailing fair value estimate, including one that indicates up to 13% downside from the current price.
Form Your Own Verdict
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your J. Front Retailing research is our analysis highlighting 1 key reward and 4 important warning signs that could impact your investment decision.
- See our latest analysis for J. Front Retailing. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate J. Front Retailing's overall financial health at a glance.
Looking for more J. Front Retailing investment ideas?
If the latest update on J. Front Retailing has you rethinking your watchlist, it can help to compare this retailer with other businesses that face different demand patterns, balance sheets and payout profiles. The Simply Wall St Screener is a quick way to surface stocks that line up more closely with your own risk tolerance and income goals.
- If capital preservation comes first for you, start with a basket of businesses that have historically scored well on stability and resilience by reviewing our 21 resilient stocks with low risk scores.
- For readers who care most about financial strength and clean balance sheets, focus on companies that combine modest leverage with solid fundamentals using this curated list of solid balance sheet and fundamentals (22 results).
- If you want to broaden the search beyond J. Front Retailing and are hunting for lesser known opportunities with quality metrics, filter through a hand picked 74 high quality undiscovered gems that may not yet be widely followed.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com