


LaSalle LOGIPORT REIT (TSE:3466), Why Is Its Latest Update Drawing Attention?
LaSalle LOGIPORT REIT (TSE:3466) just paired a planned unit buyback with an upward revision to earnings and distribution guidance, giving investors new information on expected cash flows and capital allocation.
At a unit price of ¥146,200, LaSalle LOGIPORT REIT has seen short term momentum pick up with a 7 day share price return of 5.26%, even though the year to date share price is down 7.88% and the 1 year total shareholder return sits at 6.61%.
The announcement of a sizeable repurchase program and higher guidance on earnings and distributions has arrived just days after LaSalle LOGIPORT REIT was dropped from the FTSE All-World Index. This may have contributed to earlier share price pressure, and attention now appears to be shifting back to cash flow and capital return metrics.
Scan how LaSalle LOGIPORT REIT's capital return story compares with other income focused opportunities through our curated list of 14 dividend fortresses.
Bulls point to LaSalle LOGIPORT REIT's higher earnings and distribution guidance plus the planned buyback, while bears focus on recent index exclusion and price weakness. Which story do the current valuation markers actually support?
Price-to-Earnings of 40.6x: Is it justified?
On simple valuation markers, LaSalle LOGIPORT REIT is priced well above peers, with a P/E of 40.6x compared with a peer average of 19.4x and an Asian industrial REITs average of 16.4x, even after a year where its share price return lagged the wider JP market.
The P/E ratio compares the current unit price with earnings per unit, so a higher figure often reflects investors paying more today for each yen of current profits. For a logistics focused REIT like LaSalle LOGIPORT REIT, that can be a signal that the market is putting a premium on perceived income visibility, forecast earnings growth of 14.04% per year, and revenue growth forecasts of 15.2% per year relative to the broader JP market.
That premium is not small. The current P/E of 40.6x is described as expensive versus the estimated fair P/E of 24.9x, pointing to a level the market could move toward if sentiment or growth expectations cool. It also sits well above the Asian industrial REITs industry average of 16.4x and the peer group at 19.4x.
Explore the SWS fair ratio for LaSalle LOGIPORT REIT.
Result: Price-to-Earnings of 40.6x (OVERVALUED)
Still, the FTSE index exclusion and a recent year to date price decline of 7.88% could quickly pressure sentiment if guidance or buyback execution disappoints.
Find out about the key risks to this LaSalle LOGIPORT REIT narrative.
Another View on LaSalle LOGIPORT REIT's Value
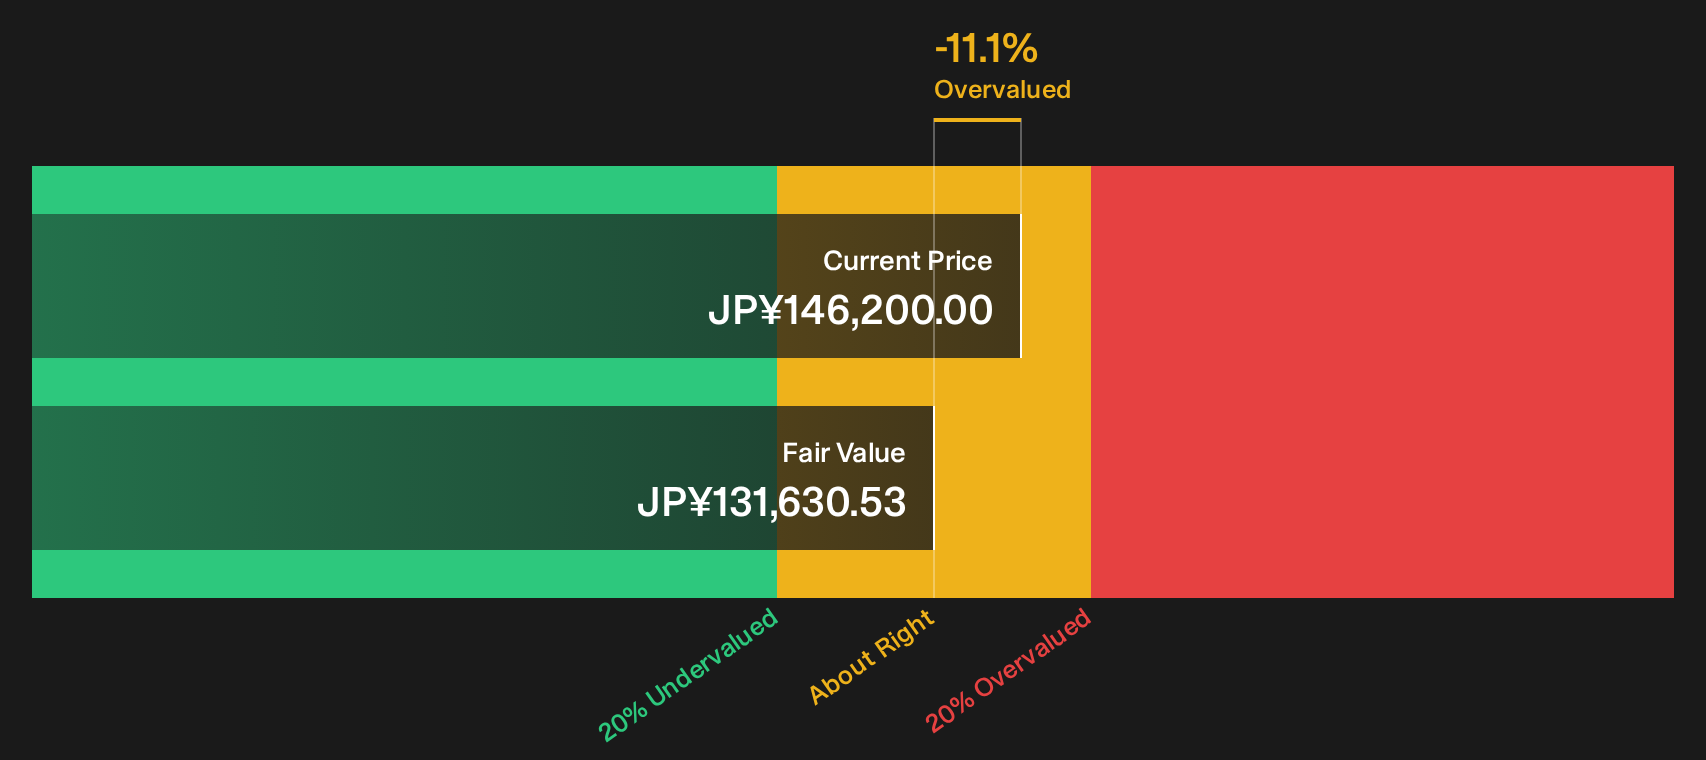
The P/E snapshot paints LaSalle LOGIPORT REIT as expensive, yet the SWS DCF model points to a different angle. At ¥146,200, the units trade above an estimated future cash flow value of ¥131,630.53, which suggests the current price leans rich rather than cheap. Which signal should carry more weight for you right now?
Look into how the SWS DCF model arrives at its fair value.
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out LaSalle LOGIPORT REIT for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 18 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Mixed signals around LaSalle LOGIPORT REIT's valuation and guidance can look confusing at first glance, so it helps to review the underlying data and pressure test both sides of the argument for yourself. To see what stands out on each side of the ledger, take a closer look at the 2 key rewards and 2 important warning signs.
Looking for more ideas beyond LaSalle LOGIPORT REIT?
If LaSalle LOGIPORT REIT has sharpened your focus on valuation and income, now is the time to widen your opportunity set with data driven stock ideas.
- Target stronger value potential by scanning companies flagged as compelling opportunities in the 18 high quality undervalued stocks.
- Prioritise resilience by reviewing businesses highlighted in the 21 resilient stocks with low risk scores that combine lower risk profiles with solid fundamentals.
- Hunt for fresh opportunities by uncovering quality companies in the 74 high quality undiscovered gems before they sit firmly on everyone else's radar.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com