


Is Three Year Tanker Charter Altering The Investment Case For DHT Holdings (DHT)?
- DHT Holdings announced that the VLCC DHT Panther, built in 2016, has been fixed on a three-year time charter at US$100,000 per day with a global energy company, with the contract having commenced in October 2026.
- This multi year charter secures contracted income for a modern vessel, which reduces earnings uncertainty and supports more predictable fleet utilization for DHT Holdings.
- We will look at how DHT Holdings' investment narrative shifts as this three year US$100,000 per day charter improves revenue visibility.
Scan for other shipping and energy transport stocks locking in multi year cash flows by reviewing our curated list of solid balance sheet and fundamentals (24 results) that echo the income visibility DHT Holdings is building with this charter.
DHT Holdings Investment Narrative Recap
To own DHT Holdings you need to be comfortable with a crude tanker business that mixes very strong recent earnings with forecasts that point to declining revenue and profit over the next three years. The DHT Panther charter helps offset some of that expected earnings pressure in the near term by locking in cash flow on a modern VLCC.
Over the next year or so, the key swing factor remains how exposed DHT Holdings is to spot rates on the rest of the fleet. The biggest risk is that weaker freight markets combine with high dividends and capex needs, which could squeeze financial flexibility if cash generation softens.
The three year US$100,000 per day contract for DHT Panther ties directly into the existing catalyst around more predictable cash flows from time charters. It converts part of the fleet from short term volatility to contracted income and supports the broader narrative of using modern, fuel efficient VLCCs to secure premium fixtures.
This announcement also sits against the backdrop of analysts expecting DHT Holdings revenue to decline 21.2% per year and earnings to fall 27.6% per year over the next three years. Locked in earnings from a single vessel do not reverse that outlook, but they can reduce operational risk and smooth results if the spot market weakens.
DHT Holdings' narrative projects US$424.7 million revenue and US$263.8 million earnings by 2029. This assumes a 19.0% yearly revenue decline and a US$209.9 million earnings reduction from current earnings of US$473.7 million.
Uncover why DHT Holdings' fair value is essentially aligned with its current price.
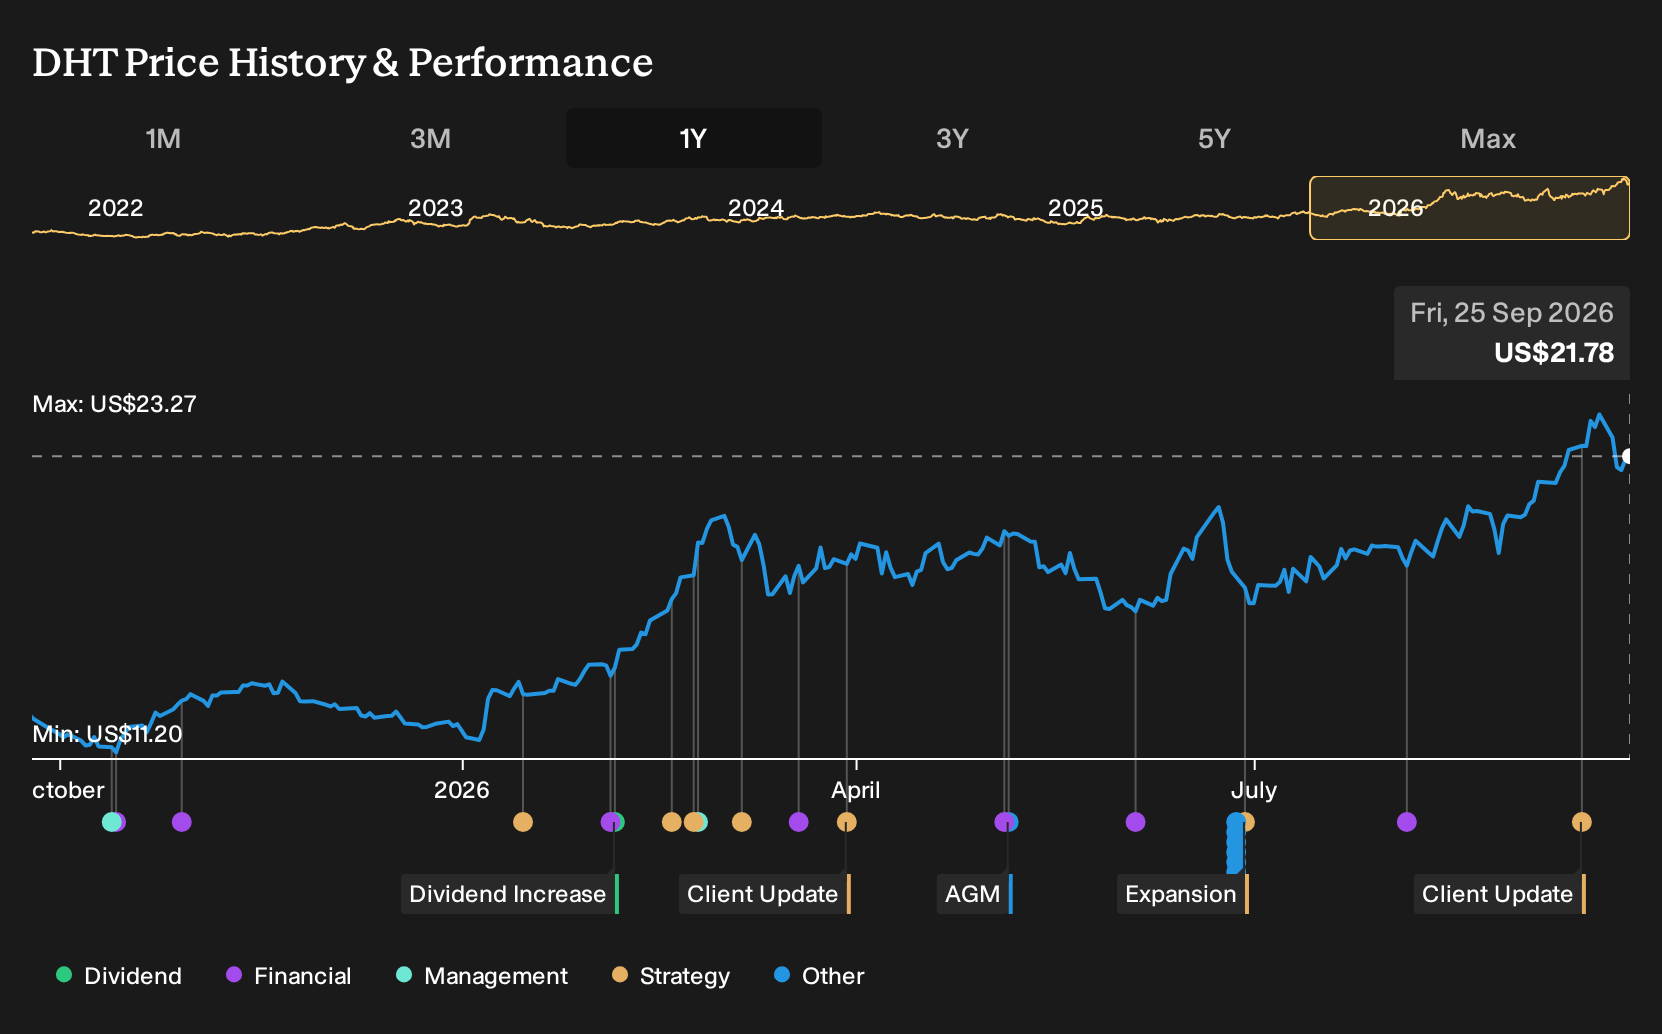
Exploring Other Perspectives
One alternate view on DHT Holdings focuses on the risk of leaning heavily on spot exposure while the most pessimistic analysts already penciled in revenue of about US$411.3 million and earnings of US$203.1 million by 2029. Those projections were set before this charter news, so you may see forecasts and opinions shift as analysts reassess the balance between fixed and spot income.
Explore 5 other DHT Holdings fair value estimates, including one that suggests it could be worth just $21.00.
Form Your Own Verdict
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your DHT Holdings research is our analysis highlighting 2 key rewards and 4 important warning signs that could impact your investment decision.
- See our latest analysis for DHT Holdings. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate DHT Holdings' overall financial health at a glance.
Looking For More Ideas Beyond DHT Holdings?
If this DHT Holdings update has sharpened your thinking on cash flow visibility and balance sheet strength, use that same lens to filter other opportunities with the Simply Wall St Screener.
- For investors who want potential upside with stricter quality filters, scan a curated set of 16 high quality undiscovered gems that pair solid fundamentals with less crowded coverage.
- If steady income is your priority, focus on companies in the 8 dividend fortresses that aim to combine higher yields with more robust financial profiles.
- For those who prefer to limit downside risk, narrow your universe to a 30 resilient stocks with low risk scores that screens for resilient balance sheets and more tempered volatility.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com