


How Investors May Respond To ThaiBev Stock Executive Reshuffle
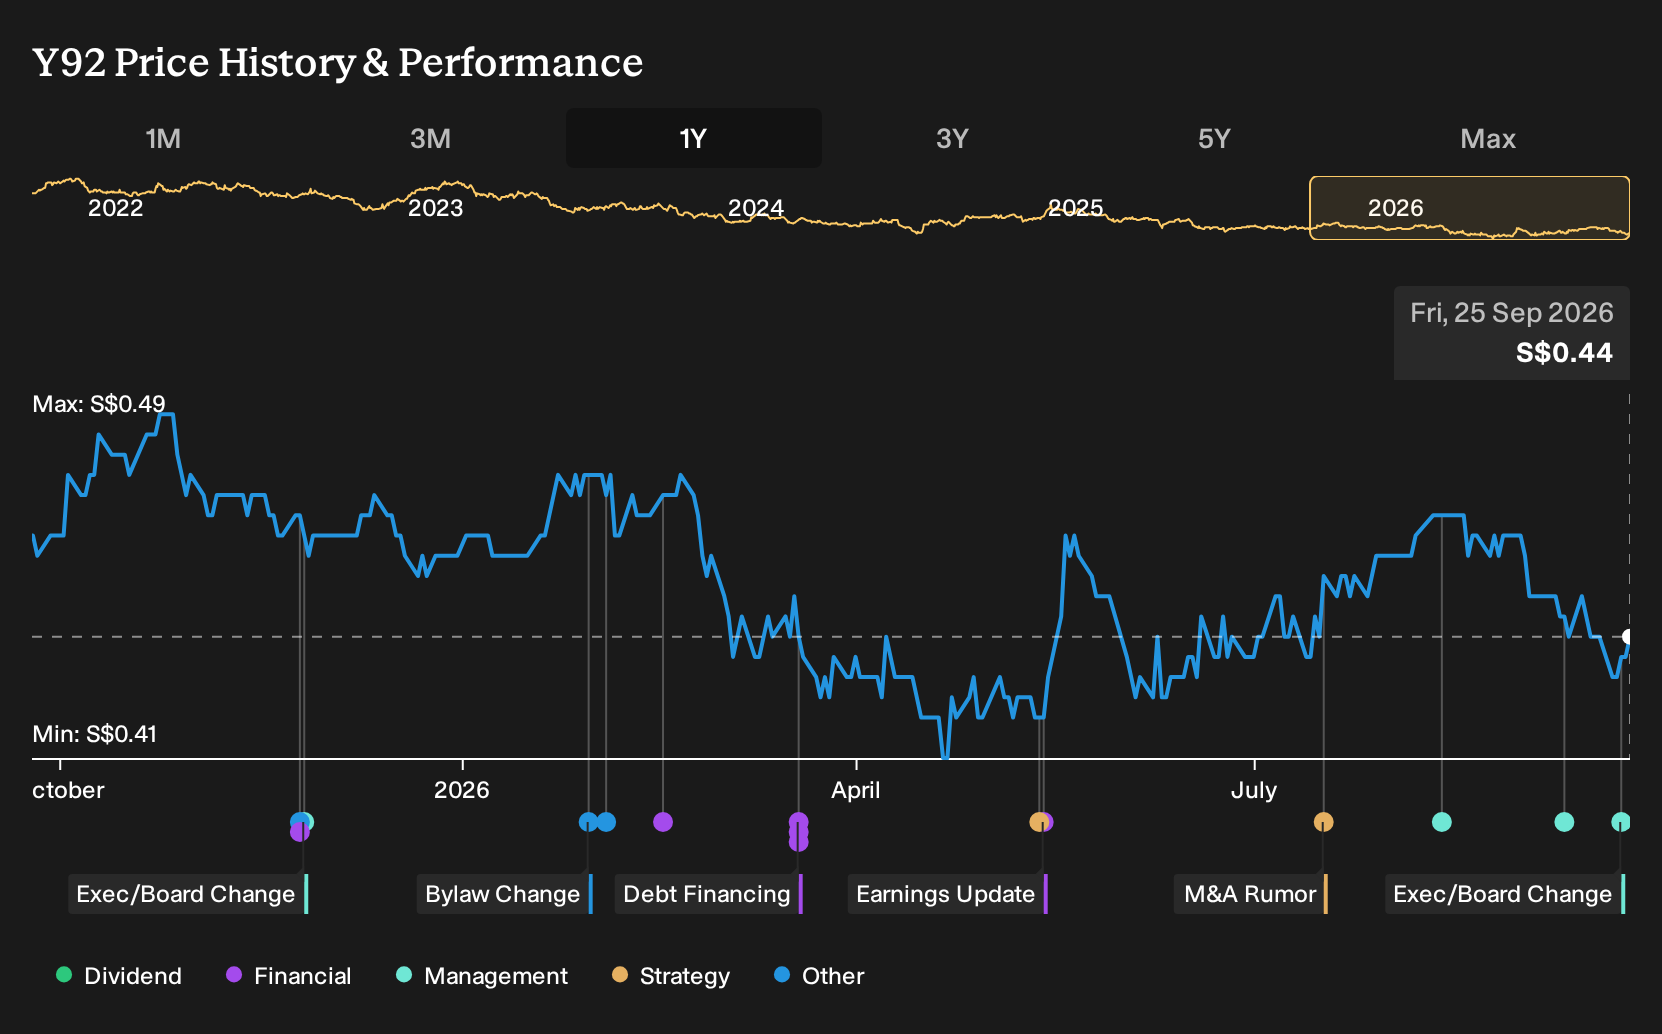
- Thai Beverage has overhauled its corporate structure, reshuffling its Executive Committee and shifting leadership across spirits, non alcoholic beverages, and group functions. These changes have been in effect since 1 October 2026.
- The reorganization concentrates product group leadership within a tighter inner circle, which may affect how Thai Beverage balances growth, cost control, and brand investment across its portfolio.
- We will now look at how Thai Beverage's investment narrative could be shaped by this streamlined Executive Committee and new product leadership.
Scan Thai Beverage's leadership reshuffle against a wider field of well run, resilient businesses by weighing it alongside 226 resilient stocks with low risk scores in your next watchlist refresh.
Thai Beverage Investment Narrative Recap
Being a shareholder in Thai Beverage really comes down to believing the group can keep turning a broad drinks and food portfolio into steady earnings, even as costs swing and regulation or competition bites in key spirits markets. In the short term, the story still hinges on defending margins where raw material and marketing spending have already pressured spirits and food profitability.
This leadership reshuffle alone does not look like a game changing near term catalyst. It may still influence how quickly management responds to risks such as potential licensing changes in Thailand and currency exposure in Myanmar, as well as how tightly cost control in beer and non alcoholic drinks is executed.
The most relevant announcement here is the appointment of Sopon Racharaksa as President at group level, with Kosit Suksingha and Rahul John Colaco taking direct charge of spirits and non alcoholic beverages. Thai Beverage is effectively putting seasoned operators over the two product clusters that matter most for margins and growth options.
For you as an investor, the interest is in execution. Spirits carry strong profitability but face regulatory and input cost risks. Non alcoholic beverages link to volume and marketing heavy growth plans. This new structure could either sharpen decisions on pricing, brand spend and cost discipline, or introduce extra coordination risk if roles overlap or slow approvals.
Thai Beverage's narrative projects THB 372.8b revenue and THB 31.3b earnings by 2029. This assumes 4.1% yearly revenue growth and about THB 4.7b earnings increase from THB 26.6b today.
Uncover why Thai Beverage's fair value indicates a 15% potential upside to its current price that could narrow quickly.
Exploring Other Perspectives
One alternate view puts Thai Beverage’s execution risk at the center. The most cautious analysts were only penciling in THB 359.2b revenue and THB 29.8b earnings by 2029 before this reshuffle. That is a much cooler outlook than consensus, and the new structure could easily nudge these forecasts in either direction.
Explore 4 other Thai Beverage fair value estimates, including one that suggests it could be worth just SGD0.434.
Form Your Own Verdict
Disagree with existing narratives? Extraordinary investment outcomes rarely come from following the herd, so go with your own analysis.
- A great starting point for your Thai Beverage research is our analysis highlighting 3 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for Thai Beverage. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easier to evaluate Thai Beverage's overall financial health at a glance.
Looking for more Thai Beverage style investment ideas?
If Thai Beverage has sharpened your focus on quality and risk, it can help to line it up against a wider bench of businesses that fit clear, disciplined criteria.
- For investors who care most about capital preservation and smoother ride potential, start with a curated set of 226 resilient stocks with low risk scores that screen well on resilience metrics.
- If you prefer to hunt for value where quality and pricing meet, weigh Thai Beverage against 184 high quality undervalued stocks that combine solid fundamentals with compressed expectations.
- Income focused readers who want cash flows today as well as tomorrow can compare its profile with 159 dividend fortresses that offer higher yields backed by sturdier balance sheets.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com