


Iovance Biotherapeutics (IOVA) Stock Trades At A Premium As Shares Jumped 421%
Iovance Biotherapeutics has seen its stock climb sharply over the past year, and that kind of move naturally raises a basic question for anyone looking at the shares. Is the current price you see on the screen adequately grounded in the company’s sales today and what those revenues may support over time?
- The stock has returned 421.3% over the past year, which puts a lot of weight on whether the underlying sales justify such a rapid re-rating.
- As a clinical-stage biotech focused on developing cell therapies, Iovance Biotherapeutics may see its valuation heavily influenced by how investors translate its current revenue base and commercialization progress into future sales potential.
- There is a second opinion on Iovance Biotherapeutics worth weighing. See what analysts think Iovance Biotherapeutics's shares could be worth.
For investors, the debate is whether Iovance Biotherapeutics’ recent share price level is supported by the scale and trajectory of its sales.
You can pressure test the same sales-based valuation question that surrounds Iovance Biotherapeutics across a wider set of companies by scanning 32 high quality undervalued stocks
Is Iovance Biotherapeutics Getting Expensive on Sales?
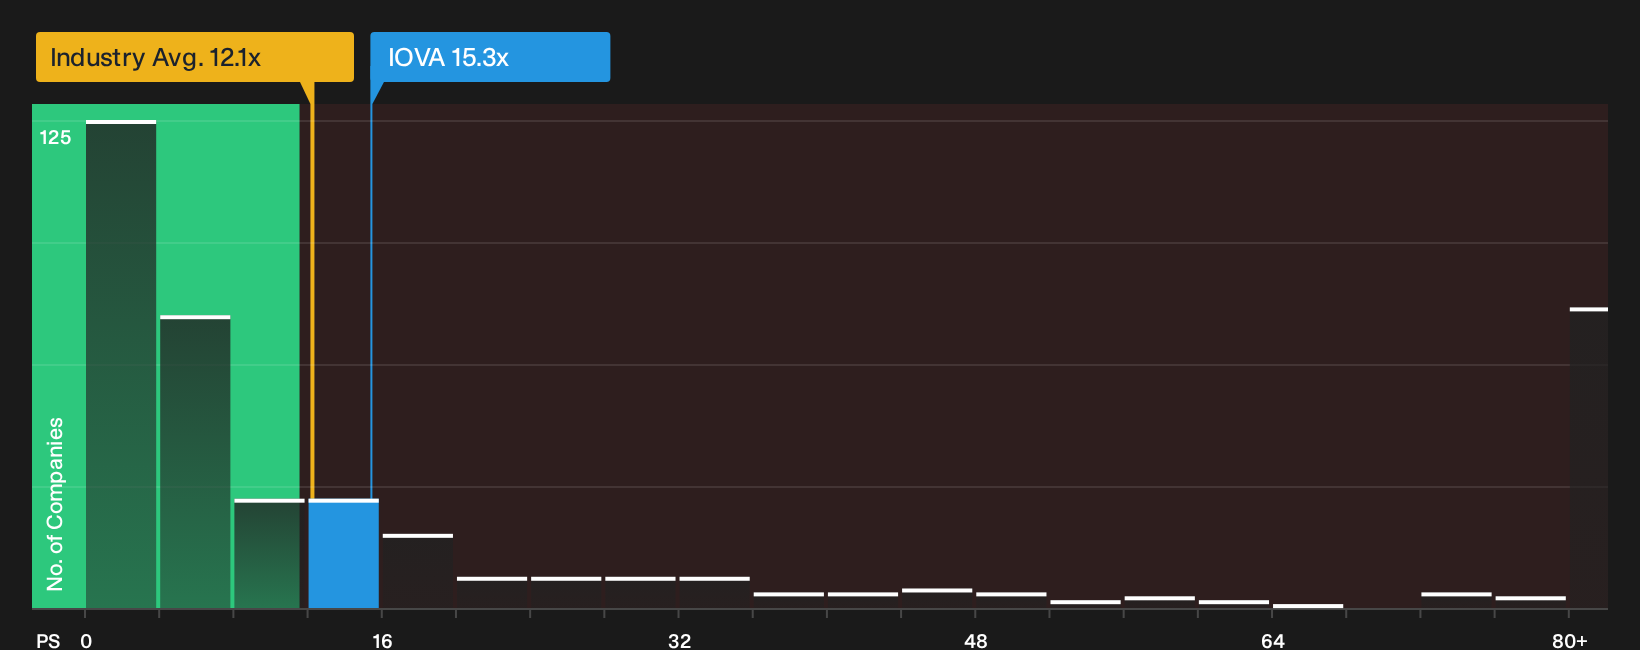
P/S is often the cleanest yardstick for a business like Iovance Biotherapeutics that is still loss making but has a measurable top line. On this lens, the stock trades on a P/S of 15.3x, which is above the broader Biotechs sector average of 12.1x and only slightly below the peer average of 16.1x. That puts the shares toward the higher end of what investors are currently paying for similar revenue streams in this corner of healthcare.
The tailored fair multiple implied by Simply Wall St’s model suggests Iovance Biotherapeutics is priced above what would be expected once factors such as growth profile, margins, market value and risk are taken into account, so the shares screen overvalued on this framework. Anyone considering the stock needs to judge whether the pipeline, commercial execution and funding position justify paying this kind of premium to the revenue it generates today. Explore the numbers behind Iovance Biotherapeutics's P/S valuation.
The Iovance Biotherapeutics Narrative: What Would Justify Today's Price?
Simply Wall St Narratives pick up where the valuation puzzle around Iovance Biotherapeutics' P/S multiple leaves off by spelling out which assumptions on future growth, margins and earnings would need to hold for the share price to be worth materially more or less than it is today. These narratives sit on Simply Wall St's Community page. Each narrative is framed as a thesis about Iovance Biotherapeutics' business that can be revisited over time rather than a one-off snapshot.
Community views on Iovance Biotherapeutics split between investors who see a mispriced growth story and others who think the current valuation already reflects most of the upside.
Bull case: 39% undervalued
"The number of treatment centers continues to increase, more doctors are referring patients, manufacturing has become faster and more efficient, and the company expects strong revenue growth this year…"
Discover why this Narrative puts Iovance Biotherapeutics at 39% undervalued.
Bear case: 10% overvalued
"The company remains highly dependent on Amtagvi, its lead (and only currently approved) product. Any setbacks in demand, reimbursement, or competitive developments for this therapy could have an outsized negative impact on Iovance's revenue…"
Explore why this Narrative puts Iovance Biotherapeutics at 10% overvalued.
For Iovance Biotherapeutics, who is steering the ship matters as much as what it earns
Price tags and sales multiples only tell part of the story, because the calibre of the leadership team and how they are rewarded can heavily shape what happens next for Iovance Biotherapeutics. See who runs Iovance Biotherapeutics and how they are paid.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com