


Is adidas (XTRA:ADS) Cheap As China Growth And Tim Hortons Buzz Lift Sentiment?
adidas (XTRA:ADS) is back in the spotlight after teaming up with Tim Hortons on a limited-edition Tims Run Club collection, while fresh coverage highlights the brand’s localization push in China.
Recent headlines around adidas, from the Tim Hortons collaboration to localization wins in China, come against a backdrop where the share price has risen 3% over the past week but is still down 19% on a 3 month share price return, and the 1 year total shareholder return has declined 17%. This suggests sentiment is recovering from a weaker run rather than breaking into a clear new trend.
Scan beyond adidas and see how other consumer names with strong brands and fresh product stories line up in our curated list of 618 high quality undiscovered gems.
adidas shares have bounced in the very short term, yet the price still trails both analyst targets and some intrinsic value estimates. Does that gap flag opportunity, or does it signal that expectations still need to reset before value feels clear?
Most Popular Narrative: 28% Undervalued
On the most followed view of adidas, a fair value of about €202.72 sits well above the last close at €146.50. This puts the spotlight on how the brand is expected to turn current momentum into longer term earnings power.
The accelerating global health and fitness movement is driving strong demand for adidas' performance and athleisure product categories, as demonstrated by double-digit growth in key segments like Running (+25%), Training (+20%), and Basketball, positioning the company for sustained volume expansion and recurring sales growth (impacts revenue and earnings).
See why 90 investors see adidas as 28% undervalued.
Result: Fair Value of €202.72 (UNDERVALUED)
Still, tariff driven cost pressure and tougher fashion cycles could quickly test the bullish adidas narrative if pricing power or fresh product demand disappoints.
Find out about the key risks to this adidas narrative.
Another View on adidas Valuation
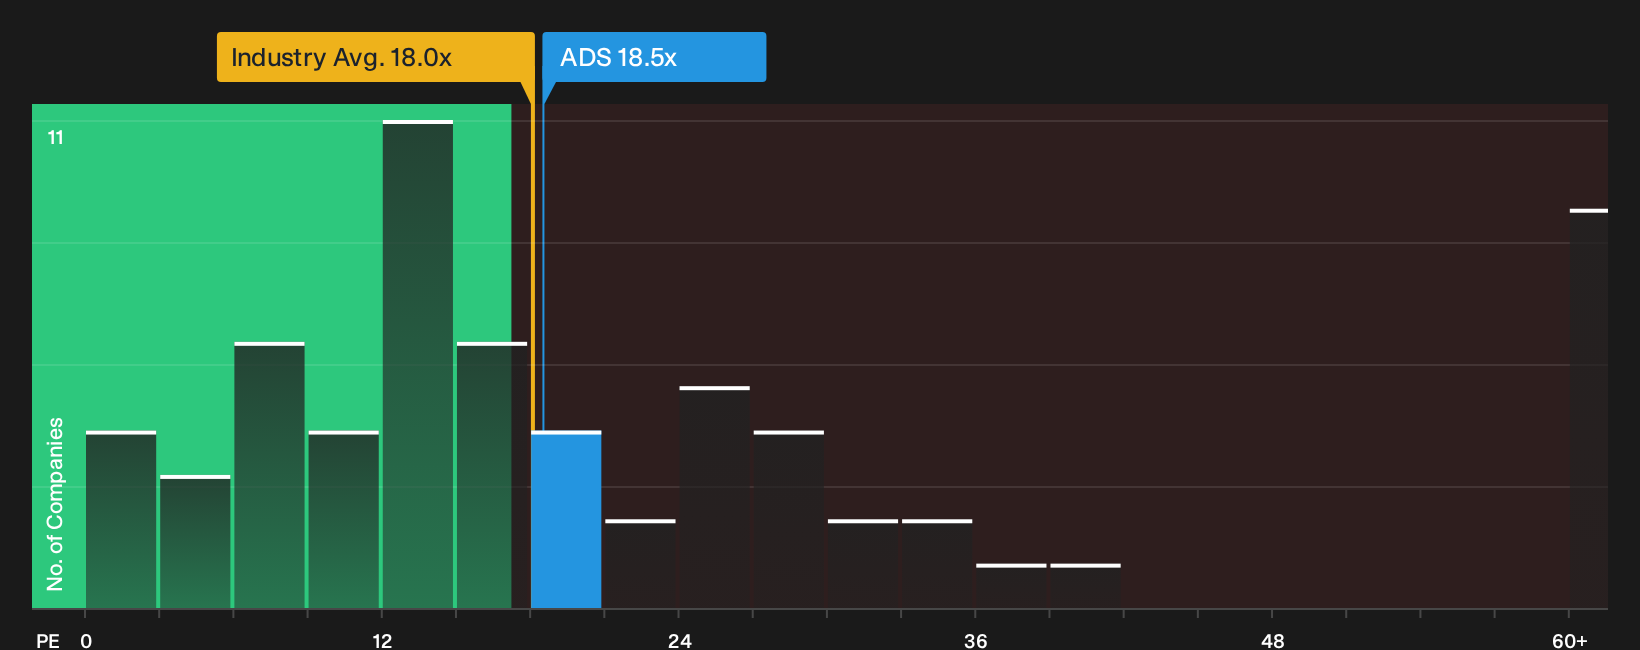
The DCF story presents adidas as heavily undervalued, with the stock at €146.50 compared with an estimated future cash flow value of €347. A simple P/E snapshot tells a different story. At 18.5x earnings versus a fair ratio of 13.7x and a peer average of 12.5x, investors are paying a richer multiple. That gap points to higher valuation risk if growth or margins fall short. Which lens do you consider more useful for your own hurdle rate?
See what the numbers indicate about this price in our valuation breakdown with See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Sentiment around adidas is clearly split, with real concerns sitting alongside genuine optimism about what could go right next. Act quickly, pressure test the numbers yourself, and weigh both sides of the story by reviewing 4 key rewards and 1 important warning sign.
Looking for more adidas sized opportunities?
If you only stop at adidas, you risk missing other compelling setups. Put fresh ideas on your radar with a quick scan across different types of opportunities.
- Review selective small caps in the 129 elite penny stocks with strong financials to explore higher risk opportunities filtered by focused financial criteria.
- Look for value-driven entries and see which companies appear in the 184 high quality undervalued stocks where quality fundamentals are paired with conservative pricing.
- Explore the 226 resilient stocks with low risk scores to find candidates with balance sheets and risk scores designed to help keep surprises in check.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com