


WD-40 (WDFC), What Is Drawing Fresh Attention Now?
WD-40 (WDFC) has drawn fresh attention after recent trading left the stock about 19% lower over the past 3 months, despite modestly positive 1-year and year-to-date total returns.
Recent trading hints at fading momentum. The share price is up over the past week but down 8% over 30 days and about 19% over 3 months, while WD-40’s 1-year total shareholder return remains slightly positive, suggesting mixed sentiment around future growth and risk.
Scan beyond WD-40’s mixed momentum and line up other high quality balance sheet plays using our curated list of solid balance sheet and fundamentals (24 results) for comparison.
After a near 19% slide in three months yet slightly positive 1-year returns, WD-40 now poses a straightforward question: Does the current price still compensate you for the risks on the table?
Most Popular Narrative: 26.7% Undervalued
Against WD-40's last close of $199.17, the most followed narrative anchors on a fair value of about $271.67, so the current pullback is being framed as a discount that hinges on how the business handles growth, mix and costs over the next few years.
The company's focus on premiumization of products, with targets for a compound annual growth rate for premium products exceeding 10%, is presented as a potential driver for improving net margins by shifting the product mix towards higher-margin offerings.
WD-40’s strategy to divest its less profitable home care and cleaning brands is described as a move that could position the company as a higher growth and higher gross margin enterprise, with the aim of ultimately improving operational margins and net margins once complete.
See why 9 investors see WD-40 as 27% undervalued.
Result: Fair Value of $271.67 (UNDERVALUED)
Still, the narrative can quickly look different if input costs squeeze margins for longer than analysts expect or if the planned homecare divestiture is delayed.
Find out about the key risks to this WD-40 narrative.
Another View: WD-40 Looks Expensive On Earnings
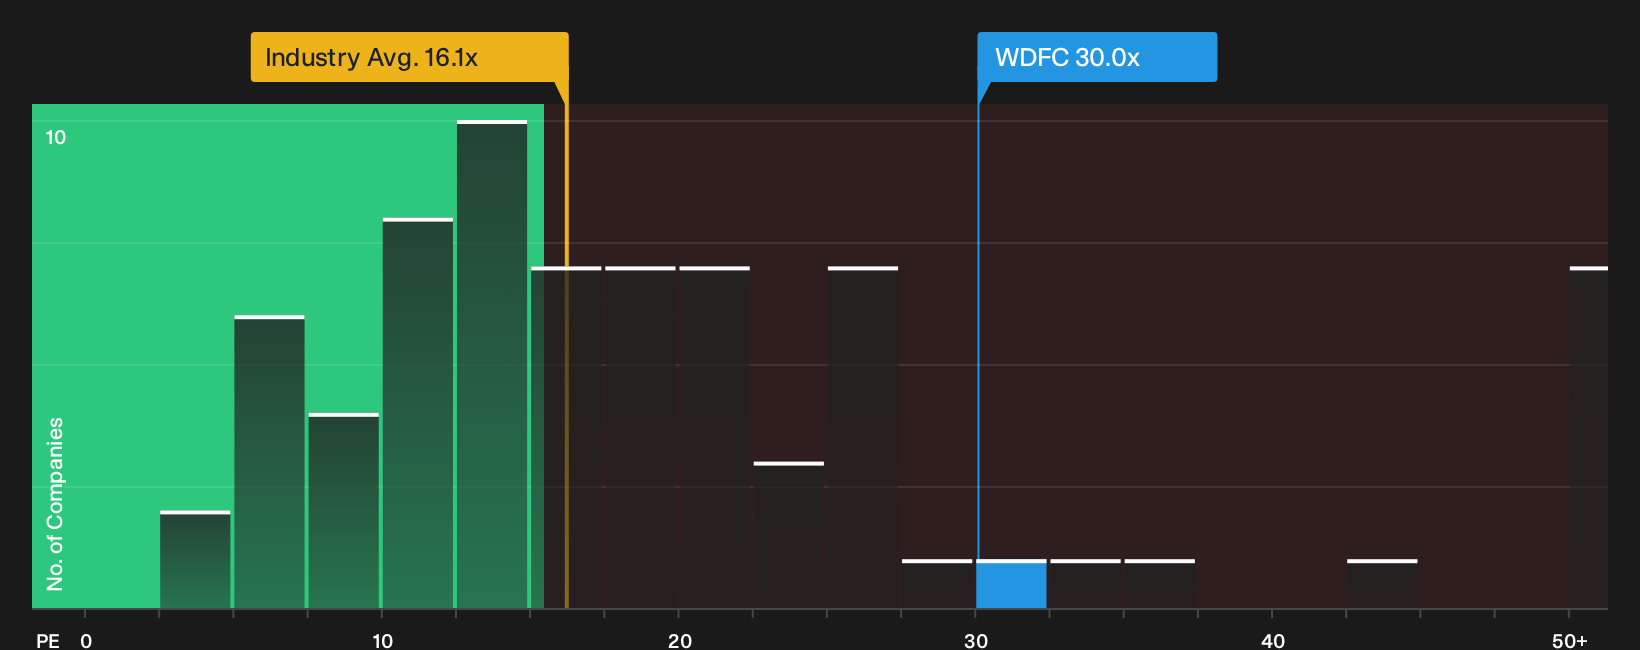
While the leading WD-40 narrative leans on a fair value of $271.67, the current P/E of about 30x paints a very different picture. The fair ratio sits closer to 14.9x, and both the global Household Products industry at 16.1x and peers at 20.5x trade on lower multiples. That points to a rich valuation that could amplify downside if expectations slip. The question is which signal to focus on.
See what the numbers say about this price in our valuation breakdown See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Sentiment around WD-40 is clearly split, so move quickly from reading to testing the numbers yourself and see what stands out in the rewards data 3 key rewards
Looking for more WD-40 investment ideas?
If WD-40 has you thinking more broadly about your portfolio, use the Simply Wall Street Screener to spot fresh opportunities before they move.
- Target resilient performers by scanning a curated set of 30 resilient stocks with low risk scores that aim to keep portfolio volatility under control.
- Hunt for mispriced quality with a focused shortlist of 32 high quality undervalued stocks that combine fundamentals with attractive valuations.
- Surface overlooked potential using our expertly filtered 16 high quality undiscovered gems that many investors may not be watching yet.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com