


Why Roche Holding (SWX:ROP) Is Back In The Spotlight
Roche Holding (SWX:ROP) has been in focus after a fresh research deal with Atavistik Bio, which includes a US$70 million upfront payment and up to US$1.9b in potential milestones and royalties tied to future CVRM therapies.
Roche Holding’s latest research tie up comes on top of a busy September, with fresh positive trial readouts in diabetes and kidney disease, new approvals in eye care and oncology diagnostics, and expanded multiple sclerosis use helping frame the CVRM push.
Within that context, the 90 day share price return of 6.35% and year to date share price return of 10.69% indicate building momentum, while the 1 year total shareholder return of 46.48% and 3 year total shareholder return of 59.52% suggest that recent news is contributing to a longer term rerating story.
Scan how Roche Holding’s recent CVRM and diagnostics momentum compares with other potential opportunities by zeroing in on 618 high quality undiscovered gems in similar health focused niches.
Roche Holding’s share price has already moved on the recent CVRM and diagnostics news, and the reported intrinsic discount sits near 60%. Should investors step in now, or wait for a cleaner entry point?
Most Popular Narrative: 2% Overvalued
According to the most followed valuation narrative on Roche Holding, the current share price of CHF360.30 sits slightly above an estimated fair value of CHF353.34, which implies only a small premium to this model. The gap is narrow enough that attention shifts to how much weight to give the underlying growth, margin and risk assumptions in that framework.
Roche is a high-quality, cash-generative pharma leader with:
✅ Strong fundamentals:
• $80B revenue scale
• ~$26B EBITDA
• ~30% margins
✅ Attractive profile:
• Defensive, dividend (~3%)
• Deep pipeline with multiple catalysts
⚠️ Constraints:
• Moderate growth compared with biotech
• Clinical execution risk
See why 4 investors see Roche Holding as 2% overvalued.
Result: Fair Value of CHF353.34 (OVERVALUED)
Still, Roche Holding faces two clear swing factors: weaker phase III outcomes that undermine pipeline value, and faster biosimilar erosion eating into existing cash flows.
Find out about the key risks to this Roche Holding narrative.
Another View on Roche Holding’s Valuation
The user narrative calls Roche Holding 2% overvalued at CHF360.30 against a fair value of CHF353.34. Our DCF model points the other way. It prices the stock at a future cash flow value of CHF893.70, which implies the current quote is trading at a large discount to that cash flow stream.
Both cannot be right at the same time. The key question is whether you trust the near term earnings based lens or the longer dated cash flow path that the SWS DCF model is applying to Roche Holding’s pipeline and margins.
Look into how the SWS DCF model arrives at its fair value.Look into how the SWS DCF model arrives at its fair value.
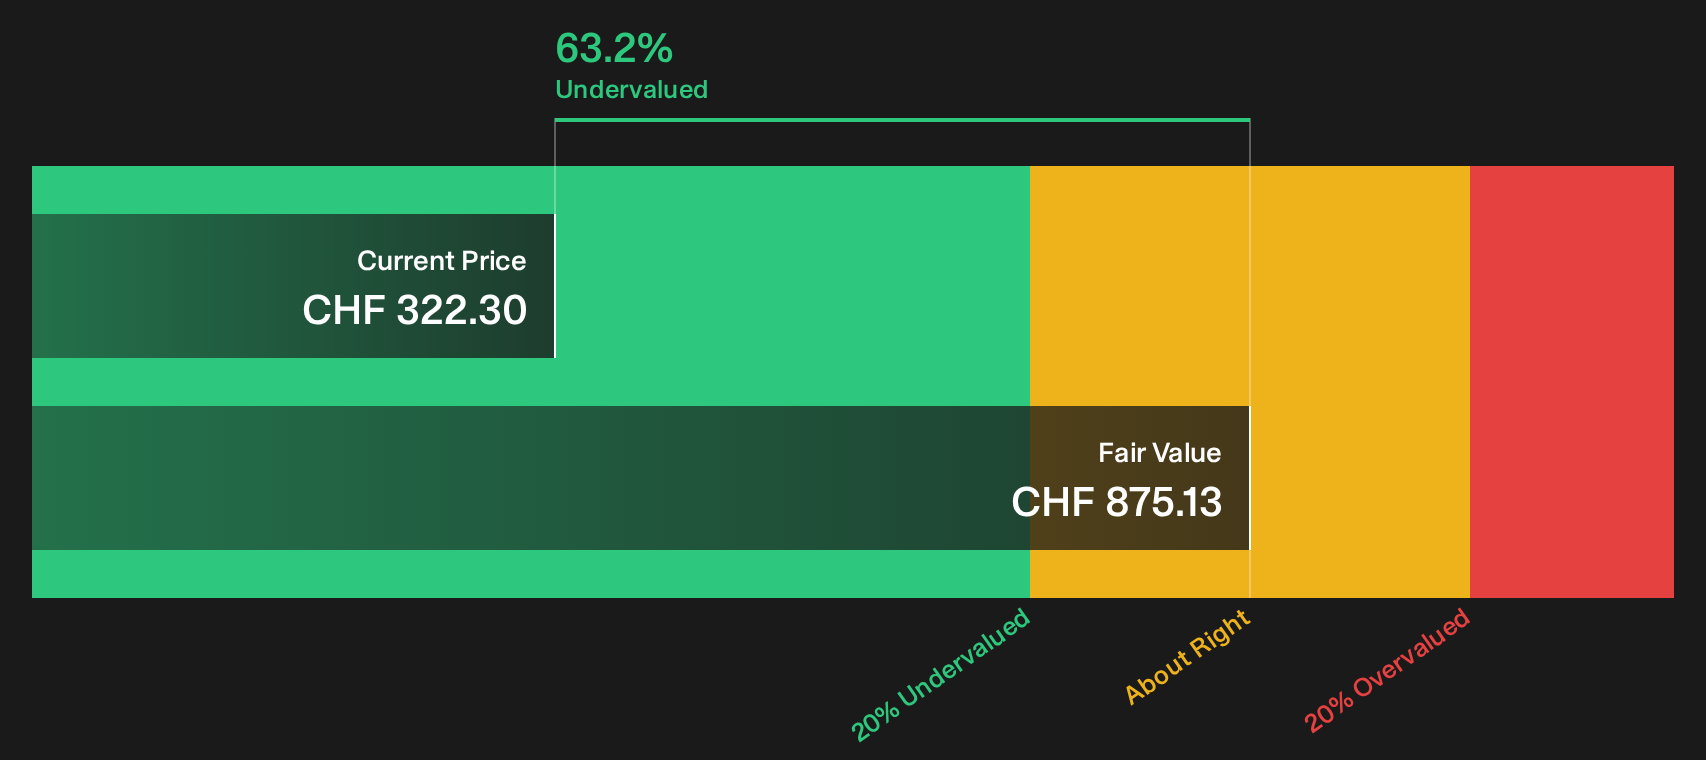
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Roche Holding for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 184 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Mixed signals on Roche Holding so far. If you want to move before sentiment shifts again, stress test the thesis against the 3 key rewards and 1 important warning sign.
Looking for more investment ideas beyond Roche Holding?
If Roche Holding has sharpened your focus on quality, do not stop here. Use the screener to spot other opportunities that match your risk, income, and value priorities.
- Target durable performers by scanning a 226 resilient stocks with low risk scores that may help limit portfolio shocks when markets turn volatile.
- Hunt for value by filtering through a 184 high quality undervalued stocks that can highlight companies trading below what their fundamentals suggest.
- Build a cash flow backbone by reviewing a 160 dividend fortresses that focuses on stronger yields and more robust income profiles.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com