


Delta (DAL) Stock May Be Reasonable After Fresh Dividend News
Delta Air Lines shares have put in a powerful multi year run, and with the stock now near US$84.94, the obvious question is whether that pricing still lines up with what the business is earning. With investors eyeing both the recent momentum and the income stream, the focus shifts to what the current earnings profile can realistically support.
- Over the past 3 years, Delta Air Lines has returned 137.3%, which raises the stakes on whether the underlying earnings justify such a strong gain.
- The recent decision to declare a quarterly dividend of US$0.2150 per share may support the idea that management sees its earnings and cash generation as stable enough to return capital to shareholders.
- Your read on Delta Air Lines is one view; the desks covering it have another. See what analysts think Delta Air Lines's shares could be worth.
The issue now is whether the current share price is adequately supported by Delta Air Lines earnings power when judged against the Fair Ratio benchmark.
If you are testing whether Delta Air Lines' earnings justify its current pricing, it can help to compare that same question across 32 high quality undervalued stocks.
Is Delta Air Lines Still Cheap on Earnings?
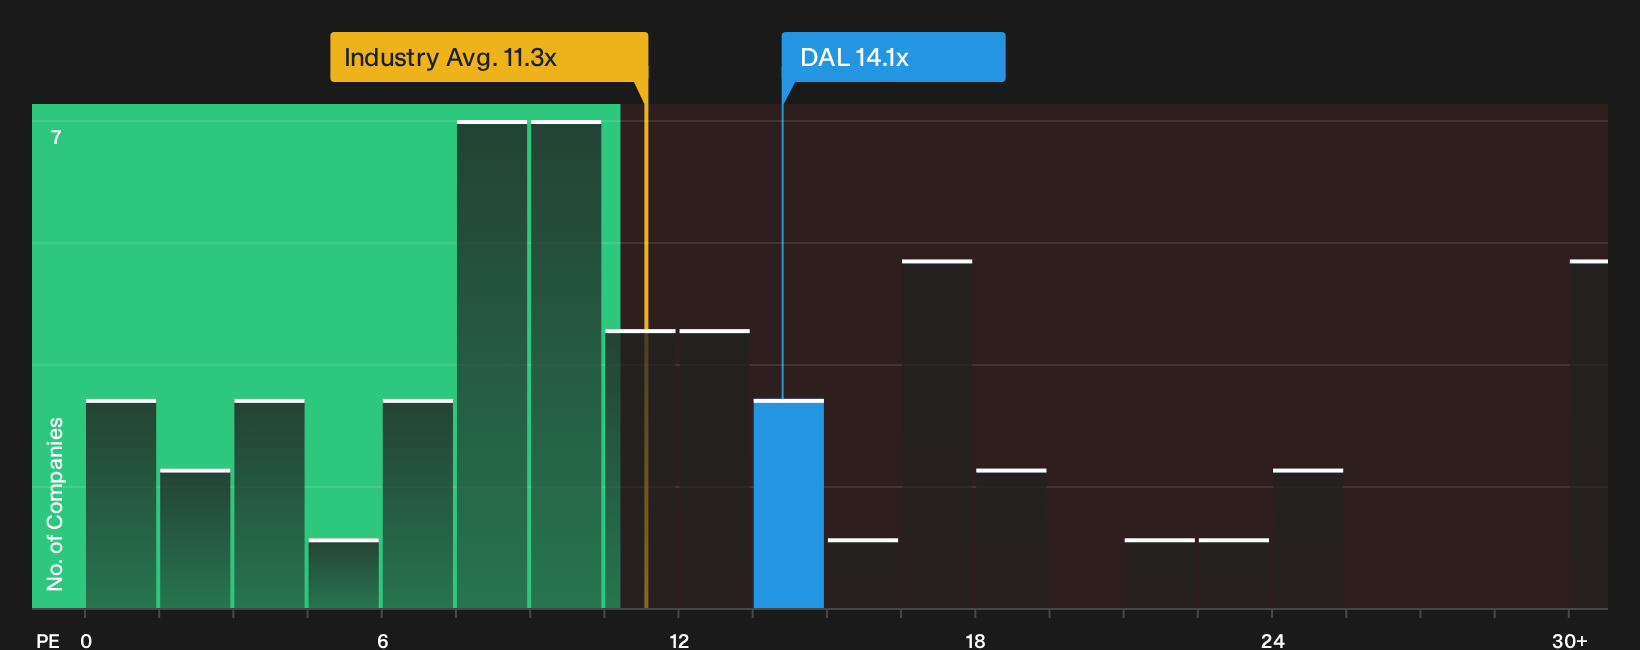
The P/E ratio is a straightforward way to see what you are paying today for each dollar of Delta Air Lines earnings. On this measure, Delta trades at about 14.1x, slightly above the broader airlines industry average of roughly 11.3x and just above the peer group at about 13.5x.
Because the board has recently confirmed a quarterly dividend of US$0.2150 per share, investors are being asked to weigh that income stream against a valuation that sits below the multiple suggested by a Fair Ratio model that factors in Delta Air Lines growth profile, profitability, scale and risk. The current P/E sitting under that tailored benchmark points to the stock being undervalued on this framework, even after the run up in the share price that reflects stronger sentiment around the business. Explore the numbers behind Delta Air Lines's P/E valuation.
The Delta Air Lines Narrative: What Would Justify Today's Price?
Narratives for Delta Air Lines pick up where the valuation puzzle leaves off by setting out the specific growth, margin and earnings paths that would need to play out for the stock to be worth meaningfully more or less than it is today, and they live on Simply Wall St's Community page. Rather than giving a single output from a ratio or model, they unpack the future that number leans on so you can watch how reality lines up over time.
Community views on Delta Air Lines are split between those who see a premium carrier with durable earnings power and those who think the recent run leaves little room for error.
Bull case: 20% undervalued
"Delta is capitalizing on resilient revenue streams such as premium, loyalty, and international segments, which are expected to continue growing..."
Discover why this Narrative puts Delta Air Lines at 20% undervalued.
Bear case: 34% overvalued
"Yet with its early warning about waning travel demand in March, my original assumptions in February re revenue growth and future PE had to be revised downwards..."
Explore why this Narrative puts Delta Air Lines at 34% overvalued.
One more angle on Delta Air Lines that could change your view
The valuation picture only tells part of the story for Delta Air Lines, because our broader checks have picked up potential pressure points that deserve a closer look before you decide how to frame this stock. Take a closer look at 2 warning signs before settling on a valuation.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com