


Equifax (EFX) Stock Looks Cheap As Shares Stay Down 41%
Equifax shares have dropped sharply over the past year, which puts a fresh spotlight on whether the current valuation lines up with what the company actually earns. With the stock under pressure, the key issue for investors is how much of the recent news flow still supports the earnings power implied in today’s price.
- The share price is down 41.1% over the past year, which puts more weight on the question of whether the earnings profile can justify where the stock trades now.
- New fraud and healthcare credentialing tools can influence how investors think about Equifax’s future earnings, since products that gain traction may support revenue durability and pricing power over time.
- Your read on Equifax is one view; the desks covering it have another. See what analysts think Equifax's shares could be worth.
The issue now is whether the earnings that Equifax generates are strong enough to support its current share price after such a steep pullback.
If you want to test the same earnings question you are asking of Equifax against a broader set of ideas, scan through 32 high quality undervalued stocks.
Is Equifax a Bargain on Earnings?
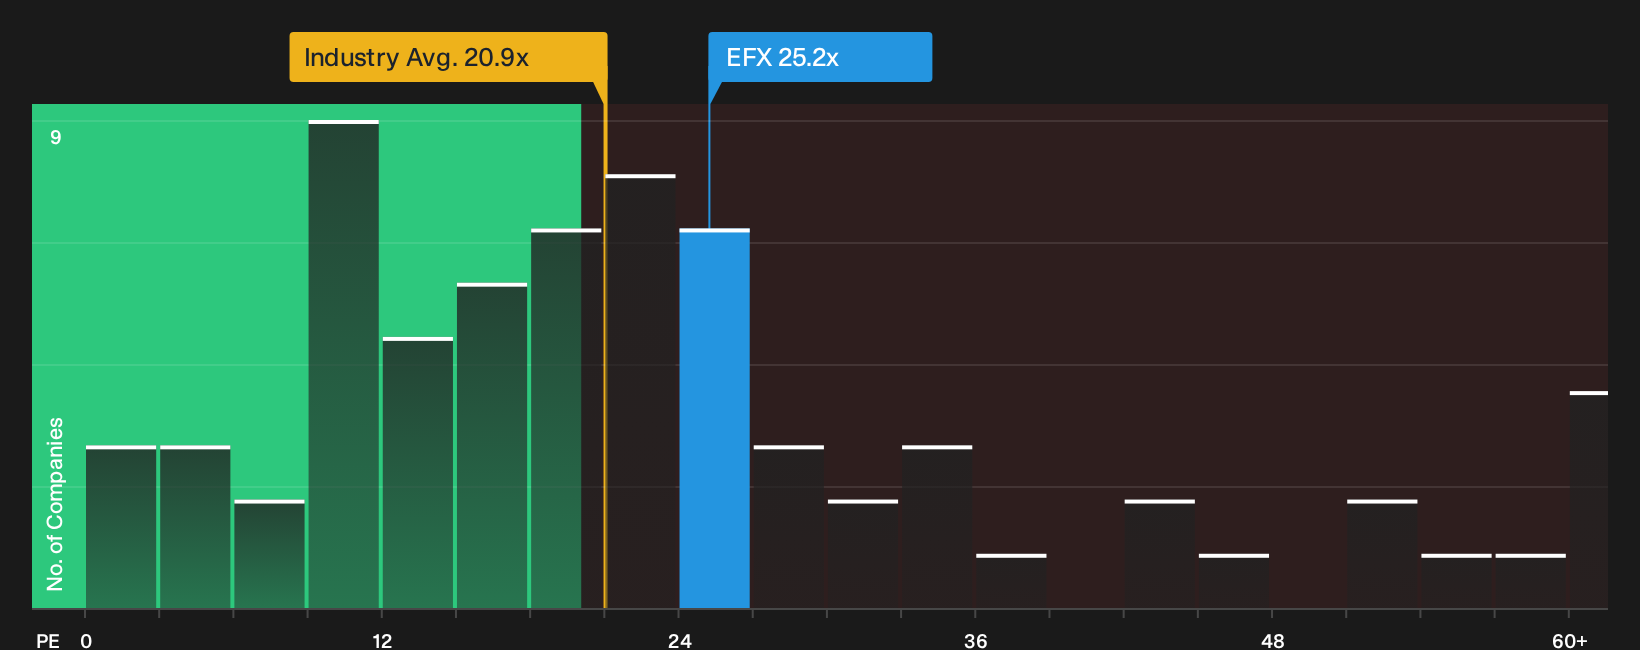
The P/E ratio fits Equifax because earnings still sit at the center of how investors judge this type of information services business. On that yardstick, Equifax trades at about 25.2x earnings, a touch above the peer average near 24.8x and clearly richer than the wider Professional Services industry near 20.9x. That points to a market that is still willing to pay a premium for the equity story even after the share price pullback.
On a more tailored lens that weighs growth expectations, margins, size and risk, the multiple that would typically be expected for Equifax screens higher than where the stock trades today. This suggests the shares look undervalued on this framework. Because the new fraud and healthcare credentialing products sharpen the earnings narrative, the current 25.2x P/E can read as a discount to what the business profile might justify if those tools gain traction. To see how large that gap is in P/E terms, you can explore the detailed valuation workup for Equifax. Explore the numbers behind Equifax's P/E valuation.
The Equifax Narrative: What Would Justify Today's Price?
Simply Wall St Narratives pick up where the Equifax valuation question leaves off. They spell out the specific growth, margin and earnings paths that would need to play out for Equifax's share price to look meaningfully higher or lower than it does today. Instead of a single multiple or model result, each one lays out the assumptions behind its fair value so you can track how those hold up as actual numbers arrive.
One of the top community narratives on Equifax: 31% undervalued
"Rapidly growing Work Number records, now at 217 million active records with 108 million unique Social Security numbers, along with high margin Workforce Solutions revenue..."
Discover why this Narrative puts Equifax at 31% undervalued.
One more Equifax factor to check before making a move
There is a whole other lens on Equifax that sits outside today’s P/E debate, which is where professional analysts think the earnings profile could land a few years from now. Explore where analysts expect Equifax to be in a few years.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com