


Does F 35 Radar Contract Change The Bull Case For Northrop Grumman Stock?
- Northrop Grumman has received a US$123.8 million U.S. Navy contract to produce 67 APG-85 radars for the F-35 program, providing production visibility through February 2031 across Air Force, Marine Corps and Navy fleets.
- The award highlights ongoing demand for advanced sensor systems and extends Northrop Grumman’s workload on a high profile platform, which can support planning around capacity, costs and program execution over several years.
- We will now consider how Northrop Grumman’s broader investment narrative could be influenced by this long dated APG-85 radar award.
Scan defense contractors that, like Northrop Grumman with this APG-85 radar contract, combine contract visibility with potential re rating catalysts using our hand picked 30 resilient stocks with low risk scores
Northrop Grumman Investment Narrative Recap
To own Northrop Grumman, you need to be comfortable with a defense heavyweight that leans on long duration U.S. and allied programs and a US$105b backlog, while managing execution on complex fixed price work. The recent APG 85 radar award adds contract visibility into 2031, but it is relatively small beside flagship efforts like B 21, Sentinel and national security space.
Right now, the near term story still revolves around converting that pipeline into solid margins and free cash flow despite high planned capex and mixed 1 year share performance, with the stock down about 12.7%. The biggest operational risk is cost or schedule slippage on large, fixed price contracts that could pressure segment profitability.
Among recent developments, the focus on expanding munitions and solid rocket motor capacity through multi year missile acceleration agreements, worth up to US$10b over seven years, is highly relevant to this radar news. Both point to Northrop Grumman leaning into long run production work that can support scale, factory utilization and learning curve benefits if execution stays tight.
For you as an investor, those missile and propulsion agreements, alongside radar awards like APG 85, form a cluster of potential catalysts around higher volumes and a richer mix of mature programs. The flip side is clear: heavy upfront investment and a high debt load require that these commitments translate into sustained, profitable output rather than margin drag.
Northrop Grumman's current earnings of $4.5b are set against analyst forecasts for $4.7b of profit by 2029, which implies an earnings increase of about $0.2b. The same models assume a 6.0% yearly revenue growth rate to reach about $51.1b of sales in 2029.
Uncover why Northrop Grumman's fair value indicates a 27% potential upside to its current price before that discount to Northrop Grumman closes.
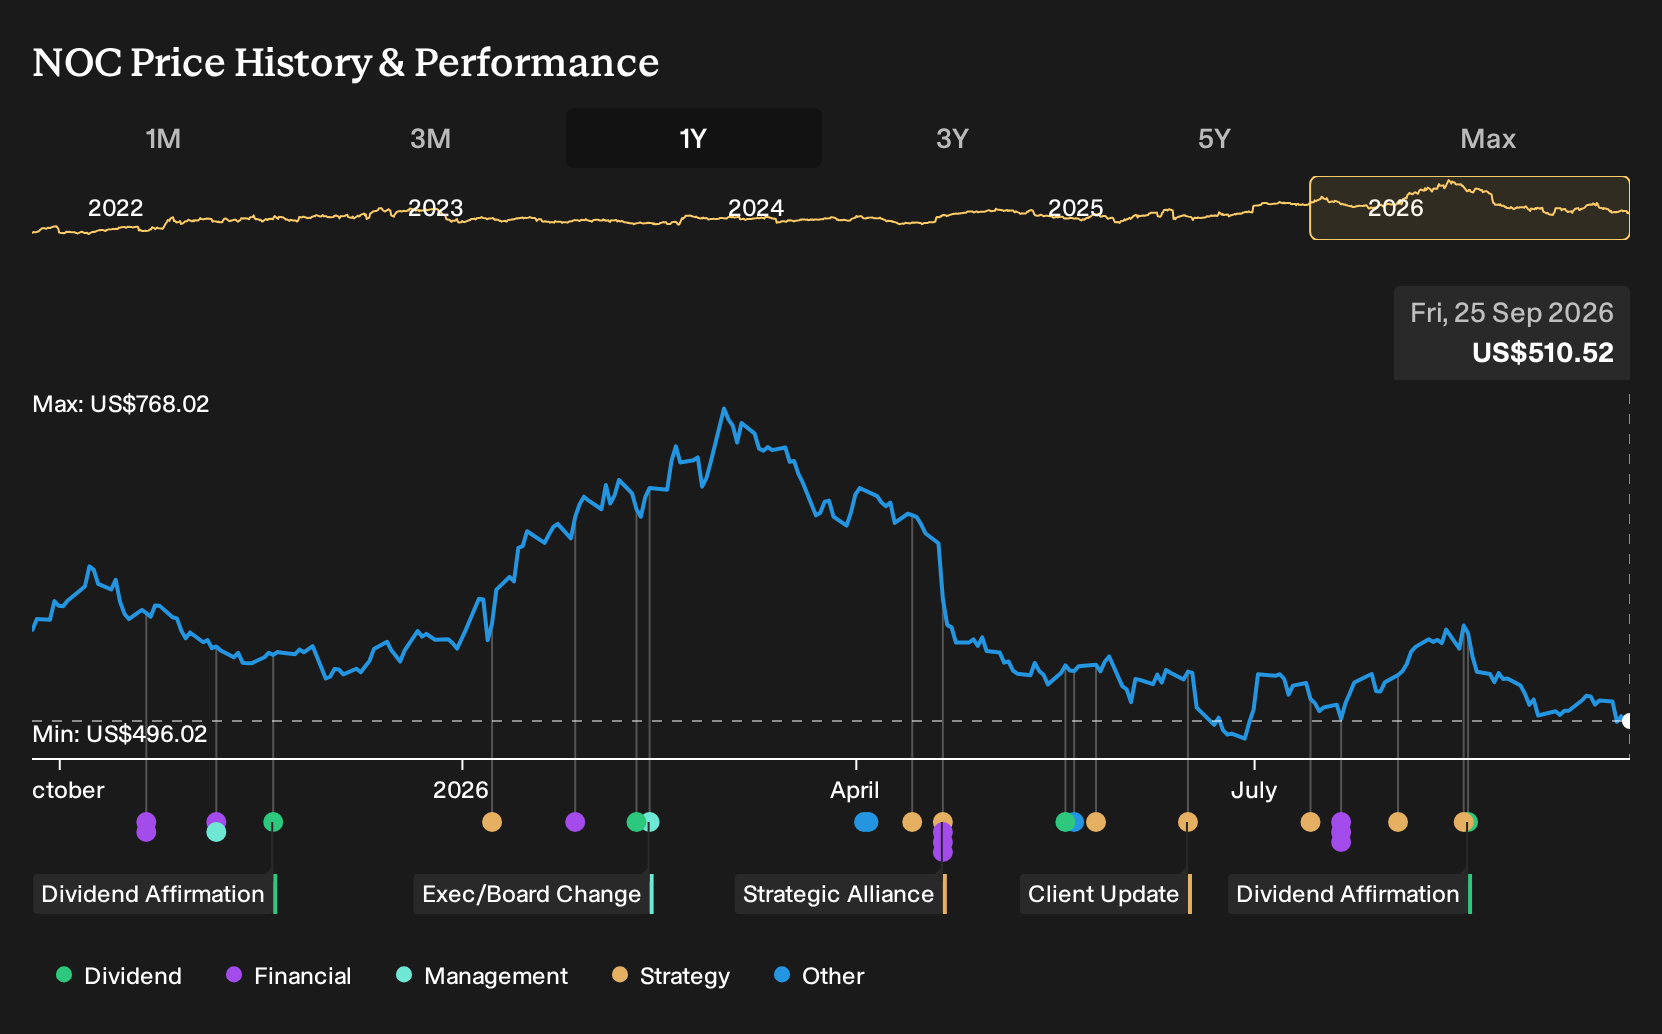
Exploring Other Perspectives
Three fair value estimates from the Simply Wall St Community cluster between about US$644.9 and US$661.5 per share, which already suggests tight but not identical views on Northrop Grumman. Those private investors are not pricing in this radar contract yet. You should weigh that against program execution risks, budget decisions and defense spending catalysts, and then explore more of those differing opinions.
Explore 2 other Northrop Grumman fair value estimates, including one that suggests as much as 30% potential increase from the current price.
The Verdict Is Yours
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Northrop Grumman research is our analysis highlighting 4 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Northrop Grumman. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Northrop Grumman's overall financial health at a glance.
Looking for more investment ideas beyond Northrop Grumman?
Once you have a view on Northrop Grumman, it can help to widen the lens and see how other businesses stack up on quality, income potential and balance sheet strength. The Simply Wall St Screener gives you a quick way to scan for candidates that fit your own risk, return and income preferences.
- If you want capital growth backed by fundamentals, start with a curated set of underpriced opportunities through 32 high quality undervalued stocks.
- For investors who prioritize reliable income, focus on companies with higher yields and solid cash coverage using the 8 dividend fortresses.
- When resilience matters most, filter for financially robust businesses with low risk profiles via the list of solid balance sheet and fundamentals (24 results).
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com