


FuelCell Energy (FCEL) Stock Looks Fully Priced Following Its 109% Run
FuelCell Energy has delivered a sharp share price swing over the past year, which puts fresh attention on a basic question for you as an investor. Is the current US$16.49 price tag adequately supported by the company’s sales, especially given the recent mix of legal headlines and policy-related optimism?
- The stock has gained 108.7% over the past year, which places significant focus on whether the underlying revenue base can justify that kind of move.
- Class action claims over earlier manufacturing and financial disclosures, alongside the one off charge linked to a key equipment contract, highlight how missteps around production economics can affect expectations for future sales quality and profitability.
- There is a second opinion on FuelCell Energy worth weighing. See what analysts think FuelCell Energy's shares could be worth.
The issue now is whether FuelCell Energy’s current market value lines up with its sales when set against the Fair Ratio benchmark.
If FuelCell Energy has put valuation back on your radar, a focused stock screen is a clean way to widen your research beyond this one story using 40 power grid technology and infrastructure stocks.
Has FuelCell Energy Run Too Far on Sales?
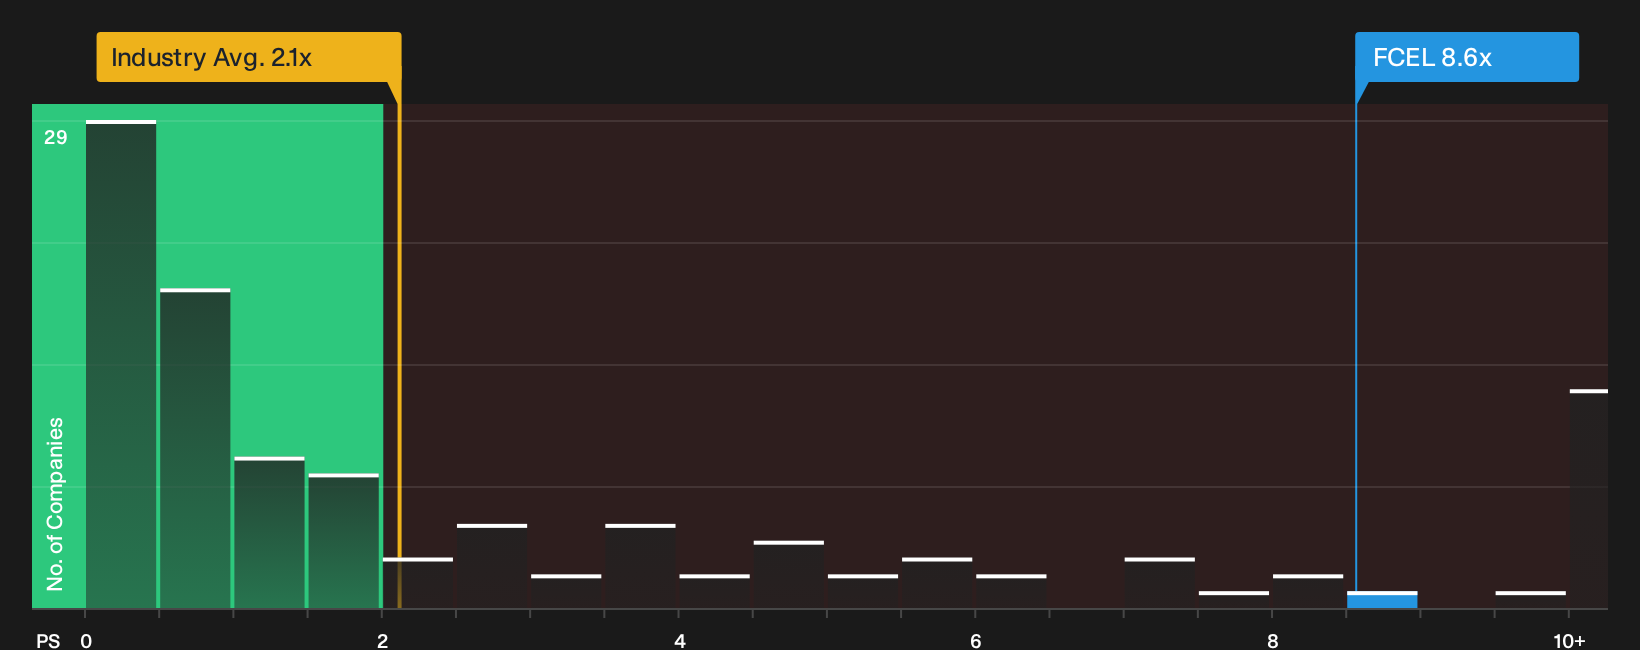
The price to sales ratio suits FuelCell Energy because the business is still loss making and investors are effectively paying for revenue rather than earnings. On this measure, the stock trades on a P/S of 8.6x, which is well above the Electrical industry average of 2.1x and also ahead of the peer group at about 1.9x. That gap suggests buyers today are paying a rich ticket for each dollar of current sales.
The Fair Ratio framework, which aligns the P/S multiple with FuelCell Energy’s specific mix of growth expectations, margins, size and risk, also flags a valuation that screens as overvalued. Because the model is heavily penalising the firm’s past losses and revenue quality, the implied fair level is better read as a warning signal than a precise target, especially after the recent class action claims around manufacturing disclosures and contract economics. Those legal issues sit uncomfortably alongside such a full revenue multiple and leave the share price highly sensitive to any disappointment in future top line delivery. Explore the numbers behind FuelCell Energy's P/S valuation.
The FuelCell Energy Narrative: What Would Justify Today's Price?
FuelCell Energy Narratives pick up where the valuation puzzle leaves off by spelling out what kind of future growth, margins and earnings profile would need to unfold for the stock to be worth materially more or less than today’s price. They sit on Simply Wall St’s Community page. Instead of giving a single output or ratio, these scenarios unpack the revenue and profit path that sits behind it so you can watch how reality lines up over time.
Bulls and bears on FuelCell Energy are reading the same data center story but reaching very different conclusions on what you are really paying for.
Bull case: 20% undervalued
"The partnership with Diversified Energy to deliver up to 360 megawatts to data centers in Virginia, West Virginia, and Kentucky is anticipated to drive significant revenue growth as it positions FuelCell Energy at the forefront of powering AI and high-performance computing sectors..."
Discover why this Narrative puts FuelCell Energy at 20% undervalued.
Bear case: 106% overvalued
"Despite high-profile commercial partnerships and global decarbonization policies that offer a favorable environment for fuel cell adoption, FuelCell Energy's persistent negative net margins, ongoing restructuring, and a need to rightsize operations may continue to pressure profitability and force further capital raises, diluting future earnings per share..."
Explore why this Narrative puts FuelCell Energy at 106% overvalued.
Before you act on FuelCell Energy’s valuation, there is one more angle to check
Price tags and narratives only tell part of the story for FuelCell Energy, since independent checks have also flagged specific risk factors that deserve your attention before you commit fresh capital. Take a closer look at 3 warning signs (2 major) before settling on a valuation.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com