


Did Dividend Increase Just Shift IDACORP (IDA) Stock Investment Narrative?
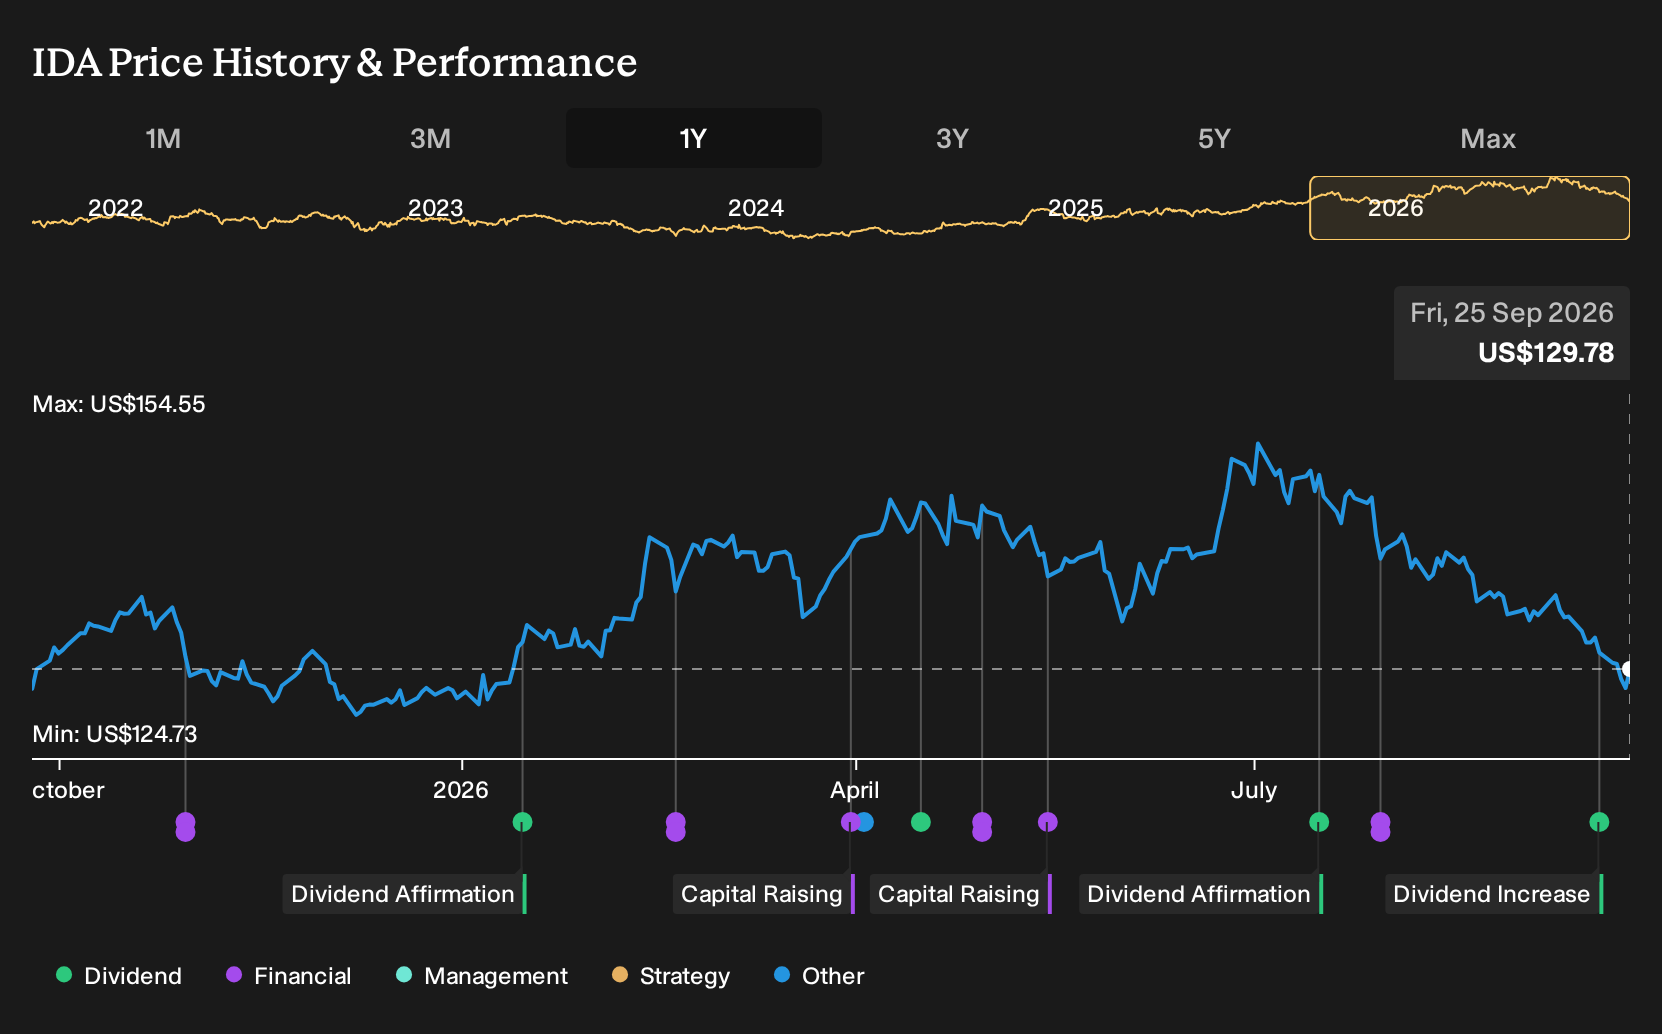
- IDACORP, Inc. previously reported that its Board of Directors approved a regular quarterly cash dividend of $0.90 per share, which indicates an annualized dividend of $3.60 per share, with specific key dates to be set in the fourth quarter of 2026.
- The higher dividend commitment ties shareholder payouts more closely to IDACORP's regulated cash generation needs. This reinforces the importance of cost control, capital planning, and regulatory outcomes for future payout capacity.
- This article will examine how IDACORP's investment narrative is shaped by the higher regular dividend level approved by the Board of Directors.
IDACORP Investment Narrative Recap
To own IDACORP, you need to be comfortable with a regulated utility leaning on steady demand growth in Idaho and Oregon while managing heavy infrastructure spending and weather risk around hydro. The higher US$0.90 quarterly dividend signals confidence in regulated cash generation, but it also tightens the link between payout capacity, rate decisions, and project execution over the next few years.
In the short term, the key swing factor is how regulators treat IDACORP's rising capital needs for transmission, storage, and new generation to meet large-load interest. The enlarged dividend does not materially change that in the near term. It mainly raises the bar for free cash flow and financing, which interacts directly with the existing risk around interest coverage and external funding reliance.
The most relevant context for this dividend move is the existing concern that IDACORP's payout is not well covered by free cash flows and that interest costs are not comfortably covered by earnings. A higher regular dividend increases the fixed cash commitment to shareholders. That puts more pressure on the utility to align rate base growth, debt costs, and project timing with actual cash generation.
For you as a shareholder, the question becomes whether IDACORP can continue to fund its transmission and generation buildout, serve strong load growth, and still service higher dividends without stretching the balance sheet. Execution on rate cases, cost control, and resource planning already sits at the center of the thesis. The new US$3.60 annual dividend simply makes those same catalysts and risks more visible in the income stream.
IDACORP's current analyst narrative points to revenues of US$2.4b and earnings of US$510.4 million by 2029, based on assumed yearly revenue growth of 10.9% and an earnings increase of roughly US$178.6 million from the US$331.8 million reported today.
Uncover why IDACORP's fair value indicates a 22% potential upside to its current price, which could narrow quickly.
Exploring Other Perspectives
Three fair value estimates from the Simply Wall St Community cluster between about US$112 and US$158, which shows how far opinions on IDACORP can stretch. Some members focus on long term demand drivers and capital spending plans. Others flag hydro weather risk and regulatory decisions as potential brakes on future performance. You may want to explore several of these viewpoints before deciding how this higher dividend fits your own thesis.
Explore 2 other IDACORP fair value estimates, including one that suggests up to 22% potential upside from the current price.
Decide For Yourself
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your IDACORP research is our analysis highlighting 3 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for IDACORP. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate IDACORP's overall financial health at a glance.
Looking For More Ideas Beyond IDACORP?
If this dividend reset has sharpened your view on IDACORP, it can be useful to widen the lens and compare it with other income and quality focused opportunities using the Simply Wall St Screener.
- Prefer strong balance sheets and resilient fundamentals over headline yield? Scan our list of solid balance sheet and fundamentals (24 results) for companies that may better match that approach.
- If capital preservation is front of mind and you want businesses with more measured risk profiles, check out our 30 resilient stocks with low risk scores to see which stocks fit that brief.
- For investors hunting for overlooked quality where the story is not yet crowded, review our 16 high quality undiscovered gems and compare those ideas against your thesis on IDACORP.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com