


Heathrow Delay Could Lift Interest In These UK Infrastructure Stocks
Heathrow’s third runway hitting a possible 4 year delay has not just stalled a flagship project. It has reshuffled expectations for who might win or lose from slower airport expansion and shifting UK infrastructure rules. For investors, that pause can create mispricing, as sentiment moves faster than contracts do. This article unpacks the story and highlights 3 UK Infrastructure & Construction Stocks most exposed to the news, all on the potential beneficiary side.
The three stocks below are a sample of the idea, while the full screen surfaced 31 more UK Infrastructure & Construction companies with equally detailed stories that are not covered here.
To go further, head straight into the UK Infrastructure & Construction Stocks screener to identify, filter and analyze potential UK infrastructure and construction opportunities for your watchlist.
Hill & Smith (LSE:HILS)
Hill & Smith plugs directly into the UK Infrastructure & Construction Stocks theme, supplying the physical kit behind roads, barriers and utilities, while also leaning on a broad US and galvanizing footprint that gives this £2.5b business real scale.
Hill & Smith generates most of its income from US Engineered Solutions at about $600 million, with Galvanizing Services and UK & India Engineered Solutions contributing roughly $300 million each, backing its role in real world infrastructure projects.
"Robust demand for engineered infrastructure solutions in the U.S., supported by record order books and multi-year federal and state investments in transportation and electric grid modernization, is expected to drive sustained revenue growth and margin expansion for Hill & Smith's higher-margin platform businesses."
What happens if one pressure point in that story shifts and the expected uplift in profitability arrives more slowly than investors currently assume?
If that timing risk matters to you, read the full narrative for Hill & Smith to see how Hill & Smith’s infrastructure engine could still be accelerating beneath today’s headlines.

Marshalls (LSE:MSLH)
Marshalls sits squarely in the UK Infrastructure & Construction Stocks theme, with its paving, kerbs, drainage and roofing products embedded in public spaces, transport hubs and housing projects across the country.
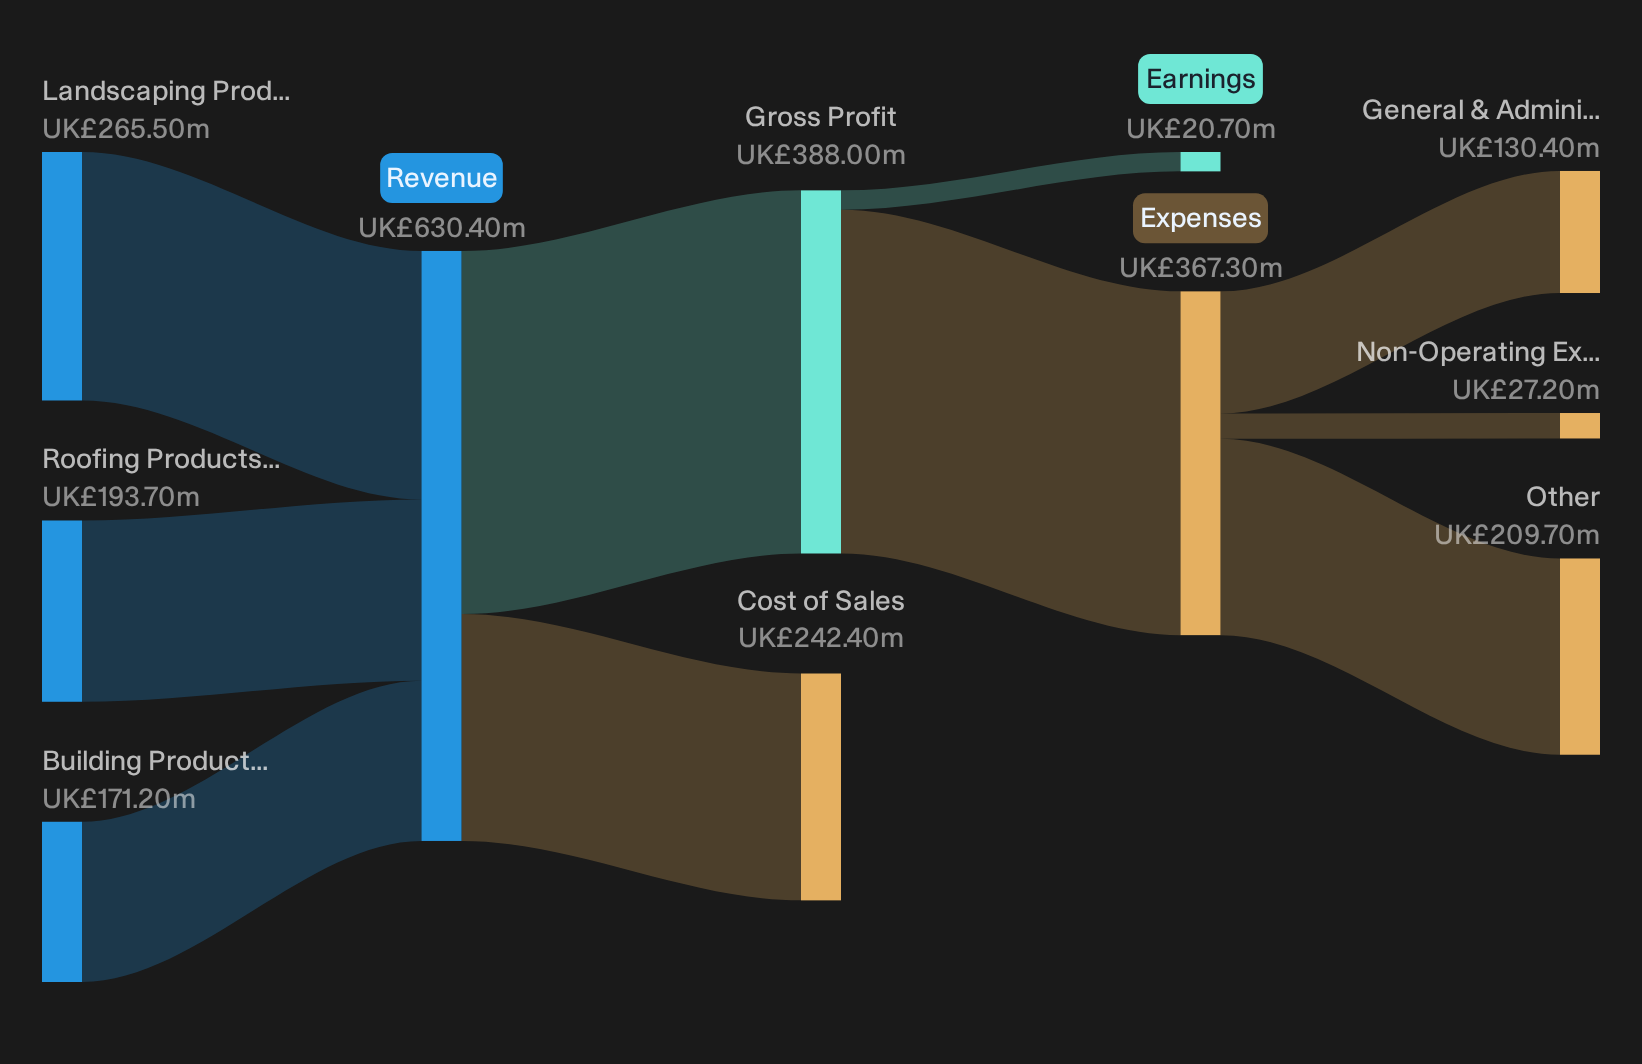
Marshalls manufactures a wide range of paving, kerb, drainage, walling and roofing products used in commercial, public realm and housing schemes. It generated about £265 million from Landscaping Products, £194 million from Roofing Products and £171 million from Building Products, and has a market cap of roughly £389 million.
"As urbanization and climate-resilient development accelerate, Marshalls' portfolio of permeable paving, SuDS solutions, and low-carbon bricks positions it as a supplier for major commercial and public sector projects."
The question for Marshalls is how strongly that climate-focused, higher value mix can influence group margins if one unseen pressure eases.
If that shift in pressure is what you are watching, go straight to the full narrative for Marshalls to see how Marshalls' mix could be quietly resetting expectations.
SigmaRoc (AIM:SRC)
SigmaRoc is a £1.4b quarried materials group supplying aggregates, concrete products and related services that feed directly into infrastructure and construction projects. It generates about £1.05b from construction material products and services across the UK, Ireland and continental Europe.
For investors watching UK Infrastructure & Construction Stocks, SigmaRoc offers exposure to the basic materials that large civil projects consume, and management has started to reshape the portfolio toward higher quality earnings rather than simply focusing on volume.
"The divestment program, which includes selling non-core assets like the concrete operations in the Benelux, is set to refocus the group's footprint on more profitable segments, potentially improving net margins and revenue quality."
The bigger swing factor is how one still developing shift in end market demand ultimately feeds through to volumes, pricing power and margins.
That shift in demand is only half the story, and the full narrative for SigmaRoc shows how SigmaRoc’s portfolio moves could reshape risk and pricing power.

Seeking Alternatives Before The Crowd
Fresh trends move fast, and the stocks leading the next breakout rarely stay under the radar for long. Catch the momentum while it matters and aim to participate early.
- Track cash rich companies quietly building momentum with the list of solid balance sheet and fundamentals (10 results) before they get fully priced in by a wider group of investors.
- Spot potential income anchors by scanning the 1 dividend fortresses and identify which payouts could stay on your radar while yields remain elevated.
- Look for opportunities in the next power build out using the 40 power grid technology and infrastructure stocks and focus on businesses supplying the backbone of future electricity networks.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com