


Is TD Cowen Presentation Altering The Investment Case For Weatherford Stock (WFRD)?
- Weatherford International recently presented at the TD Cowen Annual Energy Conference in Austin, where SVP Luke Lemoine highlighted its drilling, completion, and production service portfolio to institutional investors.
- The conference appearance, coming shortly before Weatherford International’s third quarter earnings call, put fresh focus on how its technology mix and regional exposure align with current customer demand and cash flow risks.
- We will now assess how Weatherford International’s TD Cowen conference messaging around its technology offering could influence the broader investment narrative.
Weatherford International Investment Narrative Recap
To own Weatherford International, you need to believe its shift toward higher margin, technology heavy services can offset softer activity in key international markets and pricing pressure in more commoditised work. The TD Cowen appearance reinforces that story by keeping the focus on managed pressure drilling, complex completions, and production optimisation as the core engine.
The near term swing factor still sits in cash generation and working capital, especially around markets with slower payments such as Mexico. Conference messaging does not change that risk. The coming third quarter call remains the cleaner catalyst, where you can see whether receivables, margins, and order trends line up with the long term technology led pitch.
The upcoming third quarter 2026 earnings call on 21 October now matters more in light of the TD Cowen presentation. Weatherford International used Austin to remind investors of its breadth across drilling, well construction, and production services. The call will show how that portfolio translates into real order intake, utilisation, and operating profit.
For catalysts, the earnings update gives you a read on whether international softness and pricing pressure are stabilising and how management is handling cash collection in Mexico and other higher risk markets. Any detail on cost optimisation, contract quality, or mix shift toward advanced technologies will help you judge how durable the margin story really looks.
Weatherford International’s current analyst story points to revenues of $5.3 billion and earnings of $584.6 million by 2029, based on a projected 2.7% yearly revenue growth rate and an earnings uplift of about $121.6 million from today’s $463.0 million profit base.
Uncover why Weatherford International's fair value indicates a 40% potential upside to its current price, which could narrow quickly.
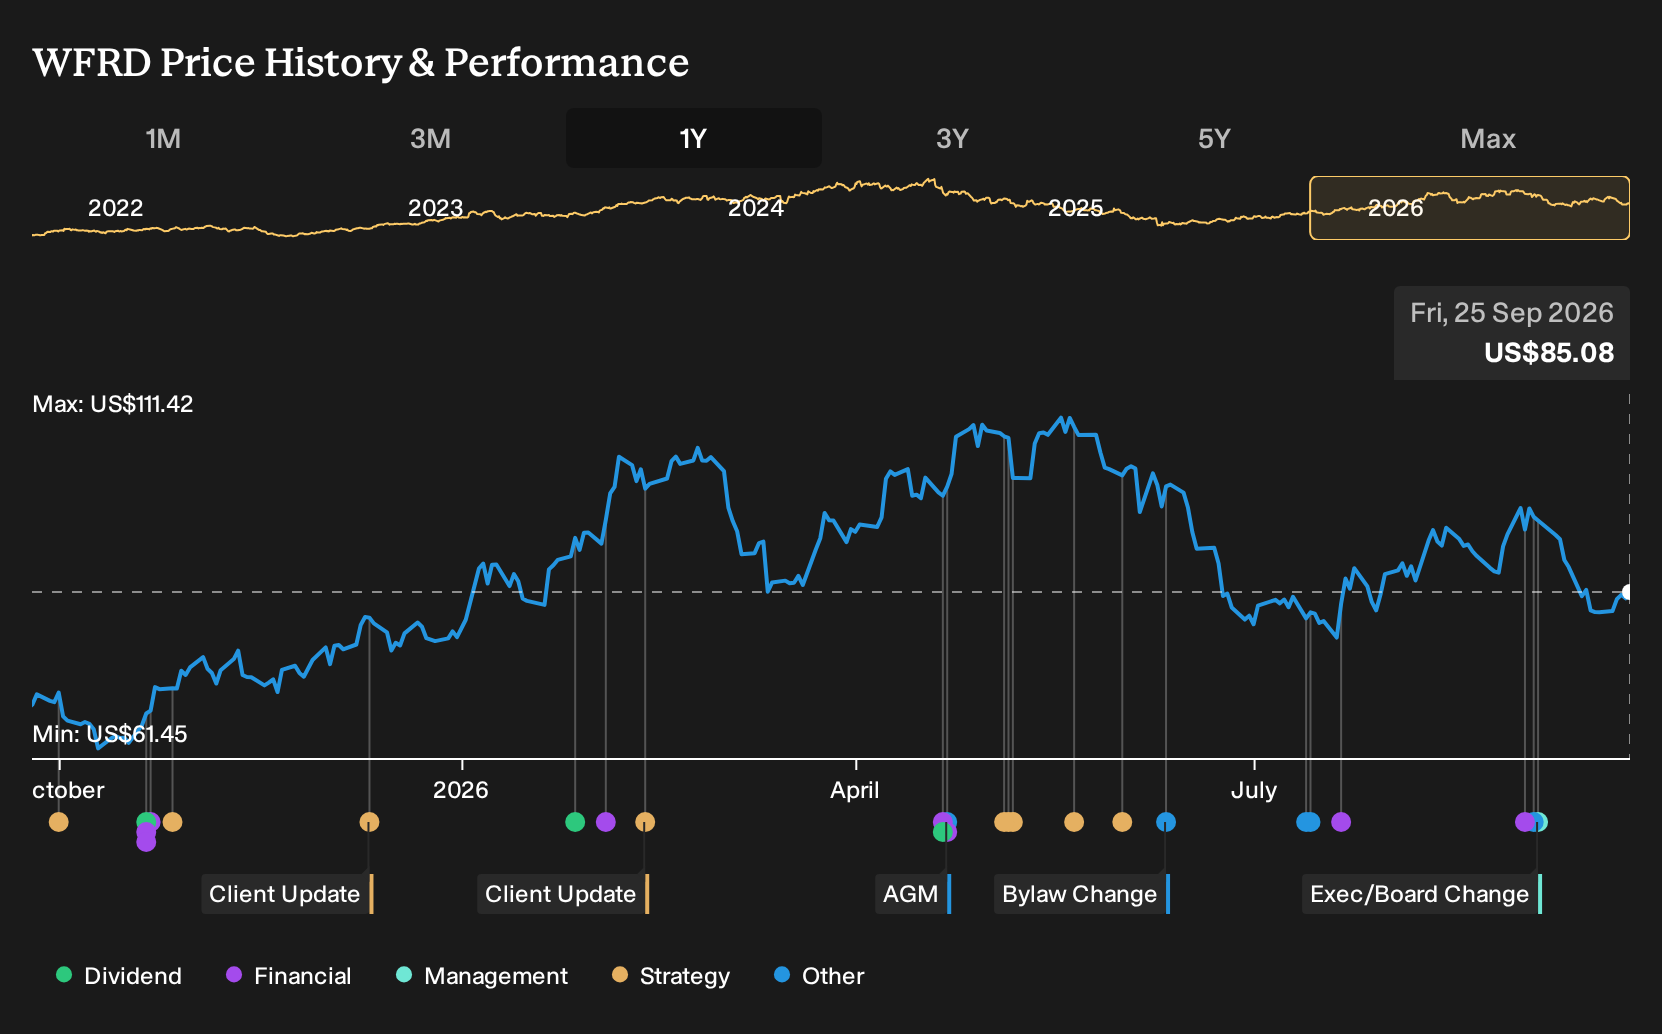
Exploring Other Perspectives
Some of the lowest analysts watching Weatherford International focus less on technology upside and more on whether free cash flow holds up if working capital gets tight. Before this TD Cowen update, that group was working off about $5.3b of 2029 revenue and roughly $607.8m of earnings, painting a more cautious path. Their numbers, and the story behind them, may shift once the conference and October 21 call land.
Explore 5 other Weatherford International fair value estimates, including one that suggests it could be worth just $93.00.
Form Your Own Verdict
Don't just follow the ticker; dig into the data and build a conviction that's truly your own.
- A great starting point for your Weatherford International research is our analysis highlighting 4 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Weatherford International. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Weatherford International's overall financial health at a glance.
Looking For More Ideas Beyond Weatherford International?
If you want to stress test your thesis on Weatherford International, it helps to compare it with a broader set of businesses that share similar balance sheet strength, cash flow profiles, or income potential. The Simply Wall St Screener can help you quickly filter for those kinds of opportunities without getting lost in endless ticker lists.
- If resilience and downside protection are high on your list, scan a focused universe of 30 resilient stocks with low risk scores that pair steadier fundamentals with calmer volatility profiles.
- If you want potential upside with valuation support behind it, review a curated group of 16 high quality undiscovered gems that combine quality metrics with under-the-radar coverage.
- If income is your priority, filter for 8 dividend fortresses that couple 5%+ yields with balance sheets built to support ongoing payouts.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com