


CoreCivic (CXW) Taps Lucibeth N Mayberry As Chief Executive
- CoreCivic (NYSE:CXW) named Lucibeth N. Mayberry as President, CEO and Board Director following Patrick D. Swindle’s resignation for health reasons.
- Mayberry, a long-serving CoreCivic executive, steps into the top role after Swindle’s abrupt departure from the leadership team.
- Swindle’s exit and Mayberry’s appointment place an experienced internal leader at the center of future corporate decision making.
- The leadership change from Patrick D. Swindle to Lucibeth N. Mayberry is an important factor to weigh against our wider work on CoreCivic. Take a look at 3 warning signs (2 major) we have identified for CoreCivic.
This shift at CoreCivic is one example of how leadership changes shape the broader theme of governance risk across other stocks too. It is worth exploring our screener containing 16 high quality undiscovered gems.
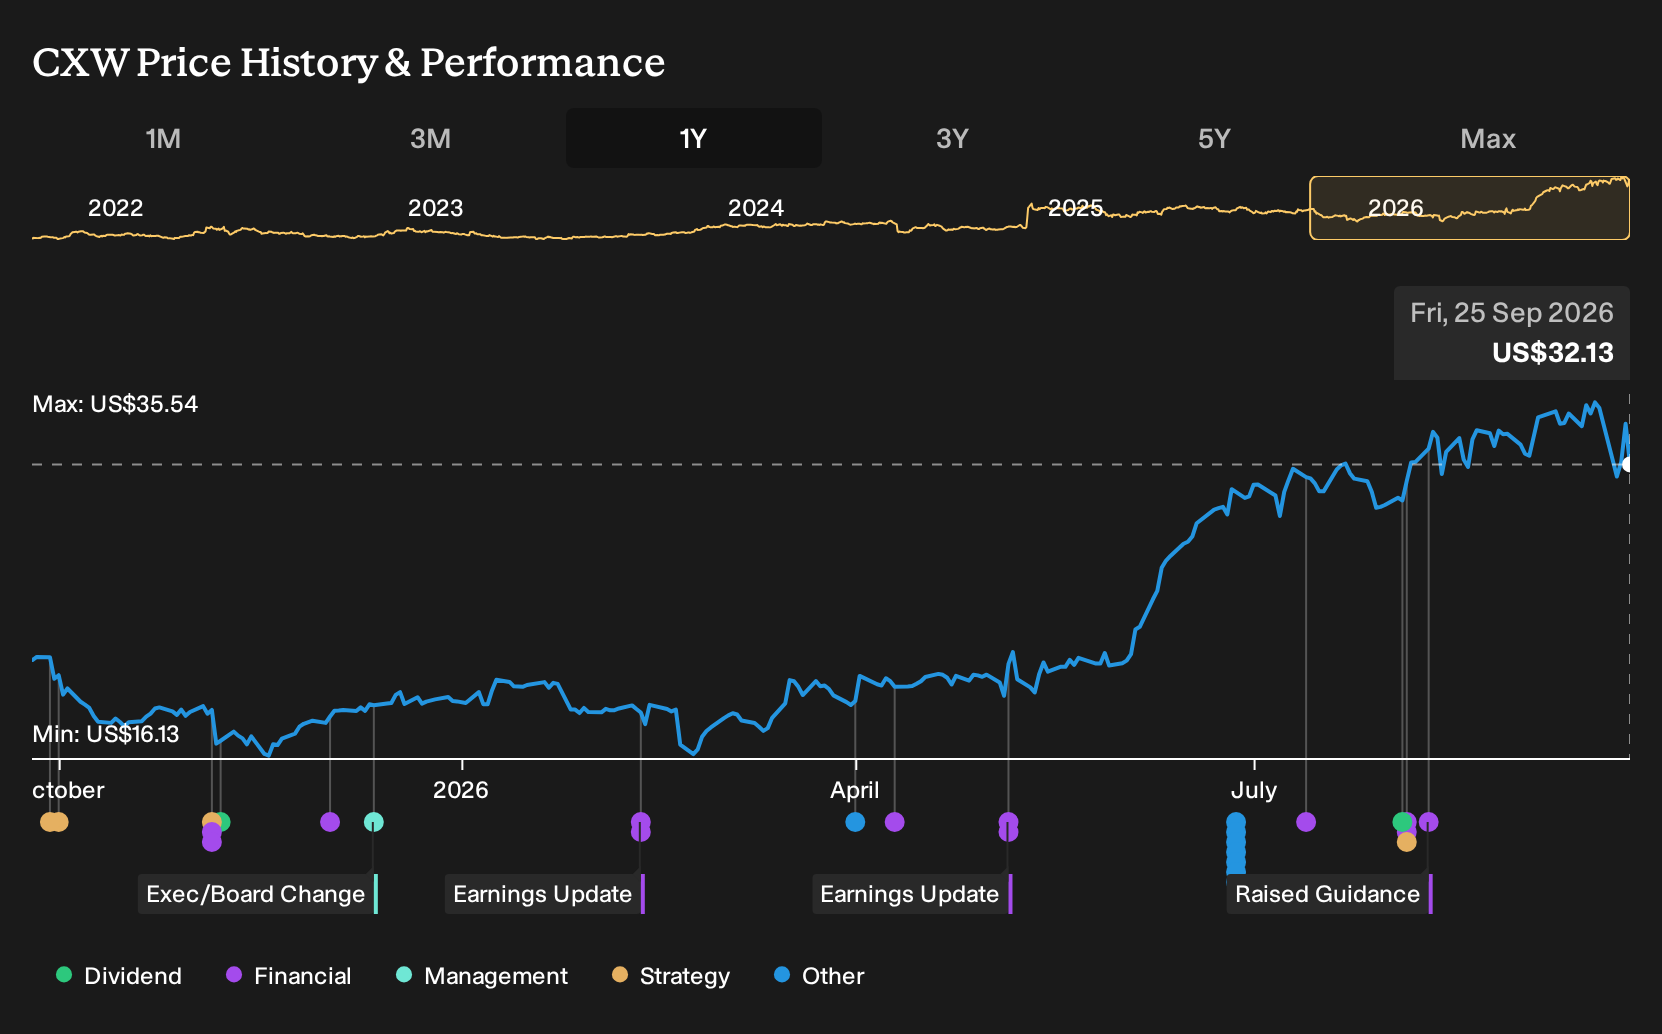
CoreCivic, a US Commercial Services operator with a market cap of about $3.2b, runs partnership correctional, detention, and residential reentry facilities. Leadership choices influence how the business manages long contracts, regulatory scrutiny, and relationships with government customers.
How CoreCivic’s new CEO choice leans into the detention-capacity Narrative
The investment story around CoreCivic hinges on whether it can turn government detention demand and asset readiness into durable cash generation while managing heavy policy and ESG risks. A long-tenured insider moving into the CEO and board seat plugs directly into that question rather than sitting outside it.
"CoreCivic's extensive portfolio of ready-to-activate idle facilities, combined with preemptive investments in staffing and transportation assets, positions the company to quickly capture additional contract awards..."
See how the full story points towards a $41.80 fair value for CoreCivic.
Mayberry has been the architect of strategy, real estate, and innovation at CoreCivic, which ties her closely to the Narrative’s key upside catalyst, rapid activation of detention capacity as contracts arrive. That background supports the idea that the current playbook on asset readiness, reactivations, and potential future facility sales can keep running rather than being reset by an external hire.
The flip side is governance risk. Concentrated exposure to ICE and U.S. Marshals contracts, plus ESG pressure that rivals like GEO Group also face, puts more weight on Mayberry’s judgement on capital spending and contract selection. Analysts have already flagged earnings and balance sheet risks. Any misstep on new deals or reactivation pacing would challenge the “asset-ready growth” storyline.
Thinking in terms of a clear Narrative helps turn a CEO change from background noise into a concrete test of the detention-capacity thesis for CoreCivic.
The CoreCivic question the headlines skip
Share moves get the attention, but the quieter question is what CoreCivic’s stream of cash coming in and out suggests the whole enterprise might reasonably be worth compared with today’s market price. Find out exactly what CoreCivic is worth today based on its cash flows.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com