


Constellation Energy (CEG) Following The Microsoft Deal Still Looks Undervalued
Constellation Energy (CEG) moved back into the spotlight after signing a long term power contract with Microsoft, a deal connected to the relaunch of the Three Mile Island nuclear facility in Pennsylvania.
Recent trading tells a mixed story. Constellation Energy’s share price return is up 3.36% over the past week and 1.52% over 90 days, while the 30 day move is down 4.87% and the year to date share price return has fallen 28.12%, alongside a very large 3 year total shareholder return of 146.04%. This combination suggests long term momentum but a cooler phase in 2026 as investors reassess growth potential and risks around major nuclear and data center power agreements.
Spot potential peers to Constellation Energy in the nuclear and power grid supply chain by scanning our hand picked 40 power grid technology and infrastructure stocks.Constellation Energy now trades well below both analyst targets and some intrinsic value estimates. After this pullback, does the current price still reflect the premium investors once paid for its nuclear and data center exposure, or has it swung too far?
Most Popular Narrative: 24.8% Undervalued
At a last close of $263.27, the most followed narrative pegs Constellation Energy’s fair value closer to $350, which implies a sizeable gap that this view treats as mispricing rather than noise.
CEG is one of the cleanest pure-play ways to own the intersection of nuclear scarcity and AI-driven power demand. The combination of an irreplaceable baseload fleet, accelerating long-term contracting, and a raised earnings trajectory makes the current valuation attractive relative to the multi-year earnings power the company is building.
See why 18 investors see Constellation Energy as 25% undervalued.
Result: Fair Value of $350 (UNDERVALUED)
Still, the narrative could crack if regulatory delays stall nuclear restarts, or if higher leverage after Calpine leaves Constellation Energy with less room for error.
Find out about the key risks to this Constellation Energy narrative.
Another View: Constellation Energy Looks Expensive On P/E
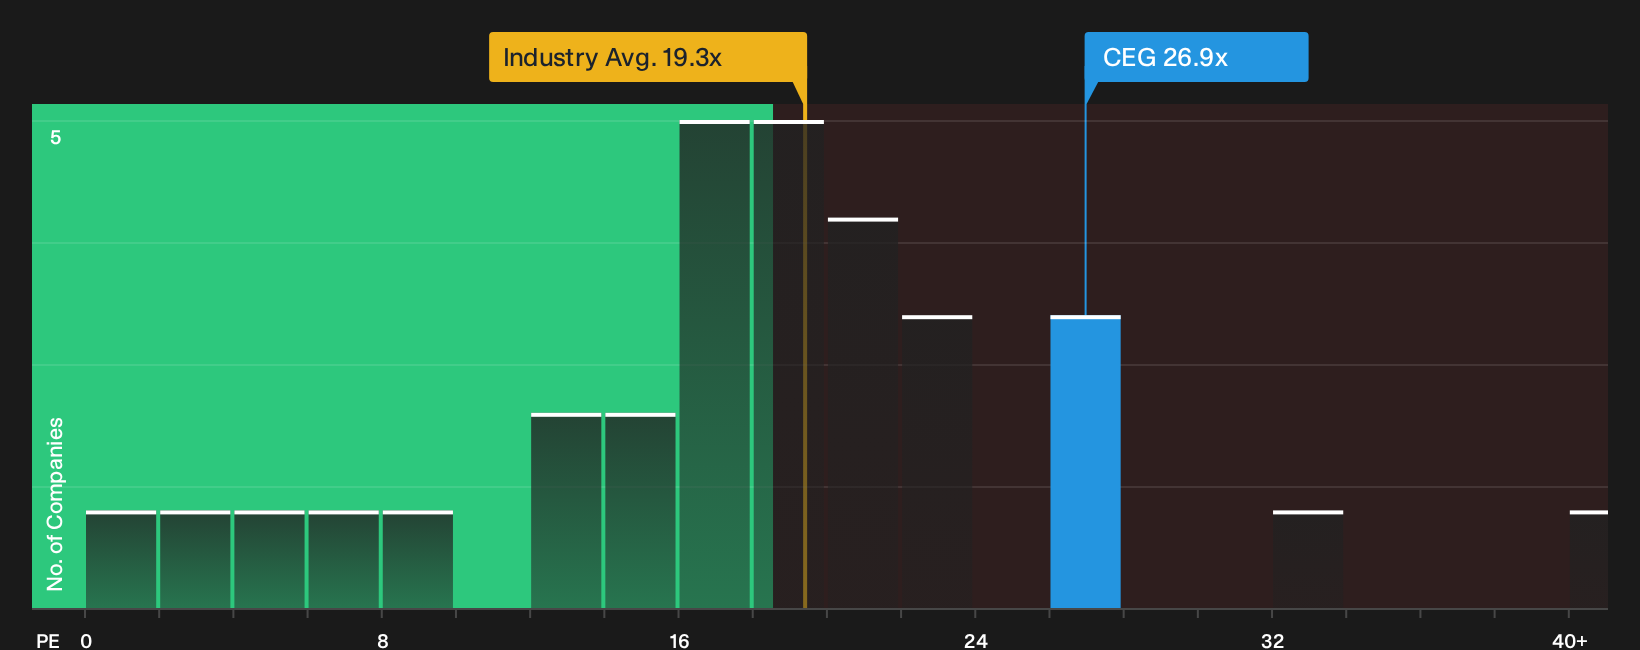
Constellation Energy may look attractive on fair value estimates, but its current P/E of 26.9x sits well above both the US Electric Utilities industry at 19.3x and peer average at 21.1x, even though the fair ratio points closer to 31.7x. Does paying this kind of premium leave enough room for error?
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
The mix of optimism and concern around Constellation Energy is clear, so instead of staying on the sidelines, consider weighing the potential upside and downside for yourself by digging into the 4 key rewards and 2 important warning signs.
Looking for more ideas beyond Constellation Energy?
If Constellation Energy has you thinking about where to put fresh capital next, do not leave it there. Broaden your watchlist with a few focused screens that surface different kinds of opportunities.
Use these tools now so you do not miss timely setups that fit your own risk, income, and quality preferences across the market.
- Target potential mispricing by scanning a curated group of businesses trading below estimated worth through the 32 high quality undervalued stocks.
- Explore income-focused ideas by zeroing in on companies that appear to offer robust yields and balance sheet strength using the 8 dividend fortresses.
- Filter for steadier rides by focusing on businesses with lower risk profiles and resilient fundamentals inside the 30 resilient stocks with low risk scores.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com