


How Investors Are Reacting To Travelers (TRV) Underwriting Discipline Holds Up
- Travelers Companies has recently drawn attention as its strong capital position, diversified insurance portfolio, and focus on underwriting discipline supported earnings amid softer commercial pricing.
- The key angle is how Travelers Companies is relying on efficiency gains, fixed cost leverage, and reserving discipline to sustain margins even as sector pricing momentum cools.
- We will now explore how Travelers Companies' prudent underwriting track record may reshape the investment narrative investors have been using up to now.
Scan beyond Travelers Companies to compare its disciplined underwriting profile with other insurers by reviewing 30 resilient stocks with low risk scores featuring resilient balance sheets and measured risk scores.
Travelers Companies Investment Narrative Recap
For an investor to stay with Travelers Companies, the core belief is that disciplined underwriting, technology spend and fixed cost leverage can keep underwriting results resilient even as commercial pricing cools and sector margins feel more mature. The immediate swing factor is whether pricing and retention in key lines still offset elevated catastrophe activity and casualty severity.
The biggest operational risk is that weather losses or long tail casualty trends exceed what the reinsurance program and reserves comfortably absorb, which would pressure the combined ratio and earnings. Softer commercial rates and moderated renewal changes in personal lines add some near term uncertainty, but do not radically alter the thesis on their own.
The most relevant recent development is the pattern of higher pre tax profits supported by efficiency gains and better fixed cost leverage while commercial pricing softens. That mix shows Travelers Companies placing greater emphasis on execution, underwriting discipline and its US$1.5b plus technology and AI budget rather than relying solely on price increases to support margins.
For you, the operational question is whether that toolkit can continue to offset headwinds such as catastrophe exposure, casualty litigation trends and moderating rate momentum. If execution on underwriting, reserving and cost control remains tight, those same drivers could remain the key catalysts, while any slip in claims trends or pricing power would quickly test the thesis.
Travelers Companies' current analyst storyline points to US$47.3b in revenue and US$5.2b in earnings by 2029. Revenues are assumed to decline 1.1% per year, and earnings are expected to fall by US$3.0b from US$8.2b today to reach that 2029 consensus level.
Uncover why Travelers Companies' fair value is essentially consistent with its current price.
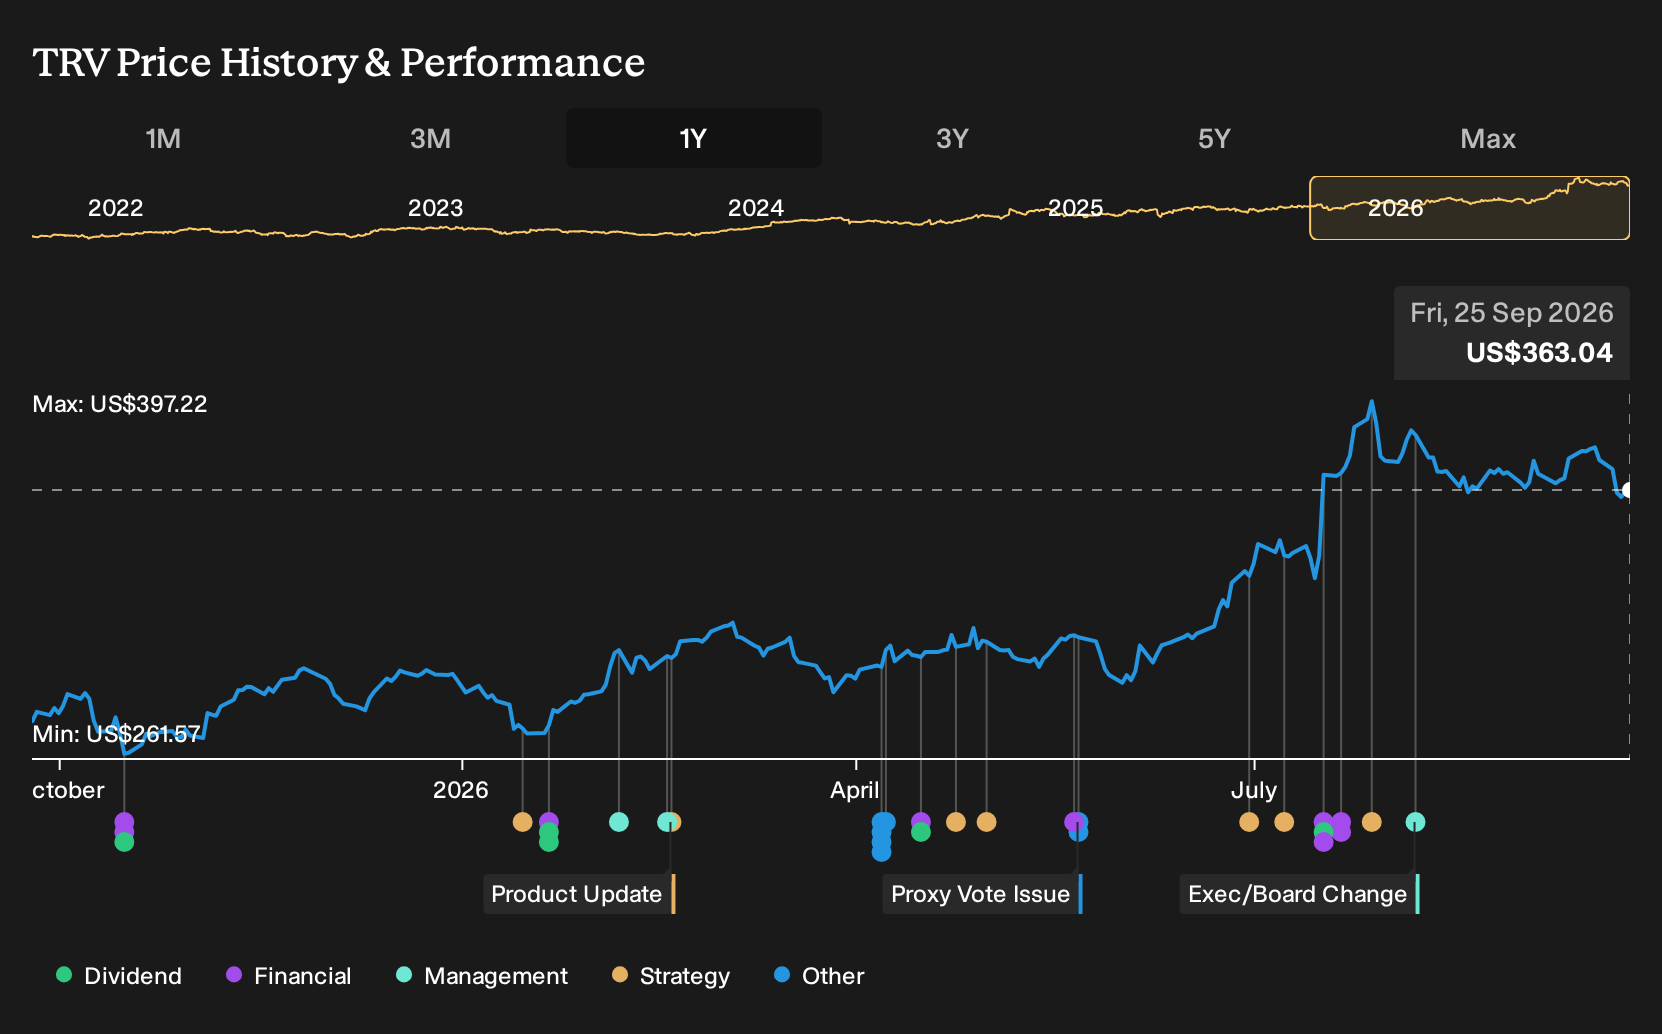
Exploring Other Perspectives
Some higher ranked analysts frame the key swing factor differently for Travelers Companies. They focus on whether record net written premiums and tools like Travis can support earnings closer to US$5.7b by 2029, compared with the US$5.2b consensus. Those views are more optimistic, and the latest news could easily shift either narrative.
Explore 2 other Travelers Companies fair value estimates, including one that suggests as much as 113% upside from the current price.
Decide For Yourself
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Travelers Companies research is our analysis highlighting 2 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for Travelers Companies. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Travelers Companies' overall financial health at a glance.
Looking for more investment ideas beyond Travelers Companies?
Once you have a view on Travelers Companies, it can help to widen the lens and see how its profile compares with other stocks that fit different risk and income goals using the Simply Wall St Screener.
- For investors who care most about capital strength and measured volatility, review a curated 30 resilient stocks with low risk scores that aim to hold up better when conditions get choppy.
- If reliable income is the priority, scan through 8 dividend fortresses that pair higher yields with balance sheets that are built to sustain regular payouts.
- When the focus is long term value, sift through 16 high quality undiscovered gems that combine solid fundamentals with less market attention.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com