


PBF Energy (PBF) Stock Looks Undervalued As Its Five Year Run Nears 7x
PBF Energy has been on a remarkable multi year run, which naturally puts the current share price under the spotlight. With the market now focusing on what the business can earn, the live question is whether that recent performance is fully backed by its earnings power.
- Over the past 5 years, the stock has delivered a very large total return, so any fresh money going in today is effectively betting that the earnings story can keep carrying that weight.
- PBF Energy recently priced US$500 million of 0% exchangeable notes due 2032 to refinance higher coupon debt, which can reshape future interest costs and the cash flow available to equity holders.
- Your read on PBF Energy is one view; the desks covering it have another. See what analysts think PBF Energy's shares could be worth.
The issue now is whether the earnings that support PBF Energy can justify where the share price sits today.
If you are weighing whether PBF Energy’s 5 year return near 7x is fully underpinned by its earnings, it can help to compare that question across 32 high quality undervalued stocks
Is PBF Energy a Bargain on Earnings?
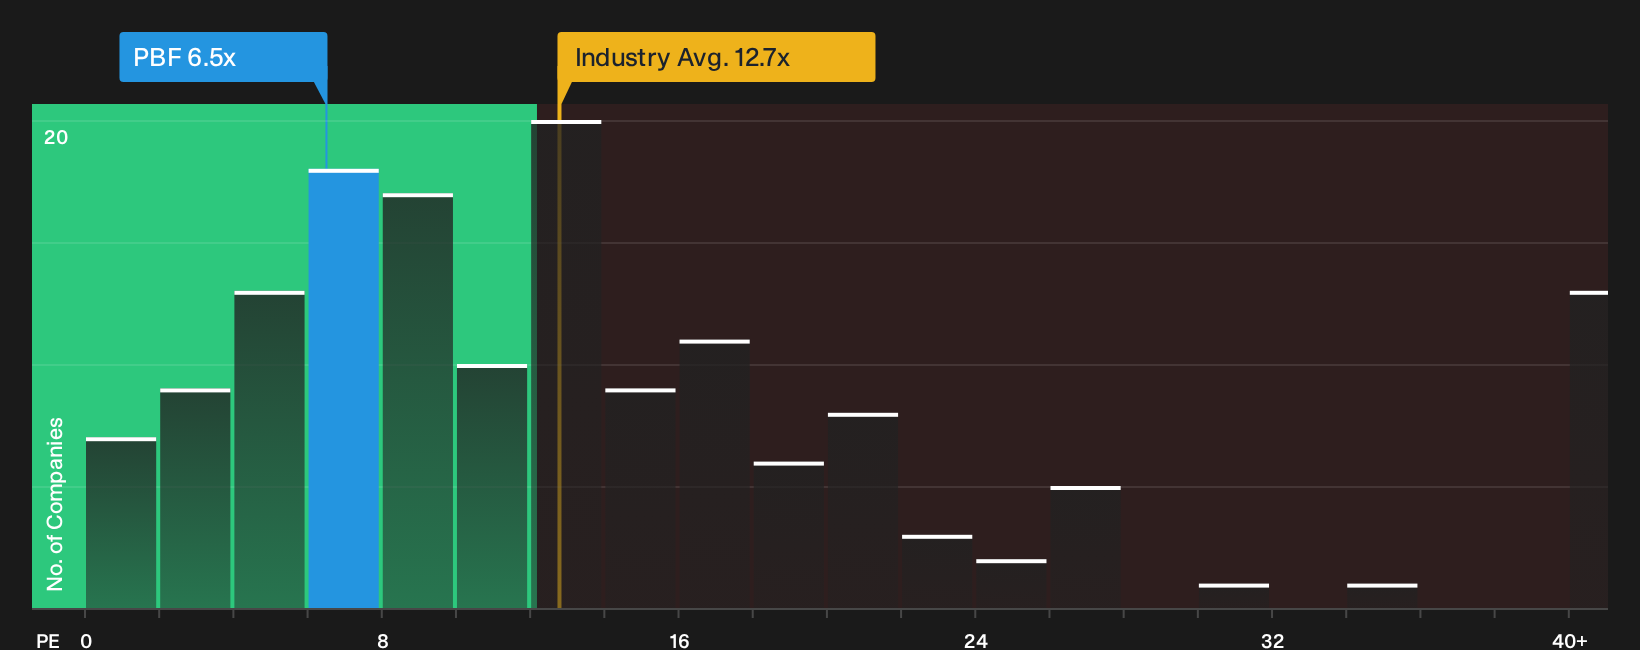
The P/E ratio is a straightforward way to see what the market is paying for each dollar of PBF Energy earnings. Right now the stock trades on roughly 6.5x earnings, which is well below the Oil and Gas sector average of about 12.7x and far under a peer group closer to 30.0x.
A tailored fair P/E multiple that adjusts for PBF Energy’s size, margins and risk profile sits above where the shares currently trade. As a result, the current 6.5x screens as undervalued against that yardstick. Because the recent US$500 million 0% exchangeable notes are aimed at refinancing higher coupon debt, the market is effectively pricing that balance sheet move in while still valuing the earnings stream at a clear discount on this framework. Explore the numbers behind PBF Energy's P/E valuation.
The PBF Energy Narrative: What Would Justify Today's Price?
Simply Wall St Narratives for PBF Energy pick up where the P/E puzzle leaves off. They explain which potential paths for PBF Energy's future earnings, margins and growth would make the current share price appear too low or too high. Each narrative ties a specific fair value to one possible mix of catalysts and risks, allowing you to track over time which version of events is actually unfolding on the Community page.
On PBF Energy, the community split is really about whether the story still has more to give or is already largely reflected in the price.
Bull case: 12% undervalued
"PBF is uniquely positioned to benefit from sustained global demand growth and inadequate capacity additions, as capacity rationalizations and refinery closures accelerate in both North America and Europe..."
Discover why this Narrative puts PBF Energy at 12% undervalued.
Bear case: roughly fairly valued
"Persistent operational and regulatory risks at key refineries, especially Martinez, expose PBF to ongoing revenue volatility and higher repair and maintenance capex..."
Explore why this Narrative puts PBF Energy at roughly fairly valued.
The share price is only one piece of the PBF Energy puzzle
Market multiples tell you what investors pay for today, while the next layer of work is checking how professional analysts see earnings and cash flows evolving a few years from now. Explore where analysts expect PBF Energy to be in a few years.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com