


One Day Left Until Dear Life Co.,Ltd. (TSE:3245) Trades Ex-Dividend
Dear Life Co.,Ltd. (TSE:3245) stock is about to trade ex-dividend in couple of days. The ex-dividend date is usually set to be two business days before the record date, which is the cut-off date on which you must be present on the company's books as a shareholder in order to receive the dividend. The ex-dividend date is important as the process of settlement involves at least two full business days. So if you miss that date, you would not show up on the company's books on the record date. This means that investors who purchase Dear LifeLtd's shares on or after the 29th of September will not receive the dividend, which will be paid on the 3rd of December.
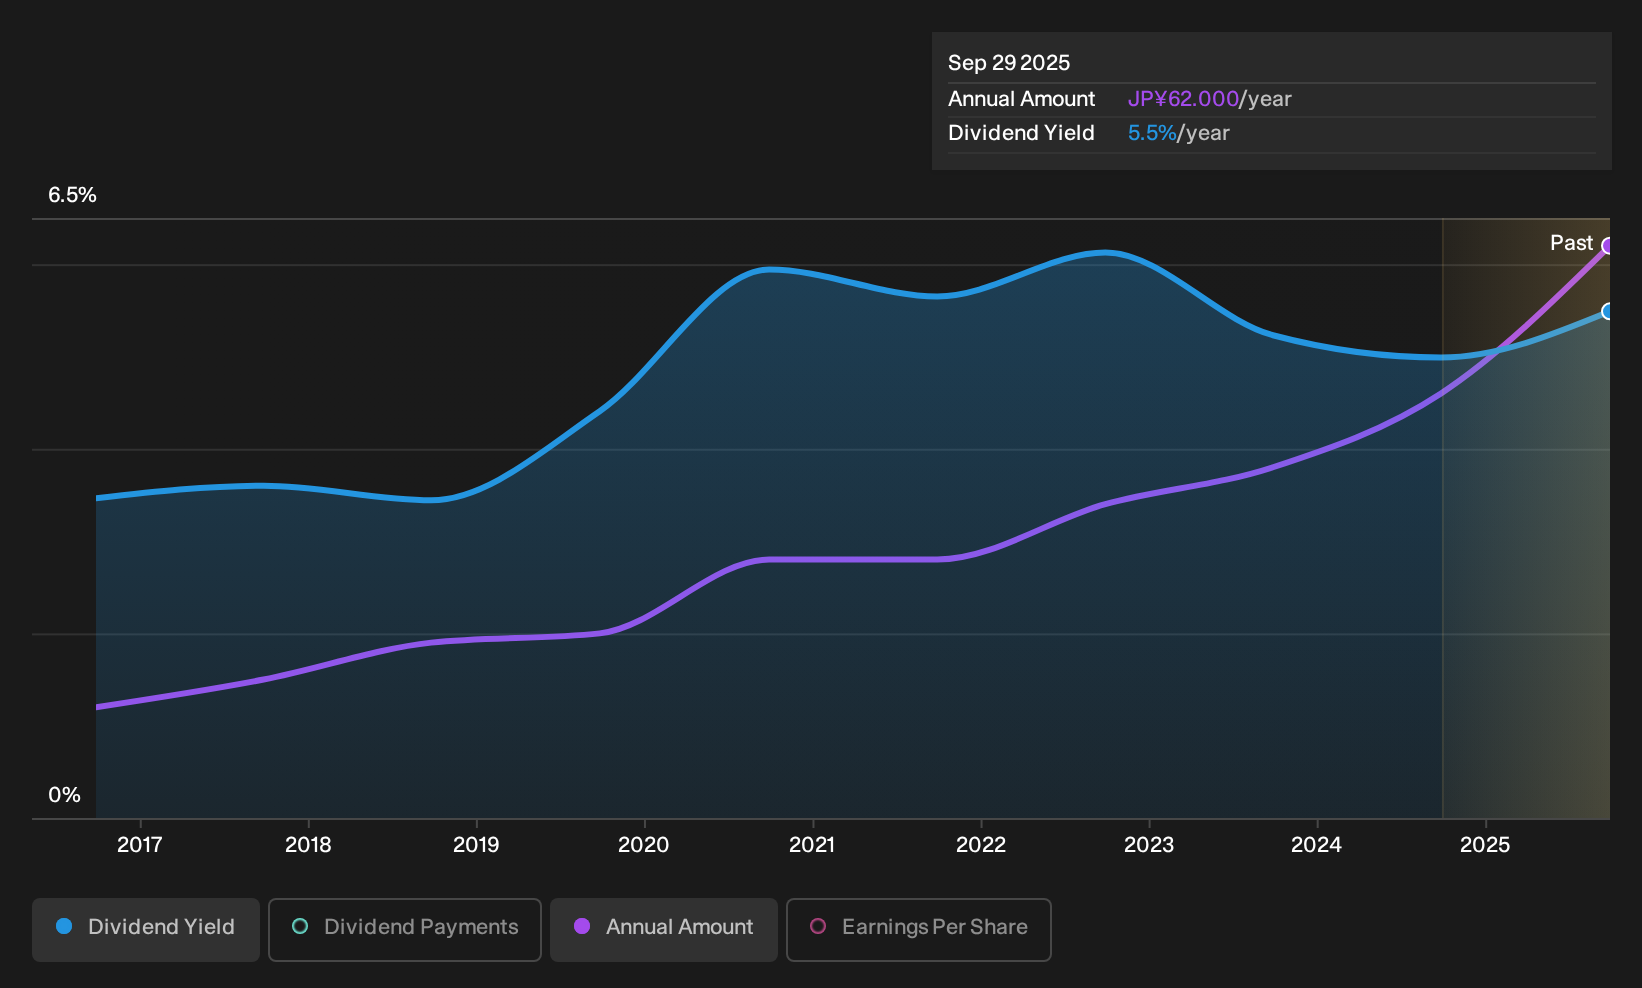
The company's next dividend payment will be JP¥64.00 per share. Last year, in total, the company distributed JP¥64.00 to shareholders. Calculating the last year's worth of payments shows that Dear LifeLtd has a trailing yield of 6.3% on the current share price of JP¥1021.00. Dividends are a major contributor to investment returns for long term holders, but only if the dividend continues to be paid. So we need to check whether the dividend payments are covered, and if earnings are growing.
Dividends are typically paid out of company income, so if a company pays out more than it earned, its dividend is usually at a higher risk of being cut. Dear LifeLtd is paying out an acceptable 56% of its profit, a common payout level among most companies. Yet cash flow is typically more important than profit for assessing dividend sustainability, so we should always check if the company generated enough cash to afford its dividend. Over the past year it paid out 114% of its free cash flow as dividends, which is uncomfortably high. We're curious about why the company paid out more cash than it generated last year, since this can be one of the early signs that a dividend may be unsustainable.
While Dear LifeLtd's dividends were covered by the company's reported profits, cash is somewhat more important, so it's not great to see that the company didn't generate enough cash to pay its dividend. Were this to happen repeatedly, this would be a risk to Dear LifeLtd's ability to maintain its dividend.
View our latest analysis for Dear LifeLtd
Click here to see how much of its profit Dear LifeLtd paid out over the last 12 months.
Have Earnings And Dividends Been Growing?
Businesses with strong growth prospects usually make the best dividend payers, because it's easier to grow dividends when earnings per share are improving. If business enters a downturn and the dividend is cut, the company could see its value fall precipitously. Fortunately for readers, Dear LifeLtd's earnings per share have been growing at 16% a year for the past five years. Earnings have been growing at a decent rate, but we're concerned dividend payments consumed most of the company's cash flow over the past year.
We'd also point out that Dear LifeLtd issued a meaningful number of new shares in the past year. Trying to grow the dividend while issuing large amounts of new shares reminds us of the ancient Greek tale of Sisyphus - perpetually pushing a boulder uphill.
The main way most investors will assess a company's dividend prospects is by checking the historical rate of dividend growth. In the past 10 years, Dear LifeLtd has increased its dividend at approximately 18% a year on average. Both per-share earnings and dividends have both been growing rapidly in recent times, which is great to see.
To Sum It Up
Has Dear LifeLtd got what it takes to maintain its dividend payments? Earnings per share growth is a positive, and the company's payout ratio looks normal. However, we note Dear LifeLtd paid out a much higher percentage of its free cash flow, which makes us uncomfortable. All things considered, we are not particularly enthused about Dear LifeLtd from a dividend perspective.
However if you're still interested in Dear LifeLtd as a potential investment, you should definitely consider some of the risks involved with Dear LifeLtd. To help with this, we've discovered 2 warning signs for Dear LifeLtd that you should be aware of before investing in their shares.
A common investing mistake is buying the first interesting stock you see. Here you can find a full list of high-yield dividend stocks.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team (at) simplywallst.com.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.