


FireFly Metals (ASX:FFM) Shares Look Fully Priced On Book Value
FireFly Metals has delivered a very large 3 year share price gain, yet the recent pullback now puts the spotlight on whether that journey is still backed by its book value. With fresh technical work on the Green Bay project confirming a stable net present value, the question is how much of that asset base and future potential is already embedded in today's A$1.72 share price.
- FireFly Metals has returned about 267.0% over the past 3 years. This raises a clear question about how closely the current valuation still tracks the strength of its balance sheet.
- The new independent technical report on the Green Bay Copper Gold Project confirms a stable project net present value and only minor capital expenditure revisions. This can influence how investors think about future funding needs and the backing that project provides to the stock's stated equity value.
- Your read on FireFly Metals is one view; the desks covering it have another. See what analysts think FireFly Metals's shares could be worth.
The issue now is whether FireFly Metals' recent share price level is well supported by its book value when compared with the industry average.
To see how FireFly Metals compares with other book value focused opportunities, it can help to review it alongside 5 high quality undervalued stocks.
Does FireFly Metals Look Pricey on Book Value?
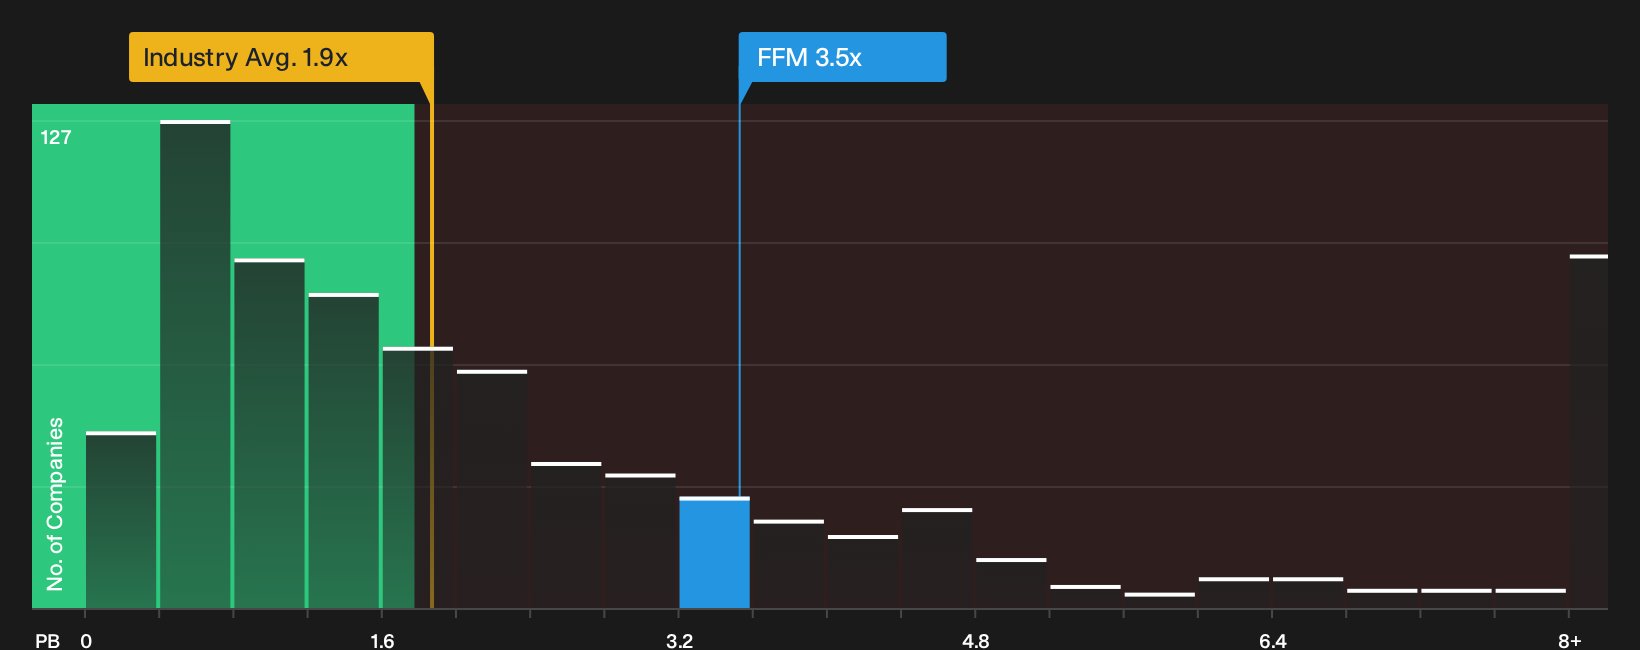
P/B is a useful yardstick for FireFly Metals because the story is still centred on assets and project potential rather than mature earnings. On this measure, the stock trades on a P/B of about 3.5x, compared with an industry average around 1.9x and a peer group level near 2.6x. That gap points to investors paying a premium relative to both the broader Metals and Mining group and closer-listed comparables. In other words, the market is already assigning extra value to the underlying assets and future projects.
Because the latest Green Bay technical report confirmed a stable project net present value, this richer 3.5x book multiple suggests that a fair amount of optimism around that asset is already reflected in the share price when stacked against the sector. For anyone weighing FireFly Metals at current levels, the key question is whether the quality, scale and funding profile of its projects justify paying above the book-based multiples that apply to many other miners. Explore the numbers behind FireFly Metals's P/B valuation.
The FireFly Metals Narrative: What Would Justify Today's Price?
Simply Wall St Narratives pick up where the P/B puzzle leaves off for FireFly Metals by spelling out which paths for future growth, margins and earnings would need to play out for the share price to sit materially above or below today’s level, and they live on the stock’s Community page. Each one frames FireFly Metals' fair value as a thesis you can watch over time, rather than as a single static number.
A written, number driven view on FireFly Metals helps pin down what investors think the confirmed Green Bay project NPV and updated resource base are worth across different scenarios, and which assumptions actually carry the current P/B premium. It then gives you a concrete roadmap to revisit as new drilling results, funding decisions and development milestones either support or challenge those expectations over time.
Share your own Narrative for FireFly Metals and set out the assumptions behind your valuation.
FireFly Metals' valuation still leaves one crucial angle unresolved
Numbers only tell part of the story for FireFly Metals. The people setting priorities and the way their incentives are structured can heavily shape how that story plays out for shareholders. See who runs FireFly Metals and how they are paid.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com