


Is Analyst Upgrade Altering The Investment Case For Nebius Stock (NBIS)?
- Nebius Group was recently added to the FTSE All-World Index and reported strong AI cloud infrastructure revenue, supported by customer prepayments and a multi year contract with Meta.
- The business is lifting prices on certain Nvidia GPU instances while scaling capacity. This highlights both intense demand and rising cost and utilization pressure on its AI platform.
- We will now see how Nebius Group's investment narrative could be affected by rapid AI cloud demand and index inclusion together.
Compare Nebius Group's AI cloud story with other potential breakout infrastructure plays by screening for 85 AI infrastructure stocks that sit at the crossroads of compute demand and capacity build outs.
Nebius Group Investment Narrative Recap
To own Nebius Group, you need to be comfortable with an AI infrastructure company that is still in a heavy build out phase, with most revenue tied to Nebius AI Cloud. The big belief is that demand for large scale GPU capacity and multiyear contracts can justify high capital spending and relatively thin 3.1% net margins today.
The key short term catalyst is execution on capacity ramp and monetisation of that Meta contract while managing construction costs and power utilisation. Index inclusion and recent stock moves do not change that core operational test. The biggest near term risk remains that utilization or pricing fails to cover rising build and energy costs.
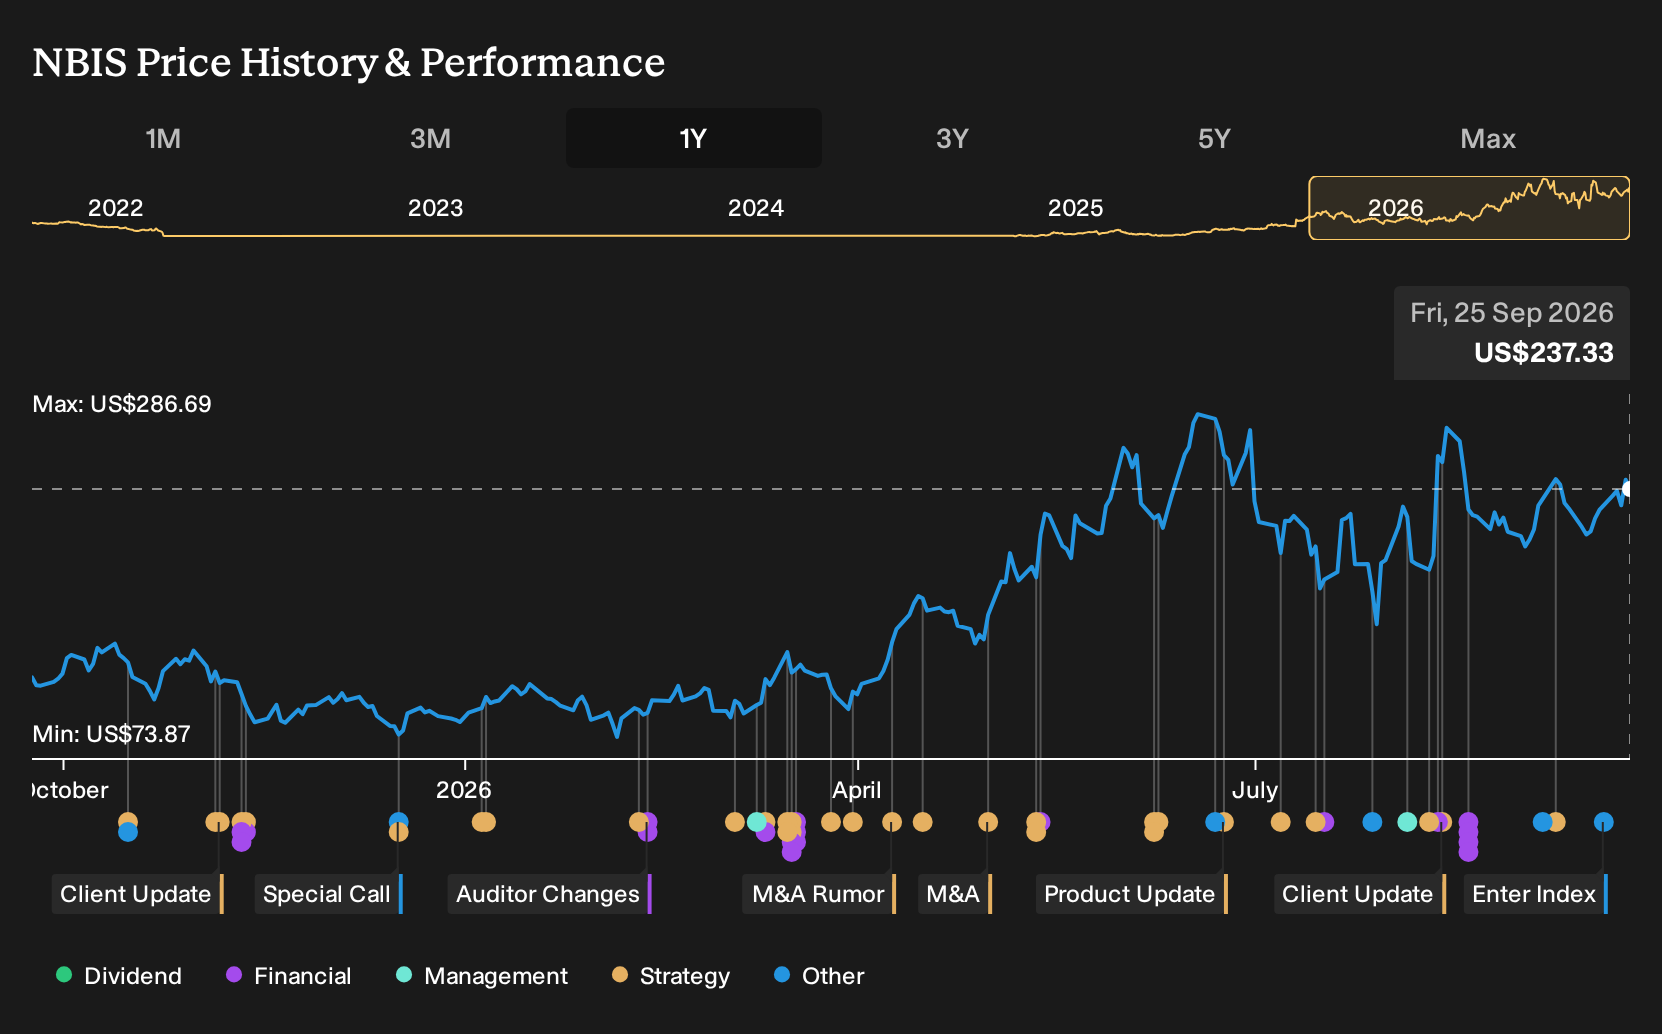
The FTSE All World Index addition is the announcement that most directly interacts with this story. Inclusion can increase visibility for Nebius Group with global allocators and passive flows, which often brings closer scrutiny of capital intensity, pricing decisions on Nvidia GPU instances, and the consistency of reported AI cloud revenue.
At the same time, Michael Burry’s expanded short against Nebius and peers shows how crowded the AI infrastructure trade has become as expectations rise. For investors watching catalysts, that mix of higher index driven exposure and visible scepticism sharpens the focus on each quarterly update around utilization, power efficiency, and progress toward the US$7b to US$9b revenue run rate.
Nebius Group's narrative projects revenues of US$30.3b and earnings of US$2.4b by 2029. That path assumes revenue growth of 181.9% per year and an earnings increase of about US$2.36b from current earnings of US$42.4m.
Uncover why Nebius Group's fair value indicates a 32% potential upside to its current price and why that gap could narrow quickly.
Exploring Other Perspectives
One alternate angle on Nebius Group focuses less on index flows and more on bullish forecasts for raw AI capacity. The most optimistic analysts were already sketching out revenue of US$48.5b and earnings of US$1.1b by 2029, well before this FTSE All World inclusion. That is far more upbeat than consensus, and it may shift again as fresh data lands.
Explore 12 other Nebius Group fair value estimates, including one that suggests as much as 75% upside from the current price.
Reach Your Own Conclusion
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so trust your own analysis and judgment.
- A great starting point for your Nebius Group research is our analysis highlighting 1 key reward and 4 important warning signs that could impact your investment decision.
- See our latest analysis for Nebius Group. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easier to review Nebius Group's overall financial position at a glance.
Looking For More Investment Ideas Beyond Nebius Group?
If Nebius Group has sharpened your thinking about AI infrastructure, you can use that same lens to look for other opportunities across the market with the Simply Wall St Screener.
- For investors who care most about balance sheet strength and fundamental quality, start with a list of solid balance sheet and fundamentals (24 results) that may better match a preference for resilience over excitement.
- If resilience and lower downside risk are your priority, filter for 30 resilient stocks with low risk scores that aligns with a more defensive approach to building long term wealth.
- Those hunting for under followed opportunities can focus on 16 high quality undiscovered gems that combine fundamental quality with limited current attention.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com