


3 Indian Undervalued Stocks To Own In September 2026
US 10-year Treasury yields recently moved above 5%, which raises borrowing costs across sectors and makes cash today more valuable than cash promised far in the future. That shift pushes investors to look harder at Indian companies that already produce solid cash flows yet trade below fair value on discounted cash flow screens. This article highlights three such undervalued candidates and explains why their cash generation may appeal to patient buyers.
The three Indian stocks below are just a starting sample, because the full discounted cash flow screen surfaced four more companies with equally cash-rich stories that are not covered here.
If you want to go beyond this short list and actively identify, analyze, and focus on your own highest-conviction cash flow ideas, head straight to the Undervalued Stocks Based On Cash Flows screener.
WPIL (BSE:505872)
Overview: WPIL designs, manufactures, installs, and services engineered pumping systems for water, irrigation, municipal, and energy projects in India and overseas.
Operations: WPIL generates about ₹10.7b from pumps and accessories and ₹9.1b from project works, with revenue split between India and international markets.
Market Cap: ₹42.0b
WPIL fits this cash-flow-focused screener because its engineered pumps and long-term service work are closely tied to real-world water infrastructure buildouts, which can translate project pipelines into more visible future cash generation.
"Rising global focus on water infrastructure, including river linking, wastewater and municipal water projects, is feeding into WPIL's consolidated project and product order backlog of about ₹5,200 crores."
What really matters now is how one less obvious pressure shapes the profitability that underpins those cash flows investors are counting on.
That hidden pressure on profitability is exactly what the full narrative for WPIL unpacks, showing how current cash generation and future projects could be decoupling from headline risks.
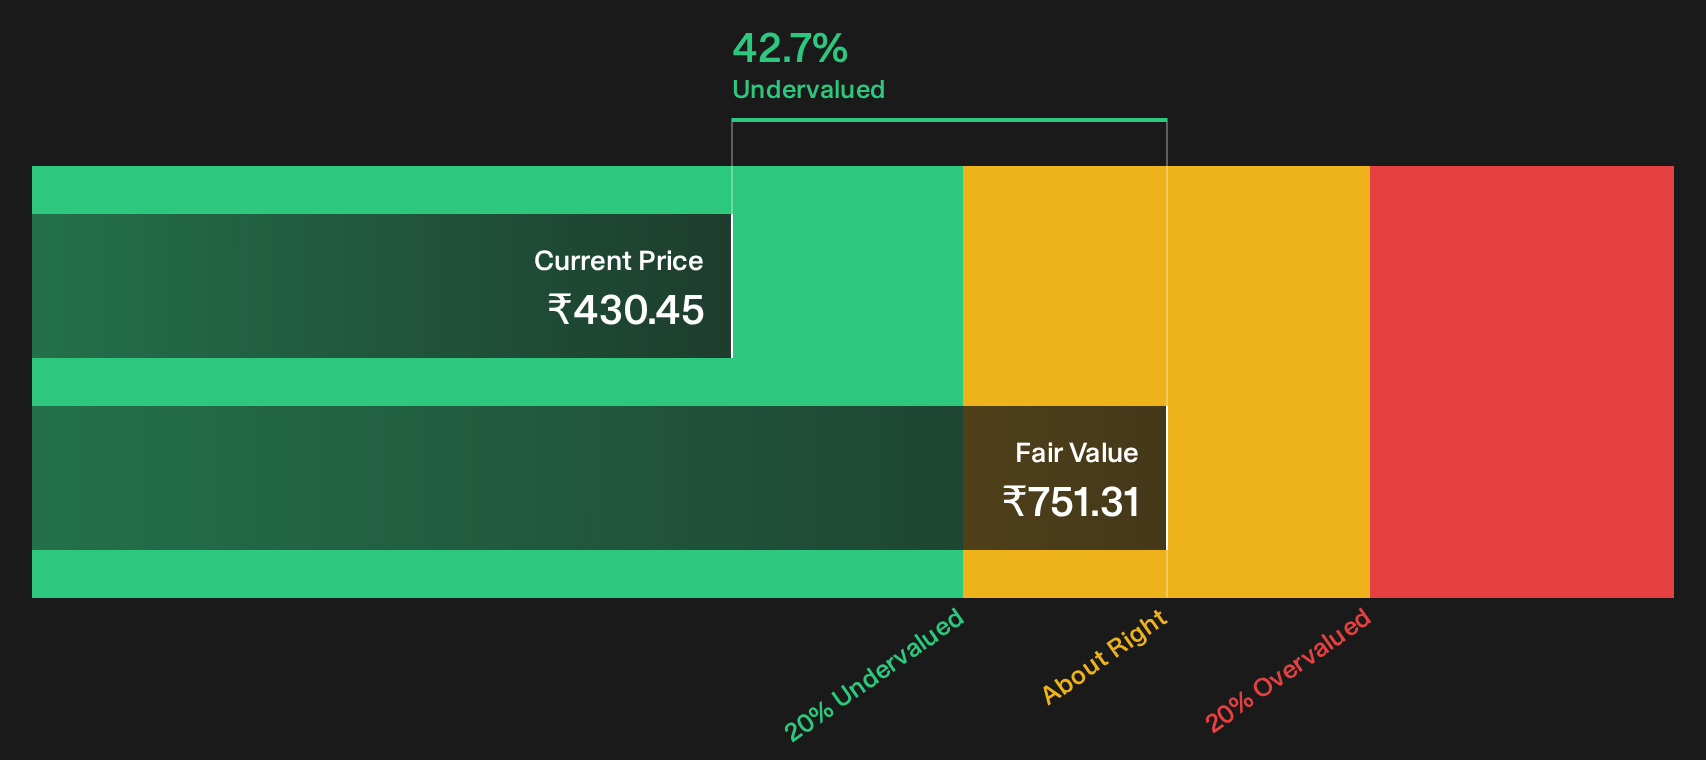
Flair Writing Industries (NSEI:FLAIR)
Overview: Flair Writing Industries manufactures and sells pens, creative stationery, and related writing products, giving it writing-instrument driven cash flows that fit this undervalued cash-flow screener.
Operations: Flair Writing Industries generates about ₹12.8b in revenue from its Writing Instruments & Other Allied(s) segment.
Market Cap: ₹25.0b
Flair Writing Industries earns its place in this cash-flow-focused screen because its core pen and refill franchise creates repeat, relatively predictable demand that a discounted cash flow model can directly value.
"Scaling of high growth, higher margin creative and steel bottle and houseware portfolios, which together already contribute about 30% of revenue versus 15% last year, is expected to structurally lift consolidated revenue growth above prior guidance and sustain EBITDA margins near or above 18%."
What happens if one quiet shift in how that higher-margin mix evolves ends up changing the earnings trajectory investors are currently pricing in?
If that mix shift is what decides where the upside really sits, full narrative for Flair Writing Industries shows whether Flair Writing Industries’ premium push is accelerating or quietly stalling.

TeamLease Services (NSEI:TEAMLEASE)
Overview: TeamLease Services runs large-scale temporary and contractual staffing, payroll, and HR services that generate recurring cash-flow-focused revenue across many industries.
Operations: TeamLease Services earns about ₹110.1b from General Staffing, ₹7.0b from Specialised Staffing, and ₹2.5b from Other HR Services.
Market Cap: ₹19.7b
TeamLease Services matters for this cash-flow screener because its volume-heavy staffing and payroll engine converts recurring HR contracts into steady, fee-based cash generation that a discounted cash flow model can directly weigh against the current share price.
"The rapid growth of apprenticeship adoption, accelerating government skilling initiatives, and TeamLease's unique partnerships with 22 universities position it as the clear national leader in work-integrated learning, paving the way for a new, high-growth, higher-margin revenue stream that is underappreciated in current earnings estimates."
What really decides how much of that underappreciated cash potential reaches shareholders is whether one quiet shift in capital allocation continues.
If that shift is what unlocks the real cash story, full narrative for TeamLease Services illustrates how capital allocation, apprenticeships, and staffing economics could be quietly compounding ahead of expectations.

Seeking Alternatives Beyond These Ideas?
Fresh opportunities move fast. Some gain breakout momentum while others drop off once the crowd catches on. Scan what is still under the radar for now and act now.
- Spot income workhorses with staying power by scanning the 162 dividend fortresses before yields compress and the strongest payout stories are fully priced in.
- Track the next wave of automation leaders by reviewing the curated 93 robotics and automation stocks while these operators are still flying below many investors' screens.
- Get ahead of the energy buildout by combing through the hand-picked 40 power grid technology and infrastructure stocks before grid upgrades and electrification stories get fully caught by the crowd.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com