


How Cancer Test Approval At Quest Diagnostics (DGX) Has Changed Its Investment Story
- Quest Diagnostics has seen strong momentum in advanced diagnostics, broader uptake across physician, hospital, and consumer-testing channels, and New York State approval to commercialize its molecular residual disease cancer test nationwide, supported by AI driven automation in its labs.
- The same push that is expanding Quest Diagnostics' cancer and kidney care offerings is also feeding growing consumer wellness demand. This deepens its mix of higher complexity, potentially higher value testing beyond traditional lab volumes.
- We will now look at how Quest Diagnostics' advanced diagnostics momentum could reshape the existing investment narrative around its growth drivers.
Scan how Quest Diagnostics' AI supported diagnostics push compares with other health focused plays by reviewing a curated list of 38 healthcare AI stocks in the same testing and treatment trend.
Quest Diagnostics Investment Narrative Recap
Owning Quest Diagnostics means believing that advanced diagnostics, AI supported automation, and consumer wellness testing can keep pulling more volume and higher complexity work through its labs. The recent 36.3% year to date share price gain reflects that story already. The key short term swing factor still sits in execution, keeping cost savings and service quality aligned with the rising mix of complex tests.
The biggest near term risk has not changed much. Reimbursement pressure from policies such as the Protecting Access to Medicare Act and broader healthcare coverage shifts could weigh on pricing and test volumes. If wage inflation or automation projects outpace efficiency gains, margins could come under pressure even with solid testing demand.
The New York State approval for Quest Diagnostics to commercialize its molecular residual disease cancer test nationwide is the clearest operational milestone tied to this news. It pushes the advanced oncology portfolio deeper into routine clinical use, across physicians and hospitals, at the same time AI tools are being rolled out to keep throughput and accuracy tight.
For catalysts, this fits neatly alongside broader activity in cardiometabolic, autoimmune, brain health, and consumer wellness diagnostics. Expanded MRD access adds another high complexity testing stream that can support tests per requisition, while still leaving the firm exposed to the familiar risks of reimbursement changes, slower than expected efficiency gains, or any stalling in health system partnerships and consumer channels.
Quest Diagnostics' current analyst narrative points to revenues of US$13.3b and earnings of US$1.5b by 2029, based on a projected 4.8% yearly revenue growth rate and an increase in earnings from US$1.1b today to that 2029 consensus level, which is an increase of roughly US$400m.
Uncover why Quest Diagnostics' fair value indicates a 5% potential upside to its current price, which could narrow quickly.
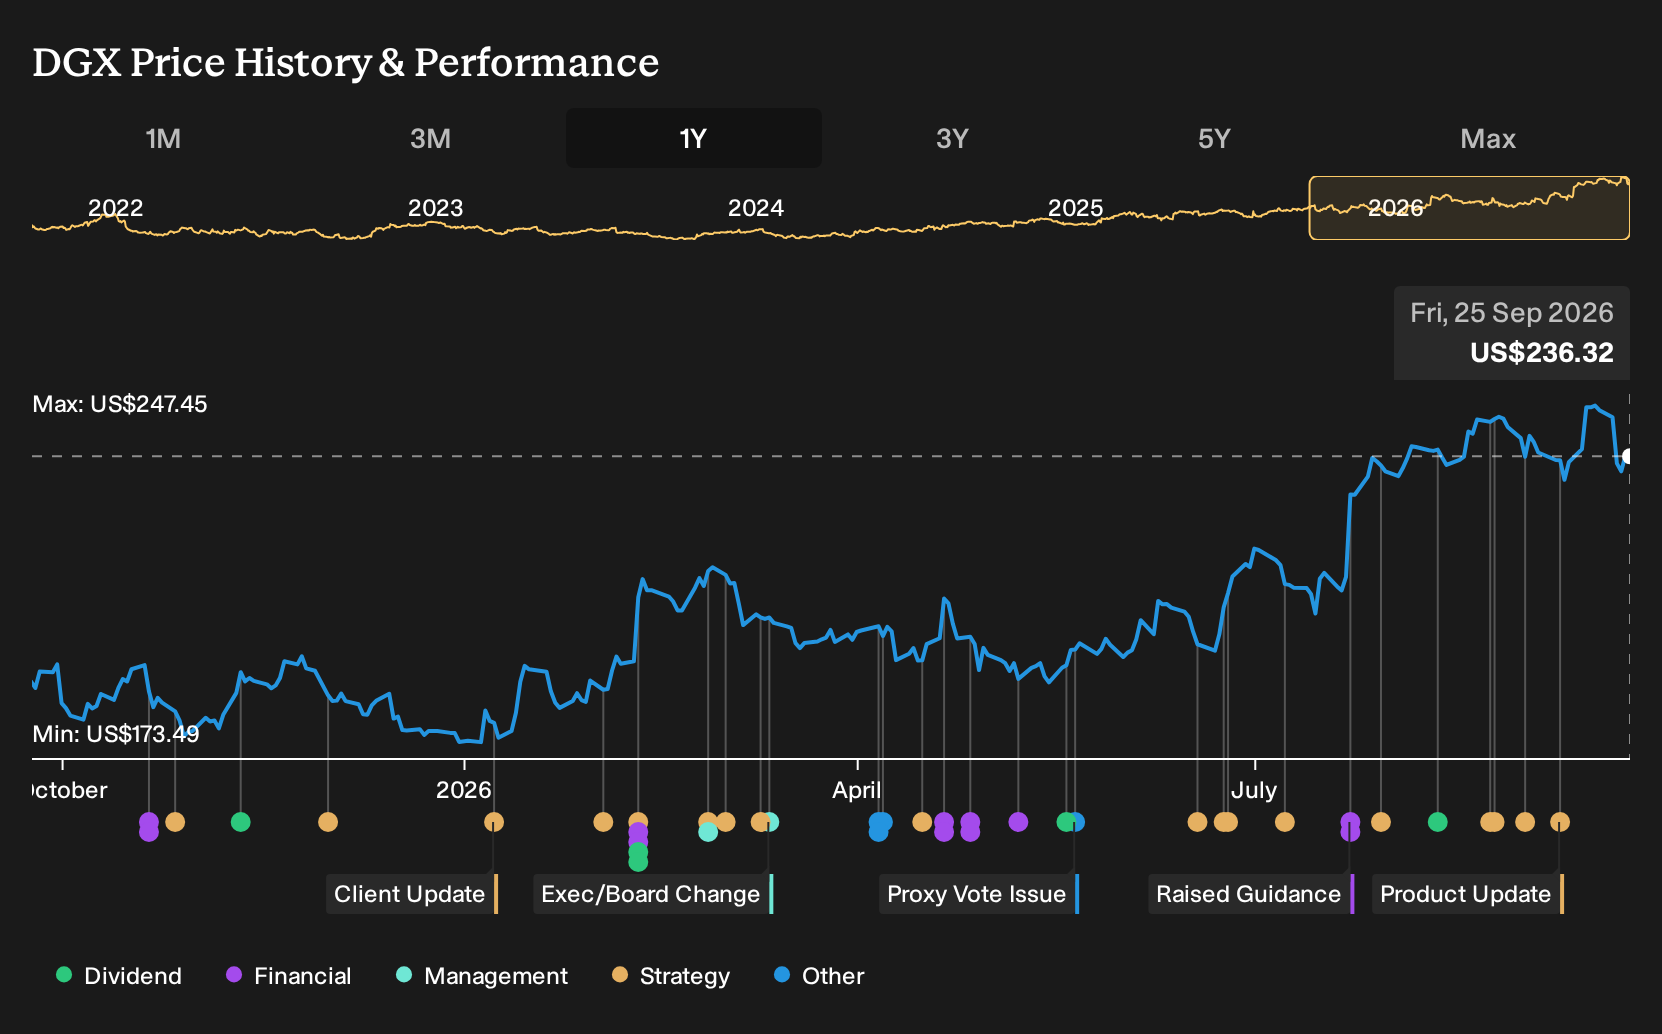
Exploring Other Perspectives
Two fair value estimates from the Simply Wall St Community bracket Quest Diagnostics between about US$247 and US$348 per share, which is a wide span for just a pair of views. Those private investors have not yet factored in the recent diagnostics news, so reimbursement risk, cost inflation, and evolving wellness demand could pull opinions even further apart. You should expect that views differ and use this as a prompt to explore several alternative angles on the stock.
Explore another Quest Diagnostics fair value estimate, including one that suggests as much as 47% upside from the current price.
Form Your Own Verdict
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your Quest Diagnostics research is our analysis highlighting 3 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Quest Diagnostics. The report includes a comprehensive fundamental analysis summarized in a single visual (the Snowflake), making it easy to evaluate Quest Diagnostics' overall financial health at a glance.
Looking For More Investment Ideas Beyond Quest Diagnostics?
If Quest Diagnostics has sharpened your thinking about healthcare and diagnostics, it can be useful to compare it with other opportunities that line up with your risk tolerance, income needs, and time horizon. The Simply Wall St Screener lets you filter for very different types of stocks, from steady compounders to higher risk contrarian ideas.
- If capital protection is front of mind, start with a basket of companies that score well on resilience and balance sheet strength through the 30 resilient stocks with low risk scores.
- For investors hunting for quality at a reasonable entry point, scan a curated set of potentially mispriced businesses with solid fundamentals via the 32 high quality undervalued stocks.
- Income focused portfolios can benefit from another lens altogether, so review a targeted universe of higher yielding payers by checking the 8 dividend fortresses.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com