


How Device Adoption Growth Will Impact AtriCure (ATRC) Stock
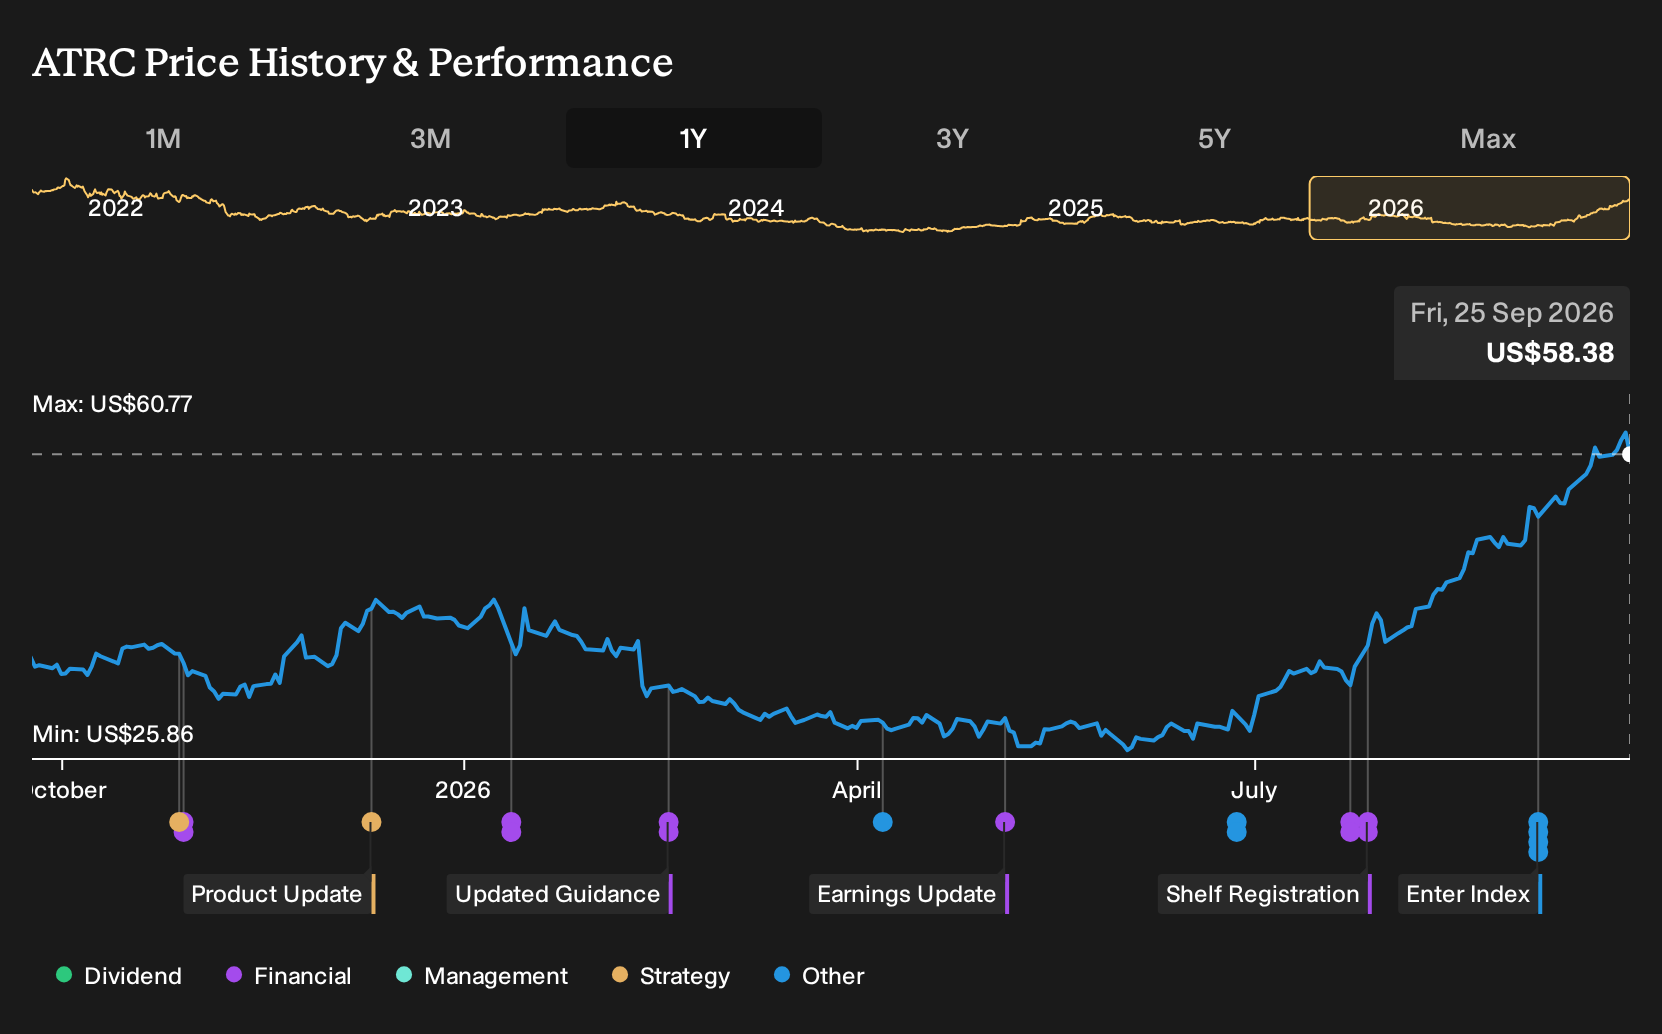
- AtriCure has drawn attention after its shares recently closed at US$60.77, with revenue supported by accelerating uptake of its minimally invasive cardiac surgical devices and continued push into international markets.
- The spotlight now falls on how much investors are willing to pay for AtriCure's sales base as its cardiac device portfolio gains broader adoption, while the share price trades above several fair value models.
- We will now look at how AtriCure's accelerating device adoption and global expansion could reshape the broader investment narrative around the business.
Scan how AtriCure's move has reset expectations for high-growth medtech, and compare it with a curated list of peers using the 38 healthcare AI stocks.
AtriCure Investment Narrative Recap
To back AtriCure at today’s price, you need to believe its cardiac devices can keep gaining share in procedure volumes and maintain healthy pricing, even as competitors push pulsed field ablation catheter offerings. In the short term, the catalyst is continued adoption of products like AtriClip and cryoSPHERE, plus steady international momentum. The recent run in the share price does not change that operational focus.
The biggest risk right now is pressure on the minimally invasive ablation franchise if PFA adoption accelerates further in the U.S. and abroad. That could weigh on revenue mix and margins just as AtriCure is trying to build on its move into profitability and extract more operating leverage from SG&A and R&D.
Given the lack of fresh operational announcements tied directly to this latest move in AtriCure’s stock, the most relevant backdrop is still its push in clinical evidence, particularly trials like LeAAPS and BoxX NoAF. Those studies address whether the device portfolio can support a larger addressable market over time.
Progress on enrollment and early activation in those trials matters because it underpins procedure volumes, reimbursement support and surgeon confidence, which are all core to the current valuation debate. Any delays, weaker than expected data or reimbursement setbacks would run counter to one of the key catalysts investors are watching while the share price trades above several fair value models.
AtriCure's current analyst narrative points to US$807.4 million in revenue and US$36.7 million in earnings by 2029, built on an assumed 12.3% yearly revenue growth rate and an increase in earnings of about US$26.1 million from US$10.6 million today.
Uncover why AtriCure's fair value signals an 11% potential downside to its current price, a premium that may not hold.
Exploring Other Perspectives
For a very different angle on AtriCure, some of the most optimistic analysts focus on clinical trial momentum as the real swing factor. They were modeling revenue of about US$824.7 million and earnings near US$62.2 million by 2029, which is far above consensus. The latest share price move may prompt these narratives to be revisited.
Explore another AtriCure fair value estimate, including one estimate suggesting it could be worth as much as $51.67.
Form Your Own Verdict
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your AtriCure research is our analysis highlighting 2 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for AtriCure. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate AtriCure's overall financial health at a glance.
Looking For More Investment Ideas Beyond AtriCure?
If AtriCure has sharpened your thinking about risk, reward and valuation, it can help to widen the lens and see how other businesses stack up on the same criteria using the Simply Wall St Screener.
- If you are hunting for quality at a discount, compare AtriCure with a broader set of potential bargains through 32 high quality undervalued stocks.
- If resilience matters most to you, focus on companies that pair sturdy finances with measured risk profiles using the 30 resilient stocks with low risk scores.
- If balance sheet strength is your first filter, start with a list of solid balance sheet and fundamentals (24 results) to see which businesses keep financial risk in check.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com