


True North Reset Might Change The Case For Investing In Canadian Tire Stock (TSX:CTC.A)
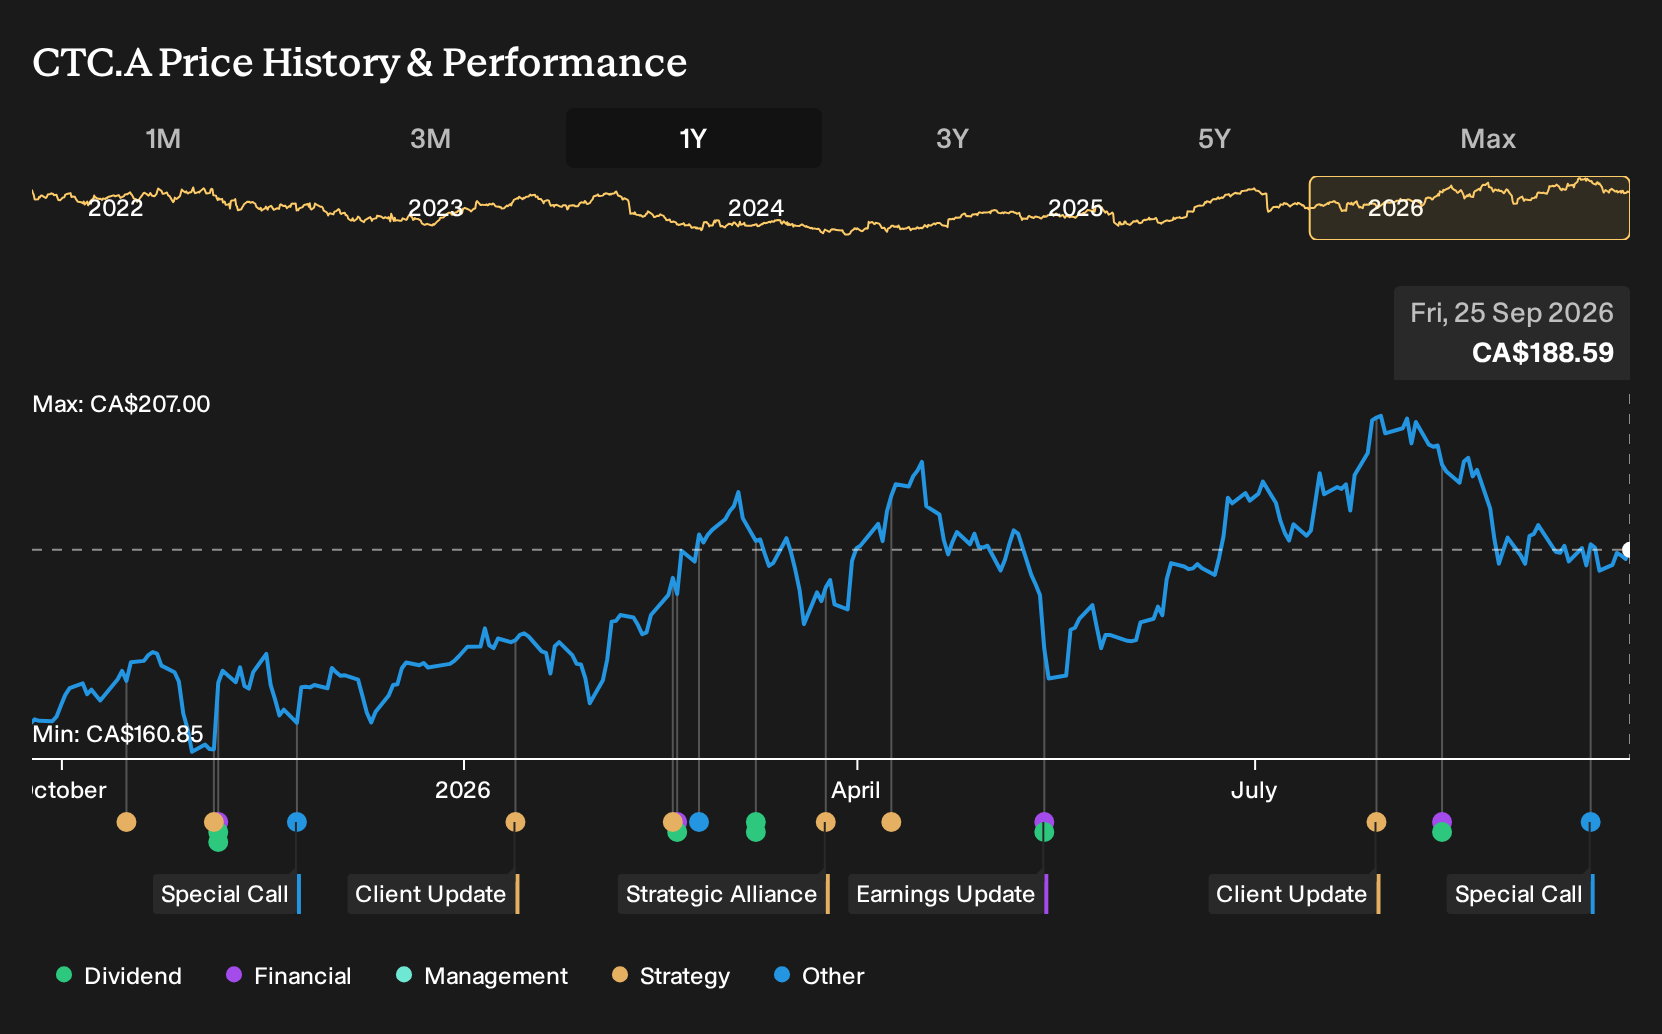
- Canadian Tire Corporation has been rolling out its four year True North program, including the sale of Helly Hansen, purchase of Hudson's Bay Company brand assets, AI tools in retail operations, and new Triangle loyalty partnerships with Tim Hortons.
- The combination of portfolio reshaping and heavier use of data and AI suggests Canadian Tire Corporation is trying to reposition a century old retailer for a more digital, partnership driven model at a time when consumer spending remains cautious.
- We will now look at how Canadian Tire's True North digital push and portfolio reshaping may influence the wider investment narrative.
Scan how Canadian Tire Corporation's True North reset compares with other retailers that are pushing into data, loyalty, and AI by reviewing our hand picked 87 AI infrastructure stocks.
Canadian Tire Corporation Investment Narrative Recap
For an investor to stay with Canadian Tire Corporation, the core belief is that the True North reset and the broader digital shift can support a more efficient, data led retailer without eroding profitability. The near term catalyst still sits in how quickly these AI tools, store refreshes and loyalty upgrades show up in earnings, given earlier margin pressure and slower forecast revenue growth.
The biggest operational risk remains execution under a heavier investment load and with debt that is not well covered by operating cash flow. The recent fireside chat and True North updates do not radically change that risk reward balance. The story still hinges on disciplined capital use and tight cost control.
The most relevant recent development is the push to embed AI across Canadian Tire Corporation’s retail and supply chain operations, tied to the wider True North program. That push runs alongside work on omnichannel services such as same day delivery and one click checkout, plus ongoing store refreshes across the retail network.
For catalysts, the key question is whether these tools and upgrades lift productivity and inventory turns enough to offset higher wages, utilities and technology spend. If execution stalls, investors face the risk of prolonged margin pressure while P/E support relies more heavily on the current dividend profile and perceived value rating.
Canadian Tire Corporation is modeled to reach CA$17.5b in revenue and CA$797.2m in earnings by 2029. That profile assumes 2.0% yearly revenue growth and an earnings increase of about CA$118m from CA$679.2m today.
Uncover how Canadian Tire Corporation's fair value indicates an 8% potential upside to its current price that could narrow quickly if sentiment improves.
Exploring Other Perspectives
The Simply Wall St Community only supplies two fair value views for Canadian Tire Corporation so far, with estimates between CA$158.19 and CA$204.60 per share. That spread reflects how widely opinions can differ. These investors publish numbers that do not yet factor in the fireside chat, True North progress, or any future shifts in consumer demand. Readers can use these differing estimates, along with the risks around higher fixed costs and changing shopping habits, to test their own expectations and compare several alternative viewpoints on Canadian Tire Corporation.
Explore another Canadian Tire Corporation fair value estimate, including one that suggests as much as 8% upside from the current price.
Form Your Own Verdict
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Canadian Tire Corporation research is our analysis highlighting 4 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Canadian Tire Corporation. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Canadian Tire Corporation's overall financial health at a glance.
Looking For More Investment Ideas Beyond Canadian Tire Corporation?
Once you have a view on Canadian Tire Corporation, it can help to broaden your watchlist with other businesses that match the balance of risk, income, or value you are looking for. The Simply Wall St Screener makes it straightforward to sort through the market using hard numbers instead of headlines.
- For investors who want potential upside without stretching on quality, start by reviewing a curated group of 5 high quality undervalued stocks that combine fundamentals with pricing that may appeal to value focused portfolios.
- If your priority is resilience and capital preservation, filter the market for 8 resilient stocks with low risk scores that score well on stability metrics and business durability.
- Income focused readers who care about reliable cash distributions can zero in on 1 dividend fortresses that currently offer yields of 5% or more.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com