


Vita Life Sciences And 2 Other Australian Dividend Stocks
Central banks are tightening policy to fight inflation, and government bond yields are climbing again, which puts reliable income back in the spotlight for Australian dividend stocks. When cash and bonds feel volatile, investors often look harder at companies with long records of paying and lifting dividends. This article walks through three high yield dividend veterans from our screener to help you research potential 5%+ income ideas.
The three stocks highlighted below are just a sample from the broader Dividend Aristocrats universe, and the full screen surfaced 0 more companies with equally compelling income stories that are not covered here.
If you want to identify and analyze more 5%+ dividend candidates with consistent payout records, head straight to the Dividend Aristocrats screener.
Vita Life Sciences (ASX:VLS)
Vita Life Sciences is a consumer healthcare group that formulates, packages and sells branded vitamins and supplements such as Herbs of Gold, VitaHealth and VitaScience. This gives it a direct link to stable, recurring cashflows that can support dividends. It generates about A$43 million from Australia and A$46 million from Malaysia and Singapore, and has a market cap of roughly A$149 million.
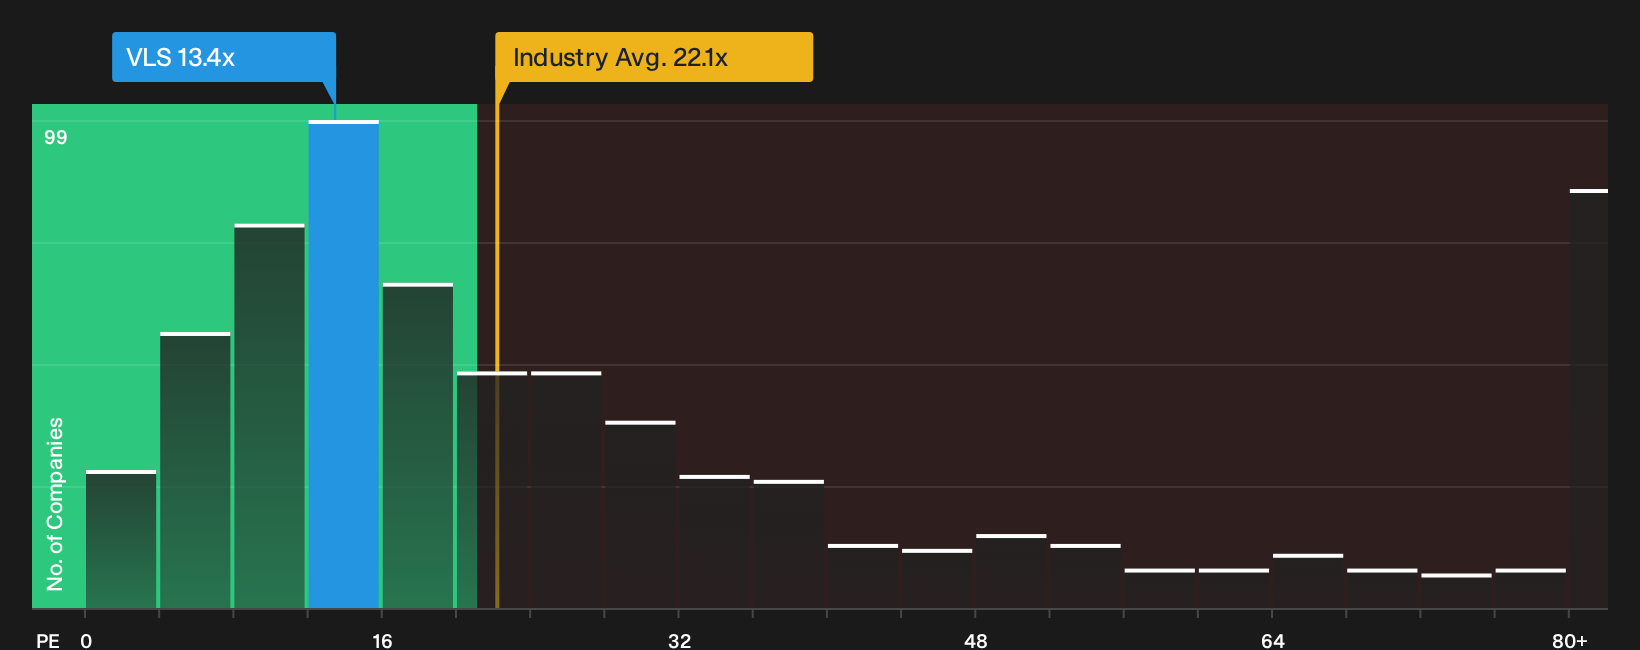
A 5.07% dividend yield, net margins of 11.6% and a P/E of 13.4x against far higher industry averages position Vita Life Sciences as a high income healthcare stock with value appeal. The main question for long term income investors is how that payout weathers one unseen pressure on the balance sheet.
To see how that balance sheet pressure really intersects with Vita Life Sciences’ income story, review the 3 key rewards and 1 important warning sign and identify what the headline yield might be masking.
Peet (ASX:PPC)
Peet is a Perth based residential developer that acquires, develops and sells housing estates across Australia, generating about A$305 million from development, A$95 million from funds management and A$33 million from joint arrangements, with a market cap near A$779 million.
Income investors may focus on Peet because its funds management arm earns recurring fees from long term land development funds, which can help support a high yield alongside project profits. Recent earnings and a fully franked dividend indicate income potential, depending on how one pending ownership shift reshapes that cash flow mix.
That ownership reshuffle is exactly why investors are turning to the 2 key rewards and 1 important warning sign to see whether Peet’s yield is quietly decoupling from its cash engine.

Sandfire Resources (ASX:SFR)
Sandfire Resources is a copper focused miner that earns its place in this Dividend Aristocrats group through cash flow from producing assets, which supports the potential for high dividends backed by real output rather than purely financial engineering.
Sandfire Resources develops and operates copper focused mines, with most revenue coming from the Motheo Copper Project at about US$745 million and MATSA operations at roughly US$910 million, plus smaller exploration income, and the business carries a market value near A$10.5b.
"Sandfire's ramp-up and optimization of the Motheo Copper Mine in Botswana is expected to deliver sustained step-changes in ore output and revenue."
The real test for Sandfire Resources is how that growing production base interacts with one pressure point that could reshape dividend comfort later on.
If that pressure point matters to you, read the full narrative for Sandfire Resources to see how Sandfire Resources’ expansion story could be accelerating or quietly masking future strain.

Seeking Alternatives Before The Crowd?
Fresh ideas move first. Breakout themes, quiet momentum and stocks still under the radar for now can get caught when attention floods in. Scan what others miss and act now.
- Review the next wave of high-yield payers by scanning a curated list of 3 dividend fortresses before payout momentum draws in income-focused investors.
- Track where capital is quietly shifting by reviewing 40 power grid technology and infrastructure stocks that could benefit if grid upgrades and electrification spending continue.
- Monitor potential resource demand changes through 17 top copper producer stocks that focus on established producers rather than speculative explorers.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com