


Banco Comercial Português (ENXTLS:BCP), Why Is It Back In The Spotlight?
Banco Comercial Português (ENXTLS:BCP) has drawn fresh attention after its shares closed at €1.21 on 24 September 2026. Recent price moves invite a closer look at performance, profitability and valuation.
Recent trading has come on the back of strong momentum, with Banco Comercial Português posting a 33.9% year to date share price return and a very large 5 year total shareholder return of around 8x, which suggests that investors are reassessing both its earnings profile and risk outlook rather than reacting to a single short term catalyst.
Scan the banking rally around Banco Comercial Português and compare it with 182 high quality undervalued stocks that currently show stronger fundamentals relative to their market pricing.
After such a sharp climb, the temptation is to wait for Banco Comercial Português to cool off. The real issue now is whether the current valuation already prices in that strength or still leaves a margin of safety.
Preferred P/E of 17x: Is it justified?
Banco Comercial Português now trades on a P/E of 17x, which means investors are paying €1.21 for each euro of recent earnings and accepting a richer tag than many European bank peers.
The P/E ratio compares the share price with earnings per share and gives a quick read on how much you are paying for the profit stream of a business. For a lender like Banco Comercial Português, this often reflects how the market views its profit profile, risk management and the stability of its banking operations across Portugal, Poland and Mozambique.
Here the valuation premium is clear. Management has a long record of profit expansion over the past 5 years and net margins currently sit at 28.5%, yet earnings over the last 12 months were affected by a one off loss of €468.6m and the return on equity is 13%, which is described as low. That mix of strong long term growth, a recent earnings setback and moderate profitability signals that investors are paying a higher multiple in anticipation of future progress rather than current efficiency alone.
Compared with a peer average P/E of 12.2x and a European banks sector average of 12.1x, Banco Comercial Português carries a materially higher multiple and is described as expensive relative to both its local and wider industry group.
See what the numbers say about this price — find out in our valuation breakdown.
Result: Price-to-earnings of 17x (OVERVALUED)
Still, that premium around Banco Comercial Português could unravel quickly if credit quality weakens or if earnings take another hit from unexpected one off items.
Find out about the key risks to this Banco Comercial Português narrative.
Another View on Banco Comercial Português's Value
The earnings multiple paints Banco Comercial Português as expensive, yet the SWS DCF model points in a different direction. At €1.21, the share price is described as trading about 17.1% below an estimated future cash flow value of €1.46, which frames the recent rally in a very different light.
That kind of gap can either close through price moves or changing expectations about those projected cash flows. The key question is which side adjusts first in your view.
Look into how the SWS DCF model arrives at its fair value.
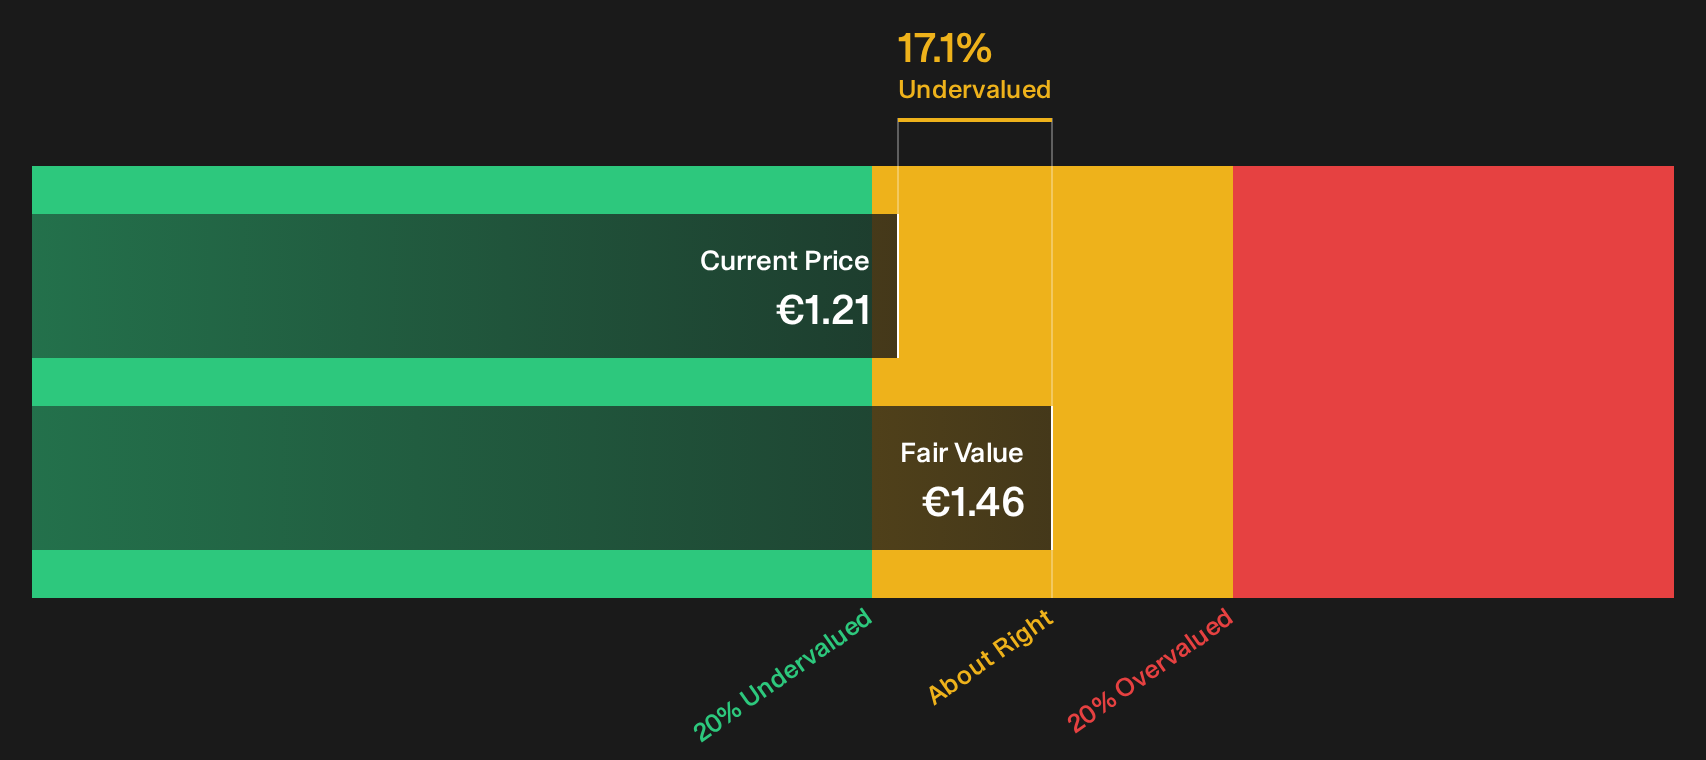
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Banco Comercial Português for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 182 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Positive or cautious, your conclusion on Banco Comercial Português should come from the underlying numbers rather than the headline move. Review both sides of the story and weigh the 2 key rewards and 1 important warning sign
Looking for more ideas beyond Banco Comercial Português?
If Banco Comercial Português has sharpened your focus, now is the moment to widen your watchlist with fresh opportunities that match your style and risk limits.
- Target potential mispricing by scanning a curated pool of 182 high quality undervalued stocks that combine solid fundamentals with more modest market expectations.
- Build a sturdier core to your portfolio by focusing on a list of solid balance sheet and fundamentals (202 results) that can better handle tougher operating conditions.
- Spot earlier opportunities before they attract broad attention by hunting through 620 high quality undiscovered gems with stronger numbers than their current profiles suggest.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com