


How Investors May Respond To Amano Stock After FTSE All World Removal
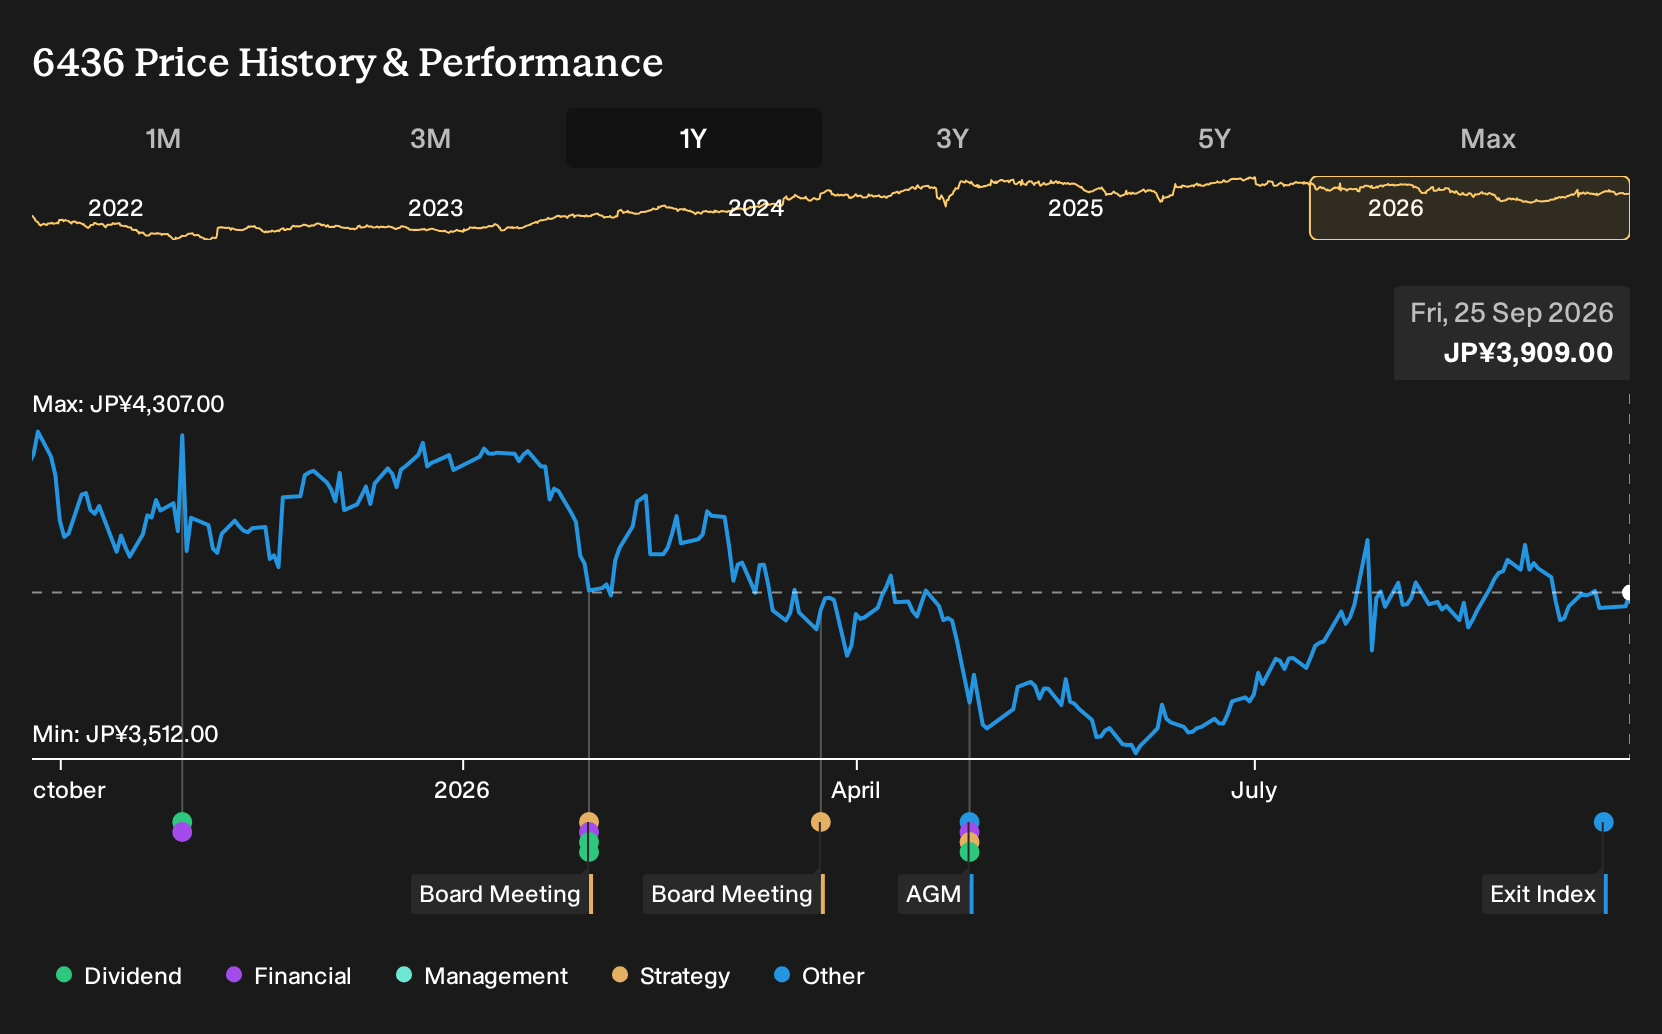
- Amano Corporation was removed from the FTSE All-World Index in September 2026. This benchmark adjustment can alter how index-linked investors allocate capital to the stock.
- The index exclusion focuses attention on Amano's core business profile and fundamentals, since passive flows may now play a smaller role in ownership.
- We will now examine how Amano's investment narrative could shift following its removal from the FTSE All-World Index as a key catalyst.
Redirect your attention from Amano's index exit and scan 18 high quality undervalued stocks, which could be next in line for fresh capital as index trackers rebalance.
What Is Amano's Investment Narrative?
Amano’s story still rests on a fairly straightforward belief. You need to think this is a solid, execution focused equipment and systems business that can keep turning its time and attendance, parking, and environmental solutions into steady earnings, even if growth expectations are moderate. Recent figures point to revenue of ¥176,429 and net income of ¥19,614, with earnings projected to rise 2.38% per year and revenue forecast at 4.9% per year, which is slower than the wider Japanese market.
The FTSE All World exclusion mostly affects how passive capital trades around the edges rather than the core thesis. In the short term, the more important swings likely come from demand for parking and time information systems, how well management manages capital intensive hardware and service rollouts, and whether profitability stays supported with a 15% return on equity and 11.1% net margin. One lingering issue is the unstable dividend track record, especially when recent 1 year share performance has trailed both the broader JP market and the electronic industry.
Even so, before leaning too heavily on Amano’s steady earnings profile, there is still the question of how its higher risk funding mix might...
There's only one way to know the right time to buy, sell or hold Amano. Head to Simply Wall St's company report for the latest analysis of Amano's Fair Value.
Reach Your Own Conclusion
Disagree with this assessment? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your Amano research is our analysis highlighting 3 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Amano. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Amano's overall financial health at a glance.
Looking For More Ideas Beyond Amano?
If you want to stress test your view on Amano and keep your opportunity set broad, it helps to line it up against other companies with different strengths and risk profiles. The Simply Wall St Screener can surface stocks that match the mix of balance sheet strength, income potential, or upside you are looking for.
- If capital preservation and a smoother ride matter most to you, start with a group of businesses screened as 21 resilient stocks with low risk scores that may suit a more cautious approach.
- For investors who care about income today as much as price changes tomorrow, review a set of 14 dividend fortresses and see which ones fit your payout and stability criteria.
- If you prefer financially solid operators before anything else, scan a list of solid balance sheet and fundamentals (22 results) and compare how their fundamentals stack up against Amano.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com