


We Think poLight (OB:PLT) Can Easily Afford To Drive Business Growth
We can readily understand why investors are attracted to unprofitable companies. By way of example, poLight (OB:PLT) has seen its share price rise 205% over the last year, delighting many shareholders. But while the successes are well known, investors should not ignore the very many unprofitable companies that simply burn through all their cash and collapse.
So notwithstanding the buoyant share price, we think it's well worth asking whether poLight's cash burn is too risky. For the purpose of this article, we'll define cash burn as the amount of cash the company is spending each year to fund its growth (also called its negative free cash flow). The first step is to compare its cash burn with its cash reserves, to give us its 'cash runway'.
How Long Is poLight's Cash Runway?
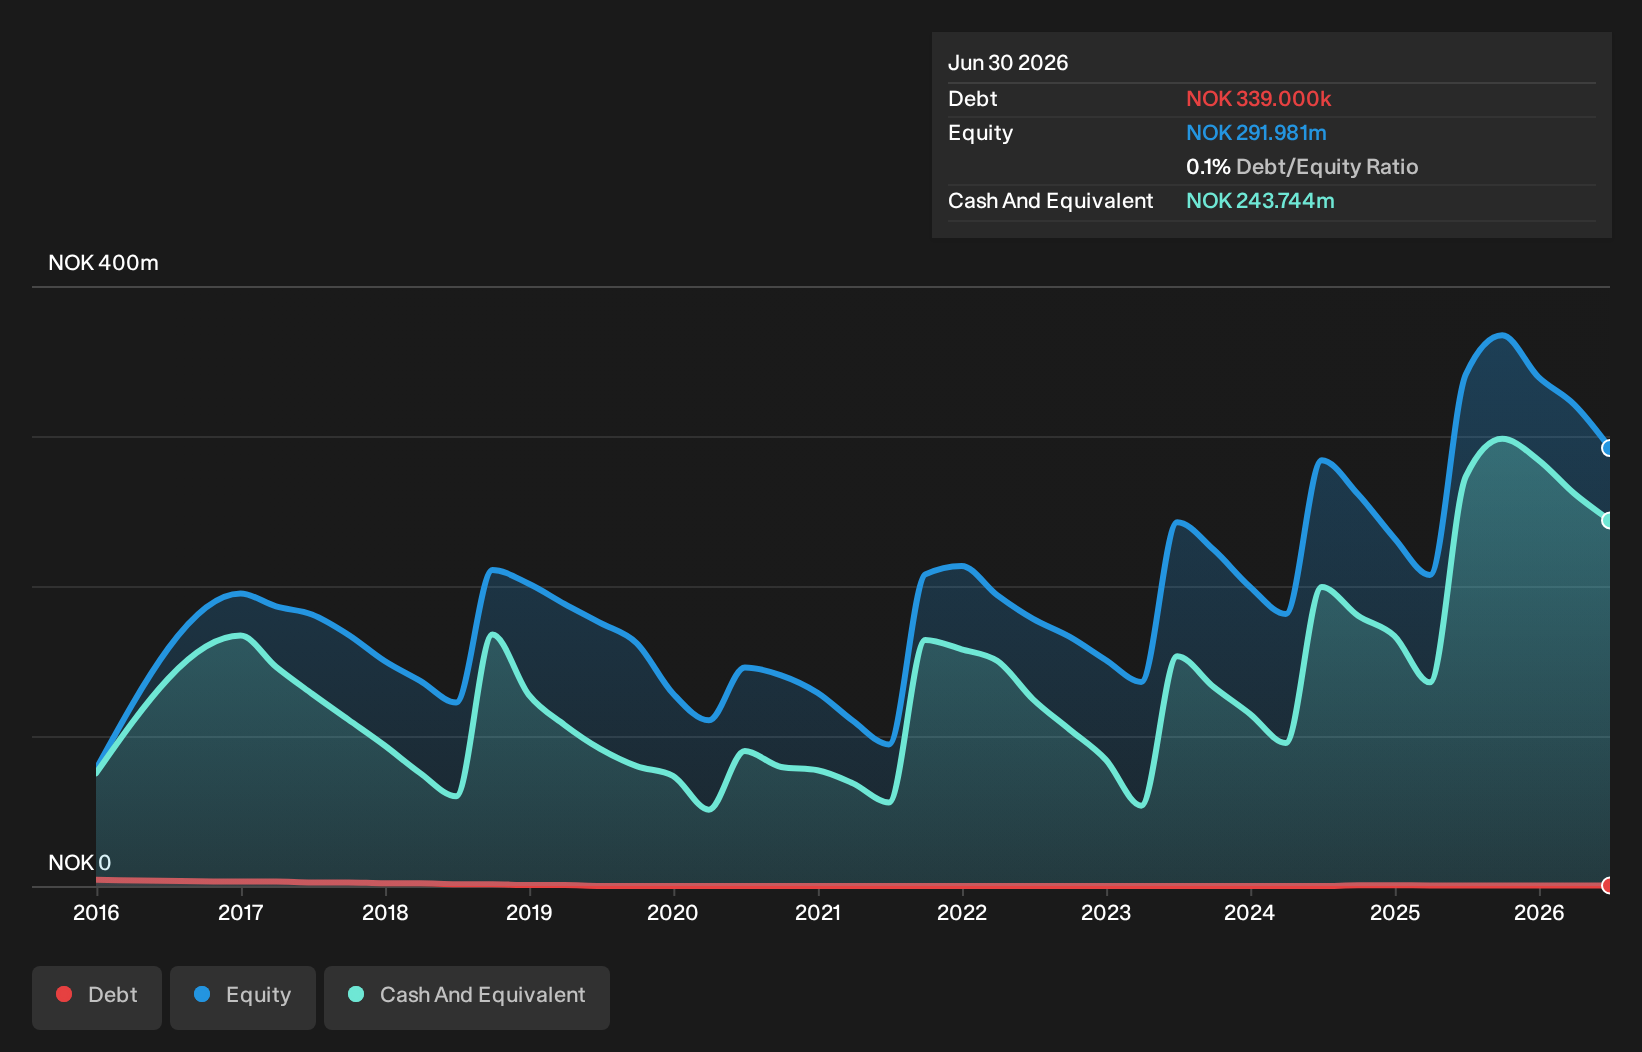
A cash runway is defined as the length of time it would take a company to run out of money if it kept spending at its current rate of cash burn. poLight has such a small amount of debt that we'll set it aside, and focus on the kr244m in cash it held at June 2026. In the last year, its cash burn was kr79m. That means it had a cash runway of about 3.1 years as of June 2026. A runway of this length affords the company the time and space it needs to develop the business. Depicted below, you can see how its cash holdings have changed over time.
View our latest analysis for poLight
How Well Is poLight Growing?
On balance, we think it's mildly positive that poLight trimmed its cash burn by 9.1% over the last twelve months. But the operating revenue growth of 245% was even better. It seems to be growing nicely. In reality, this article only makes a short study of the company's growth data. You can take a look at how poLight is growing revenue over time by checking this visualization of past revenue growth.
How Easily Can poLight Raise Cash?
While poLight seems to be in a decent position, we reckon it is still worth thinking about how easily it could raise more cash, if that proved desirable. Generally speaking, a listed business can raise new cash through issuing shares or taking on debt. Many companies end up issuing new shares to fund future growth. By looking at a company's cash burn relative to its market capitalisation, we gain insight on how much shareholders would be diluted if the company needed to raise enough cash to cover another year's cash burn.
poLight has a market capitalisation of kr3.2b and burnt through kr79m last year, which is 2.5% of the company's market value. That means it could easily issue a few shares to fund more growth, and might well be in a position to borrow cheaply.
So, Should We Worry About poLight's Cash Burn?
As you can probably tell by now, we're not too worried about poLight's cash burn. In particular, we think its revenue growth stands out as evidence that the company is well on top of its spending. Its weak point is its cash burn reduction, but even that wasn't too bad! Taking all the factors in this report into account, we're not at all worried about its cash burn, as the business appears well capitalized to spend as needs be. Taking a deeper dive, we've spotted 3 warning signs for poLight you should be aware of, and 1 of them doesn't sit too well with us.
Of course, you might find a fantastic investment by looking elsewhere. So take a peek at this free list of companies with significant insider holdings, and this list of stocks growth stocks (according to analyst forecasts)
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team (at) simplywallst.com.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.