


How Investors May Respond To Skanska (OM:SKA B) Budapest Office Sale
- Skanska AB has agreed to build an approximately 22,700 square meter, 48 MW colocation data center in Georgia, USA, under an existing client relationship, and has also invested in the first phase of the Nowy Format office project in Kraków as well as divested the second phase of the H2Offices complex in Budapest for €98 million.
- The combination of a large US data center contract, capital recycling through the H2Offices sale, and a new energy efficient Kraków office development highlights how Skanska is actively shifting capital between regions and project types, while keeping a focus on certified, electricity powered buildings.
- We will now see how Skanska's Budapest H2Offices divestment and capital rotation could influence the broader investment narrative investors follow.
Scan beyond Skanska's data center and green office projects to spot other contractors positioned for the same themes of infrastructure, electrification, and resilient balance sheets with our curated list of solid balance sheet and fundamentals (202 results).
Skanska Investment Narrative Recap
To own Skanska, you broadly need to believe that a large, diversified construction and development group can turn a deep order book, ESG focused projects and a solid balance sheet into steadier earnings, despite patchy property markets. The current data center win and Kraków investment look incremental rather than game changing for near term numbers.
The key short term swing factor still sits in project execution and timing of commercial property divestments. Risks remain around weak Nordic property demand, lumpy sales and cost inflation on long duration projects. The latest contracts mostly reinforce the existing backlog story instead of shifting that risk reward balance.
The Nowy Format office investment in Kraków is the most relevant recent update for the current news. It shows Skanska leaning into Central European offices with green certifications and all electric operations, while the Budapest H2Offices sale frees up capital. That pairing matters for you because it links development risk with balance sheet discipline.
For catalysts, this kind of project tests whether demand for certified, electricity powered offices can offset softness in other property markets and support future divestments. Execution risk is clear. Skanska must control build costs, lease up space and then sell into a still cautious transaction market without adding too much earnings volatility along the way.
Skanska's narrative projects SEK 206.0b revenue and SEK 9.2b earnings by 2029. This projection is based on an assumed 6.1% yearly revenue growth and an earnings increase of about SEK 3.5b from SEK 5.7b today.
Uncover why Skanska's fair value suggests it is in line with its current price.
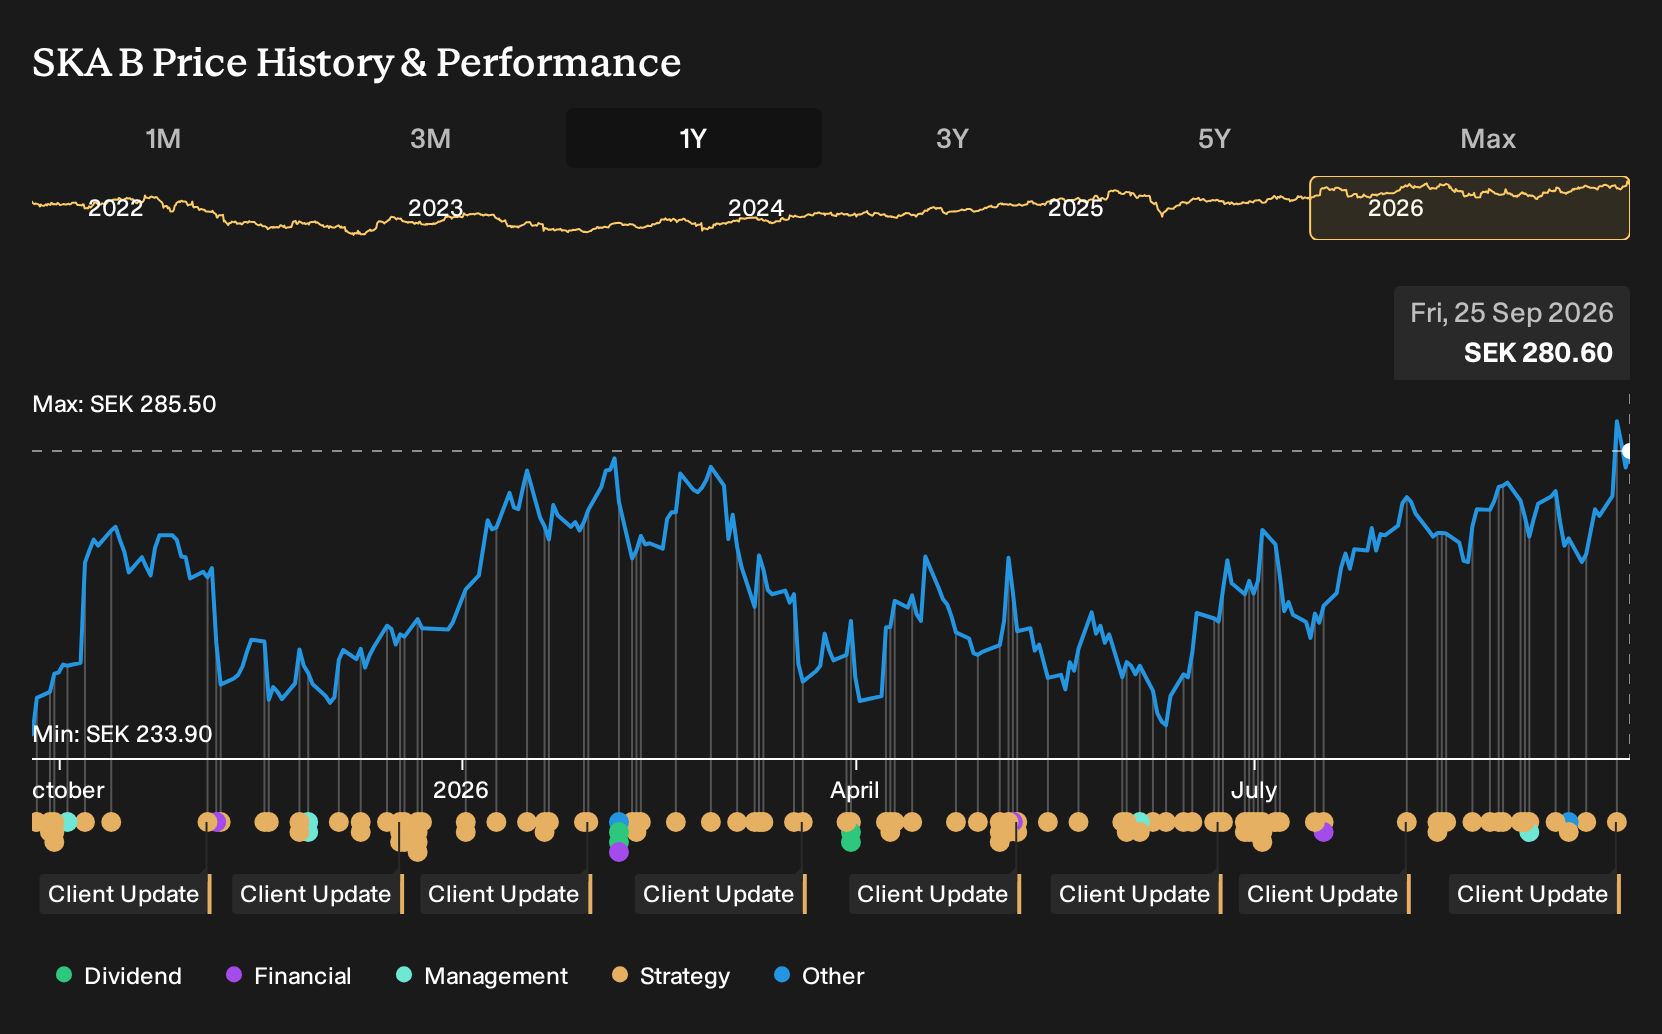
Exploring Other Perspectives
Not every analyst sees the Skanska story as just steady progress and capital recycling. The most optimistic group leans hard into the US and infrastructure angle, expecting about 7.8% annual revenue growth and SEK 9.8b earnings by 2029. Those forecasts were set before this data center and Kraków news, so you may want to explore how views could shift.
Explore 4 other Skanska fair value estimates, including one that suggests as much as 22% potential upside from the current price.
Reach Your Own Conclusion
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Skanska research is our analysis highlighting 2 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Skanska. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Skanska's overall financial health at a glance.
Looking For More Skanska-Like Investment Ideas?
If the Skanska story has you thinking about balance sheets, project pipelines, and where capital could compound over time, it can help to line it up against other listed contractors and asset heavy businesses. The Simply Wall St Screener lets you shift from a single ticker view to a curated set of companies that share some of the same themes.
- If you want potential mispricing on quality, scan a curated set of resilient businesses that currently look cheap on fundamentals with our 181 high quality undervalued stocks.
- For investors who care about getting paid while they wait, focus on companies with higher yields and robust payout histories through the 162 dividend fortresses.
- If capital preservation comes first for you, narrow in on companies with stronger balance sheets and steadier financial profiles using the 228 resilient stocks with low risk scores.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com