


3 Japanese Founder Led Stocks To Own In September 2026
Long term Treasury yields recently reached levels last seen in the early 2000s, which puts pressure on highly leveraged firms yet shines a spotlight on businesses with disciplined capital use. Many Japanese founder led companies fit that description, with leaders who often treat the balance sheet like their own wallet. This article highlights three stocks from that group and explains why committed founders can matter for long term investors.
The three founder led stocks in this article are only a sample of what disciplined ownership can look like in public markets, and the full screen surfaced 99 more companies with similarly compelling stories that are not covered here.
If you want to identify and analyze founder led opportunities that fit your own risk profile, head straight to the Founder-Led Companies screener.
Terra Drone (TSE:278A)
Overview: Terra Drone develops founder-led industrial drone platforms and software that power infrastructure inspection, land and mine surveying, and agricultural spraying worldwide.
Operations: Terra Drone generates approximately ¥4,278 million from its Drone Solutions Segment and about ¥797 million from its Traffic Management Segment.
Market Cap: ¥213.9 billion
Terra Drone offers investors a founder who remains closely involved in the development of core products such as Terra UT and Terra 3D Inspect. Analysts expect revenue to grow 16.27% a year, compared with a 6.5% broader JP market forecast. The close alignment between product vision and projected revenue trajectory is notable, although outcomes will depend on how uncertainties around future profitability and funding are addressed.
Those open questions on profitability and funding make it worth scanning the 1 key reward and 2 important warning signs (1 is major!) before Terra Drone’s growth story decouples from its risk profile.

Sansan (TSE:4443)
Overview: Sansan runs founder-influenced cloud platforms that help enterprises manage business contacts, invoices, contracts, and virtual business cards across Japan.
Operations: Sansan generates ¥46,847 million from the Sansan/Bill One Business, ¥6,720 million from Eight, and ¥415 million from Others, all in Japan.
Market Cap: ¥258.4 billion
Sansan gives you a founder still closely shaping the flagship contact-management cloud, alongside earnings that recently moved from ¥424 million to ¥6,778 million. That mix of hands-on leadership, platform scale, and board support may be important for long term holders, depending on how one unseen pressure around that earnings profile plays out.
That unseen pressure is worth unpacking through the 3 key rewards and 1 important major warning sign to see whether Sansan’s earnings surge is masking fragility or setting up a stronger phase.

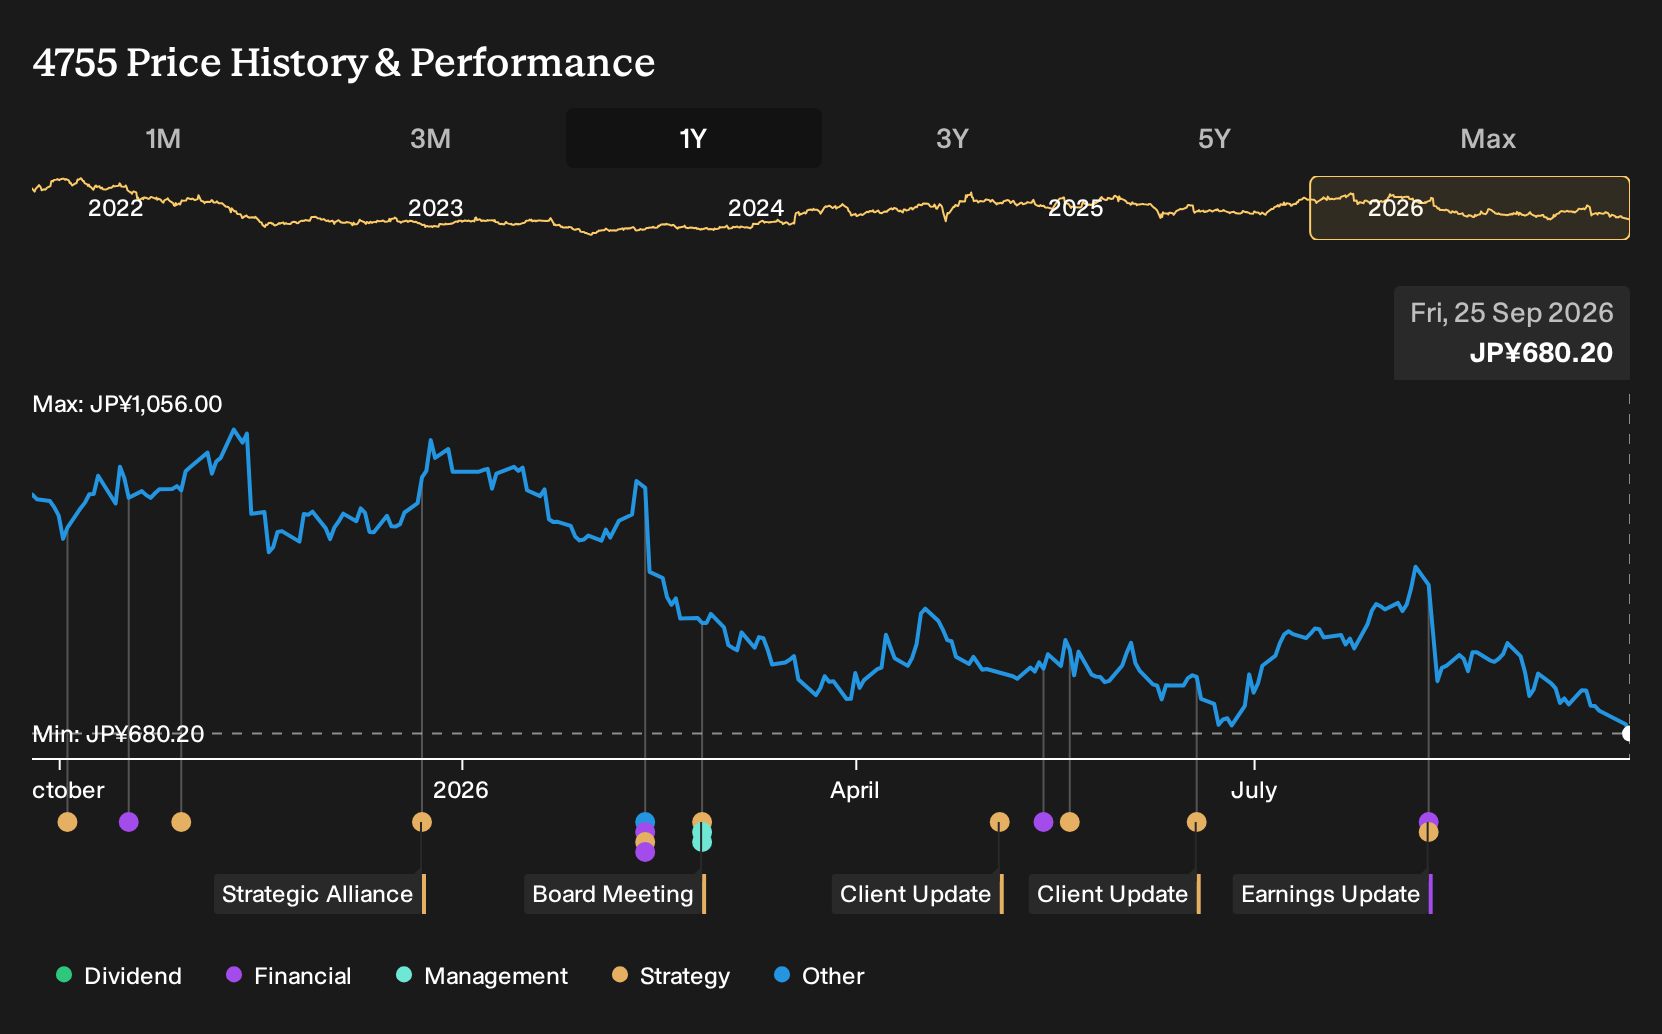
Rakuten Group (TSE:4755)
Overview: Rakuten Group runs a founder-led ecosystem that links e-commerce, fintech, and mobile services, with Hiroshi Mikitani steering long term direction.
Operations: Rakuten Group generates ¥1.4 trillion from Internet Services, ¥1.1 trillion from FinTech, and ¥513 billion from Mobile, before internal offsets.
Market Cap: ¥1.5 trillion
For investors who care about founder ownership, Rakuten Group offers a case where the original architect still pushes the major engines of growth and keeps e-commerce, payments, and mobile tightly connected under a single vision.
"Rakuten Mobile is achieving rapid growth in subscribers, expected to drive the growth of the entire Rakuten ecosystem, contributing significantly to future revenue increases through cross-selling of Rakuten services to mobile users."
What happens to that vision if one crucial assumption about future profitability and funding flexibility shifts even slightly against the current script?
If that assumption shifts, you will want the full narrative for Rakuten Group to see whether Rakuten Group’s ecosystem is accelerating, stalling, or quietly masking a stronger engine.
Curious To Explore Fresh Alternatives?
Markets move fast and the best breakout opportunities rarely stay under the radar for long. Scan these fresh ideas before the momentum is fully caught and consider acting while they are still developing.
- Target resilient cash generators while they are still quietly compounding by reviewing the list of solid balance sheet and fundamentals (22 results).
- Hunt for yield that could support a portfolio even when prices are swinging by checking the 14 dividend fortresses.
- Track where AI infrastructure money may be directed next by scanning the 87 AI infrastructure stocks.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com