


Arlo (ARLO) Stock Looks Fully Valued After Its 99% Gain
Arlo Technologies has seen its share price move around over the years, and with the stock now reflecting a long multi year gain, investors are asking a straightforward question about value. Is the current US$12.84 price properly supported by what the business is earning today and is expected to earn over time.
- Over the past 5 years, Arlo Technologies has returned 99.1%, which puts real pressure on the question of whether those gains line up with the underlying earnings power of the business.
- Recent product news around Arlo Secure 7 and its AI driven services may support expectations for future subscription based income and margins, which feeds directly into how much earnings investors are willing to pay for today.
- There is a second opinion on Arlo Technologies worth weighing. See what analysts think Arlo Technologies's shares could be worth.
The issue now is whether Arlo Technologies' current share price is justified by its earnings when set against the Fair Ratio benchmark.
If you want to pressure test whether Arlo Technologies' earnings-based valuation question shows up elsewhere in the market, compare it with the companies in 31 high quality undervalued stocks
Has Arlo Technologies Run Too Far on Earnings?
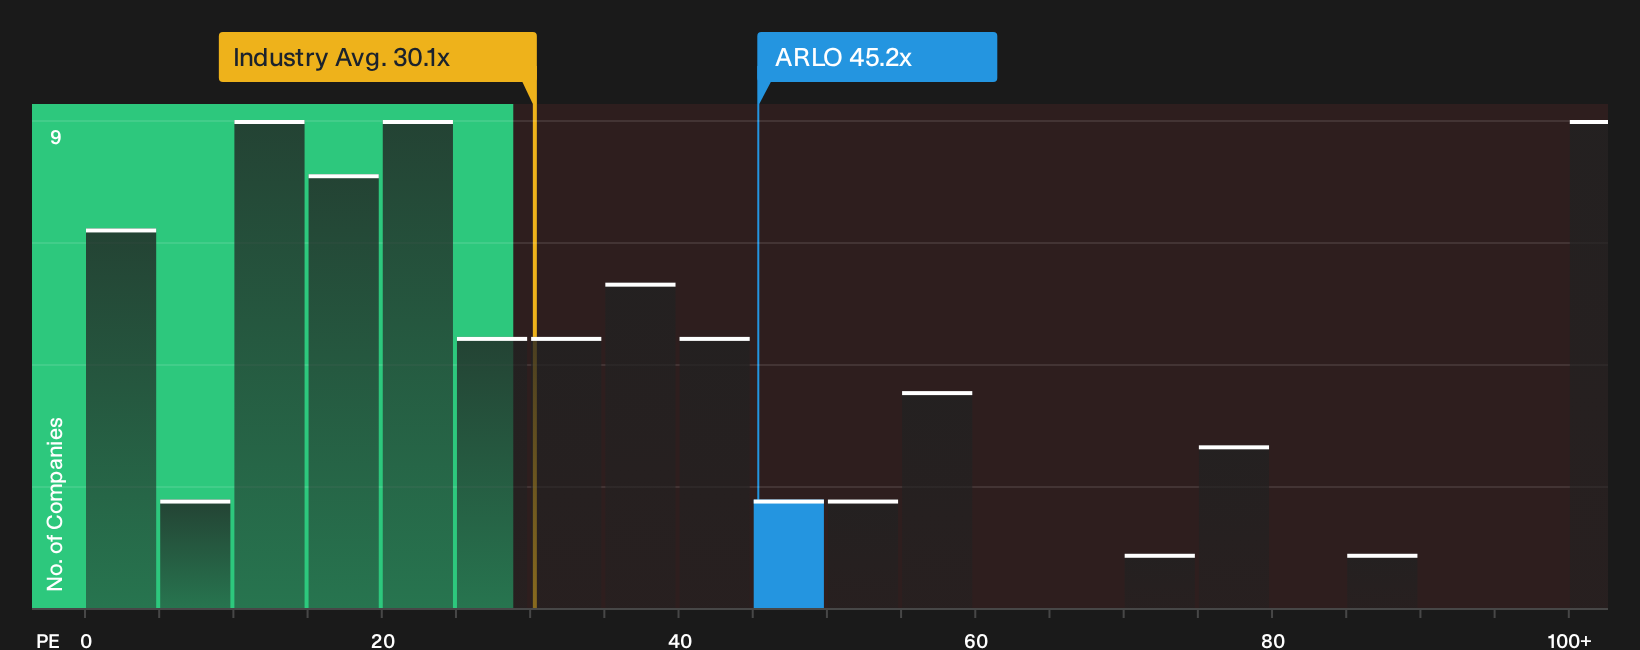
The P/E ratio matters for Arlo Technologies because earnings are now a central reference point for how the stock is priced. At roughly 45.2x earnings, Arlo trades at a clear premium to the wider Electronic industry, which sits near 30.1x, and to its peer group around 21.6x. That gap means buyers today are paying meaningfully more per dollar of profit than they would for many comparable hardware and device makers.
The Fair Ratio, which blends factors like Arlo Technologies' growth profile, profitability, size and risk into a single benchmark, points to the current P/E as overvalued rather than cheap. Despite the launch of Arlo Secure 7 and its AI heavy service push giving the story fresh momentum, the share price already embeds a richer earnings multiple than this tailored yardstick suggests is comfortable. For anyone considering the stock, the key question is whether Arlo can justify that premium over time or whether the P/E is doing too much of the heavy lifting already. Explore the numbers behind Arlo Technologies's P/E valuation.
The Arlo Technologies Narrative: What Would Justify Today's Price?
Simply Wall St Narratives for Arlo Technologies pick up exactly where that P/E puzzle leaves you by spelling out which combinations of future growth, margins and earnings would need to play out for the stock to be worth meaningfully more or less than today's price. Each Narrative ties a fair value estimate to a specific storyline about Arlo Technologies' possible catalysts and risks, so you can track over time which version of events appears to be unfolding on the Community page.
One of the top community narratives on Arlo Technologies: 40% undervalued
"Bullish analysts point to Arlo’s move from a low cost camera vendor to a premium, service first recurring revenue platform as a core pillar..."
Discover why this Narrative puts Arlo Technologies at 40% undervalued.
One big piece of the Arlo Technologies puzzle is still off the page
Arlo Technologies can only deliver on any valuation story if the people in charge are both capable and rewarded in a way that lines up with your interests as a shareholder. See who runs Arlo Technologies and how they are paid.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com