


Is YASKAWA Electric (TSE:6506) Expensive On Its Recent Share Price Slide?
YASKAWA Electric (TSE:6506) is back on investor watchlists after its share price fell about 9% over the past month and roughly 34% in the past 3 months, bringing renewed attention to its fundamentals.
Recent trading has been choppy for YASKAWA Electric, with the share price down about 9% over the past month and roughly 34% over three months. Even so, investors still have a 1-year total shareholder return of about 45%, which indicates fading short-term momentum following a much stronger prior run.
Scan beyond YASKAWA Electric and see how other robotics and automation players have been moving with the curated 93 robotics and automation stocks.
After a sharp pullback, yet with a still strong 1 year return, YASKAWA Electric now trades at a wide gap to both analyst targets and one intrinsic value model. So where does a reasonable fair value range actually sit?
Preferred P/E Multiple of 34.4x: Is it justified?
On the latest close at ¥4,480, YASKAWA Electric trades on a P/E of 34.4x, which screens as expensive compared with both its Machinery peers and its own estimated fair P/E level.
The P/E ratio compares the share price to earnings per share. For a business like YASKAWA Electric in motion control and robotics, this metric effectively shows how much investors are paying today for each unit of current profit.
That 34.4x multiple sits well above the JP Machinery industry average of 13.4x. This points to a rich valuation relative to sector peers. It is also higher than the estimated fair P/E of 26.8x. This suggests the market price embeds a stronger outlook than the level that model implies it could move toward.
Explore the SWS fair ratio for YASKAWA Electric.
Result: Price-to-earnings of 34.4x (OVERVALUED)
Still, the rich P/E can quickly look exposed if robotics demand softens or if YASKAWA Electric posts weaker earnings progress than recent annual figures suggest.
Find out about the key risks to this YASKAWA Electric narrative.
Another View on YASKAWA Electric’s Value
The SWS DCF model lands on an estimated future cash flow value of about ¥2,818.74 per share, which is well below YASKAWA Electric’s current ¥4,480 price. That suggests the stock appears expensive when viewed through this lens. How much weight should you really give to a single cash flow model?
Look into how the SWS DCF model arrives at its fair value.
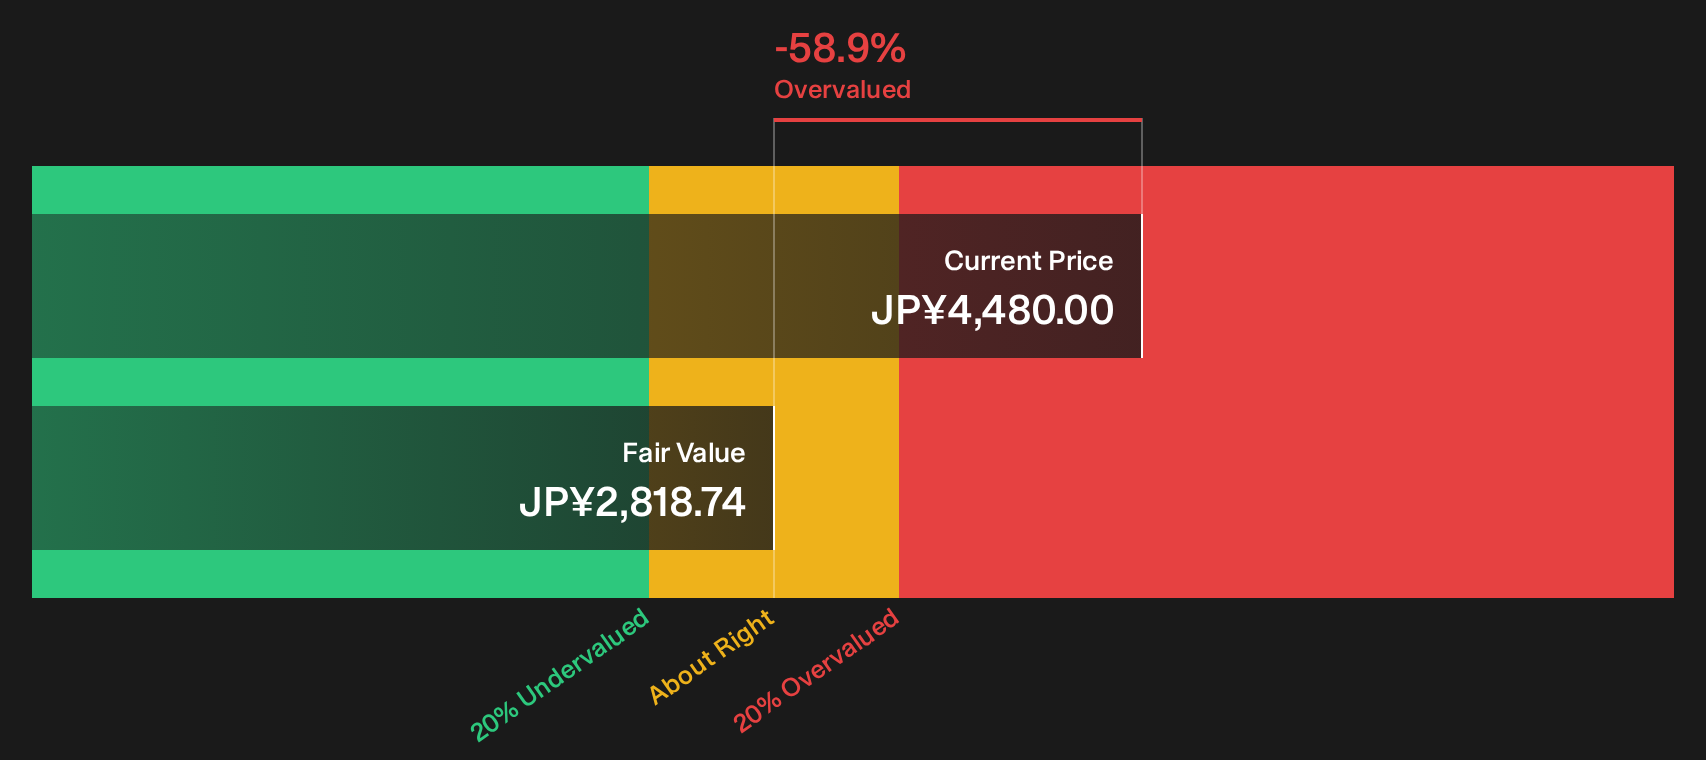
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out YASKAWA Electric for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 18 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
With sentiment on YASKAWA Electric clearly split between recent share price weakness and earlier gains, start reviewing the numbers yourself and decide how you feel about the balance of risks and upsides. To help pressure test that view quickly, take a closer look at the 2 key rewards and 2 important warning signs.
Looking for more investment ideas beyond YASKAWA Electric?
If YASKAWA Electric has sharpened your focus on valuation and quality, now is the moment to widen your watchlist and uncover a few fresh contenders.
- Target resilient income potential by scanning for companies in the 14 dividend fortresses that may align with your yield and stability preferences.
- Hunt for quality at a measured price by reviewing the 18 high quality undervalued stocks that combine stronger fundamentals with more modest market expectations.
- Prioritise capital protection first and returns second by assessing the 21 resilient stocks with low risk scores before others spot the same lower volatility profile.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com