


We're Not Very Worried About MEGAIN Holding (Cayman)'s (HKG:6939) Cash Burn Rate
We can readily understand why investors are attracted to unprofitable companies. For example, MEGAIN Holding (Cayman) (HKG:6939) shareholders have done very well over the last year, with the share price soaring by 176%. But while the successes are well known, investors should not ignore the very many unprofitable companies that simply burn through all their cash and collapse.
In light of its strong share price run, we think now is a good time to investigate how risky MEGAIN Holding (Cayman)'s cash burn is. In this article, we define cash burn as its annual (negative) free cash flow, which is the amount of money a company spends each year to fund its growth. We'll start by comparing its cash burn with its cash reserves in order to calculate its cash runway.
When Might MEGAIN Holding (Cayman) Run Out Of Money?
A cash runway is defined as the length of time it would take a company to run out of money if it kept spending at its current rate of cash burn. As at June 2026, MEGAIN Holding (Cayman) had cash of CN¥187m and no debt. Importantly, its cash burn was CN¥28m over the trailing twelve months. So it had a cash runway of about 6.6 years from June 2026. While this is only one measure of its cash burn situation, it certainly gives us the impression that holders have nothing to worry about. The image below shows how its cash balance has been changing over the last few years.
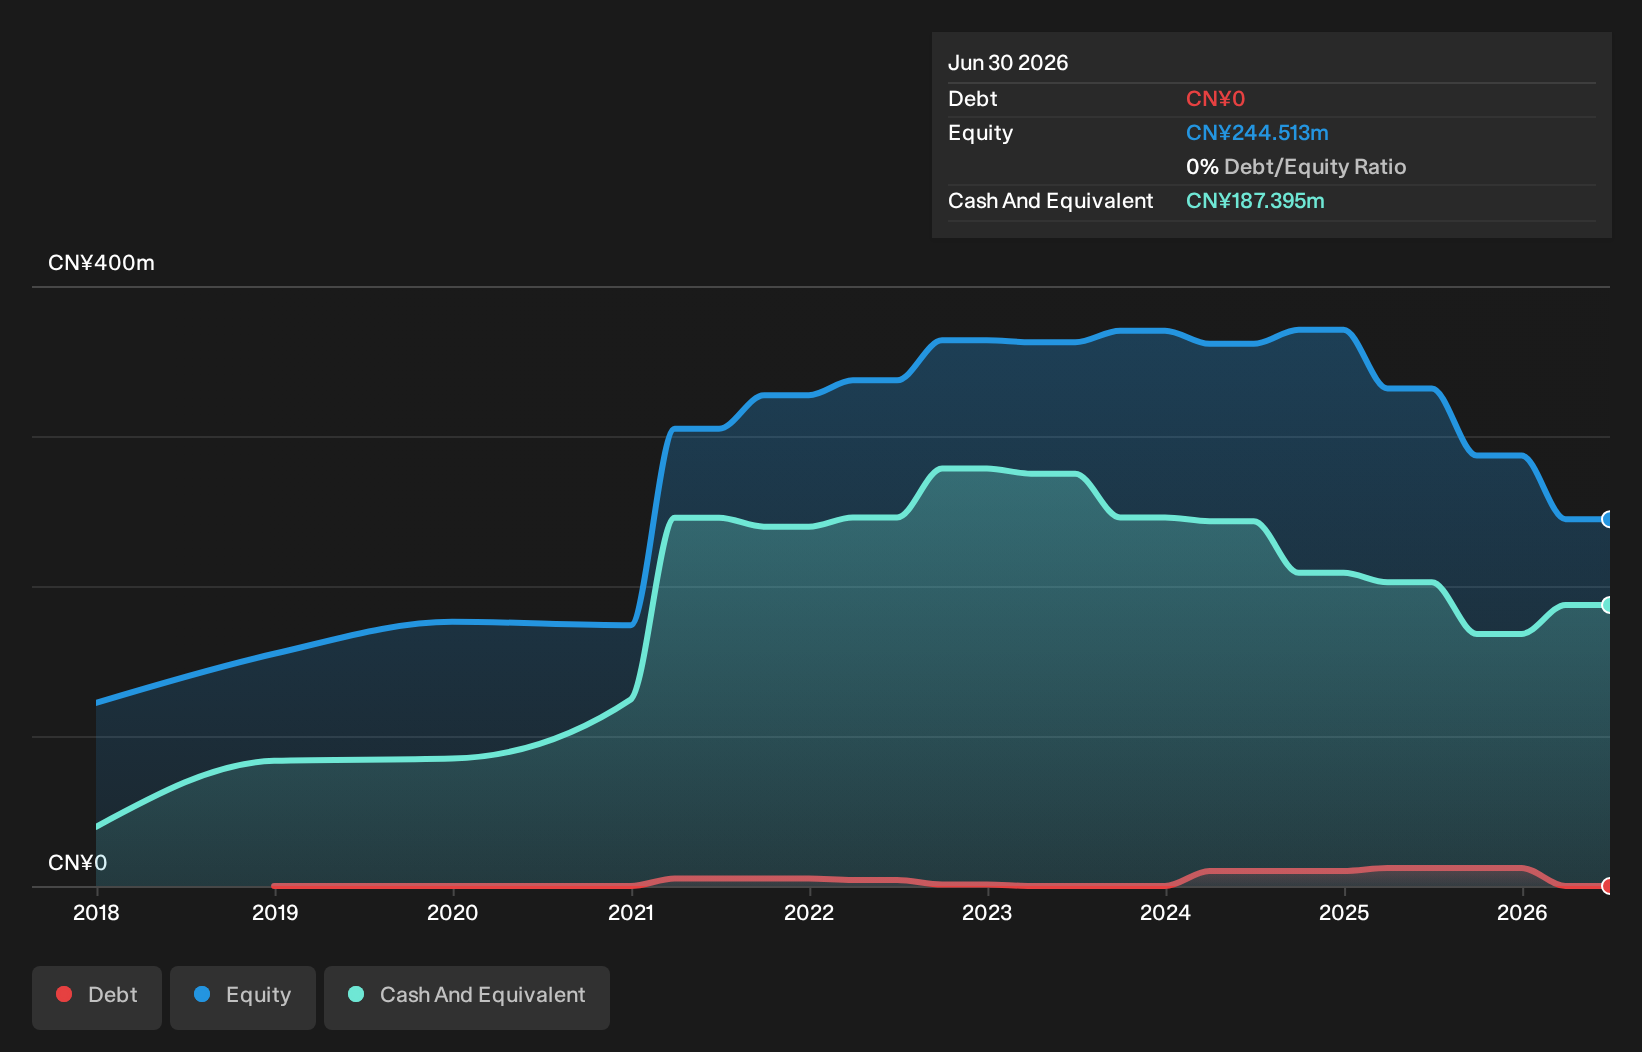
See our latest analysis for MEGAIN Holding (Cayman)
How Well Is MEGAIN Holding (Cayman) Growing?
MEGAIN Holding (Cayman) actually ramped up its cash burn by a whopping 53% in the last year, which shows it is boosting investment in the business. That's not ideal, but we're made even more nervous given that operating revenue was flat over the same period. Considering both these metrics, we're a little concerned about how the company is developing. In reality, this article only makes a short study of the company's growth data. This graph of historic earnings and revenue shows how MEGAIN Holding (Cayman) is building its business over time.
Can MEGAIN Holding (Cayman) Raise More Cash Easily?
While MEGAIN Holding (Cayman) seems to be in a fairly good position, it's still worth considering how easily it could raise more cash, even just to fuel faster growth. Companies can raise capital through either debt or equity. Many companies end up issuing new shares to fund future growth. We can compare a company's cash burn to its market capitalisation to get a sense for how many new shares a company would have to issue to fund one year's operations.
Since it has a market capitalisation of CN¥661m, MEGAIN Holding (Cayman)'s CN¥28m in cash burn equates to about 4.3% of its market value. Given that is a rather small percentage, it would probably be really easy for the company to fund another year's growth by issuing some new shares to investors, or even by taking out a loan.
So, Should We Worry About MEGAIN Holding (Cayman)'s Cash Burn?
As you can probably tell by now, we're not too worried about MEGAIN Holding (Cayman)'s cash burn. For example, we think its cash runway suggests that the company is on a good path. Although its increasing cash burn does give us reason for pause, the other metrics we discussed in this article form a positive picture overall. Considering all the factors discussed in this article, we're not overly concerned about the company's cash burn, although we do think shareholders should keep an eye on how it develops. Separately, we looked at different risks affecting the company and spotted 4 warning signs for MEGAIN Holding (Cayman) (of which 1 is a bit unpleasant!) you should know about.
Of course, you might find a fantastic investment by looking elsewhere. So take a peek at this free list of interesting companies, and this list of stocks growth stocks (according to analyst forecasts)
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team (at) simplywallst.com.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.