


Cowboys Stadium Deal Could Be A Game Changer For AT&T Stock (T)
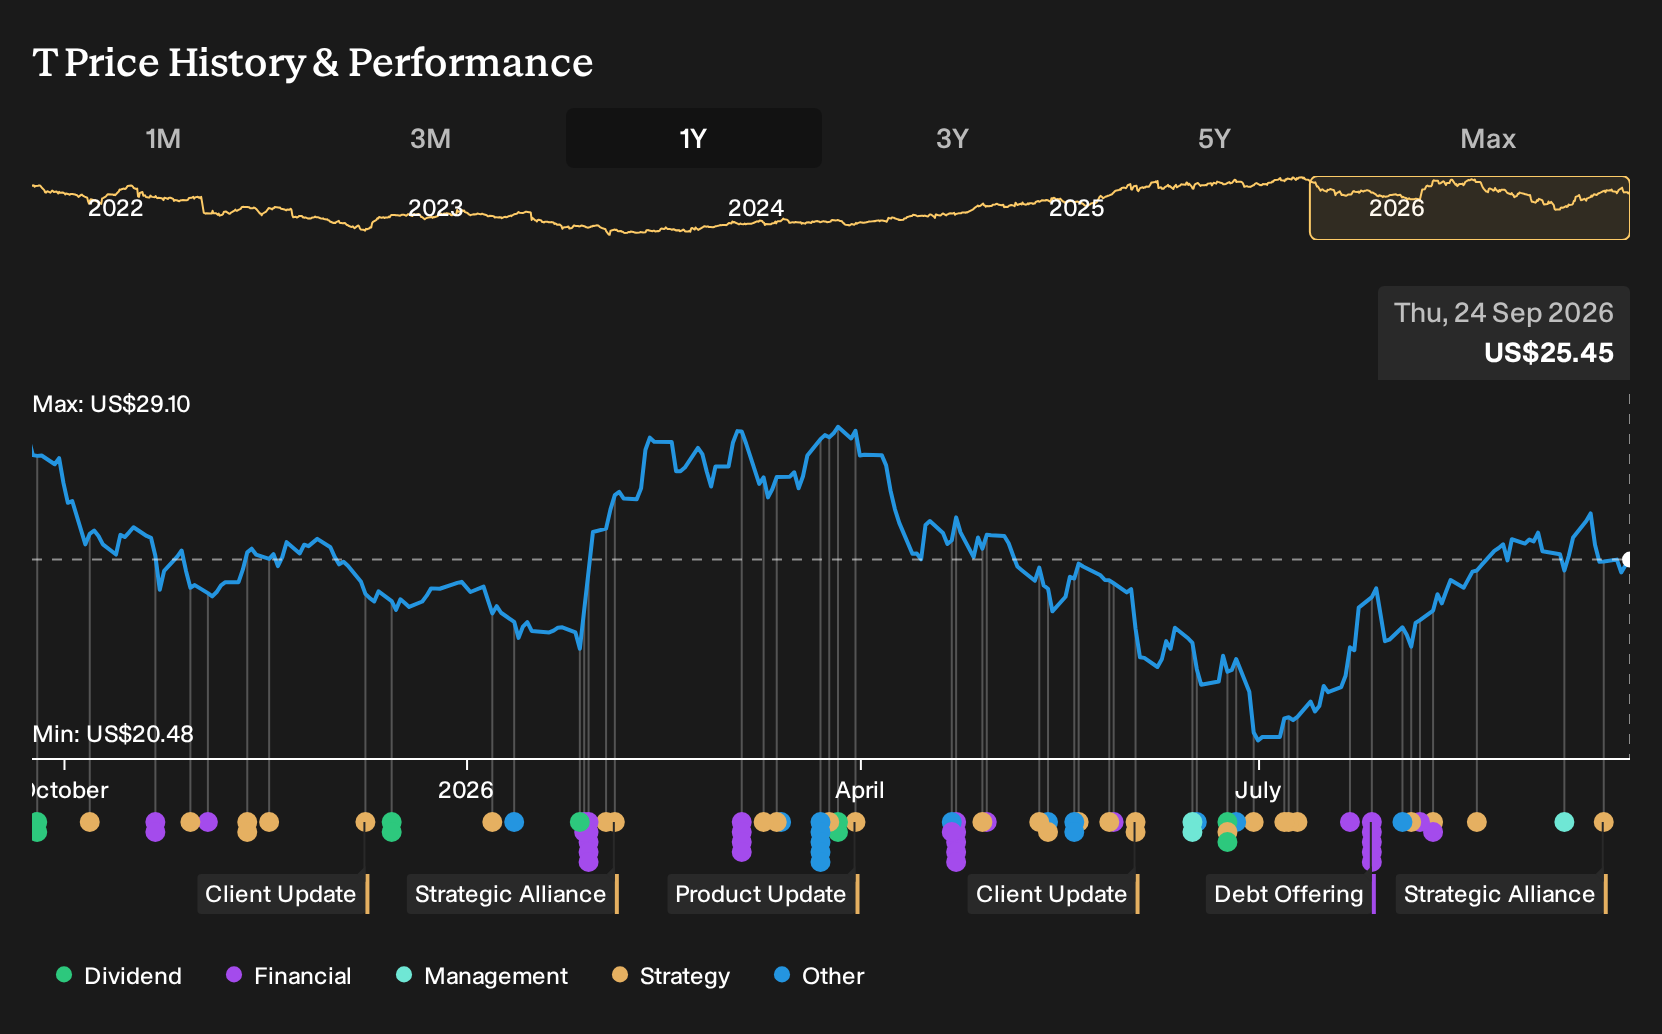
- AT&T's board declared quarterly dividends on its 5.000% Series A and 4.750% Series C perpetual preferred stock, alongside a US$0.2775 common stock payout. All dividends are payable on 2 November 2026 to holders of record on 12 October 2026.
- The renewed agreement with the Dallas Cowboys turns AT&T Stadium into a live testing ground for connectivity, mixed reality and AI fan experiences. This ties the telecom group's network investments directly to visible, high-usage consumer and enterprise use cases.
- We will now examine how AT&T's stadium technology agreement with the Dallas Cowboys could influence the broader investment narrative around connectivity.
AT&T Investment Narrative Recap
To own AT&T, you need to believe that heavy investment in 5G and fiber can offset pressure in legacy wireline and a slow wireless market. In the near term, the focus is on keeping churn under control while monetising data usage more effectively. The fresh dividend declarations signal no obvious shift in that operating focus.
The main short term swing factor remains execution on network build and cost cuts while carrying a high debt load and facing intense competition. The biggest risk is that returns on new fiber and spectrum spend fall short, which would strain cash generation and make it harder to keep funding both investment and shareholder payouts.
The renewed Dallas Cowboys stadium agreement looks particularly relevant right now. It ties AT&T’s capital spend in 5G and fiber directly to visible, high-traffic use cases such as mixed reality, smarter routing inside the venue and AI supported fan engagement. This is where the firm is trying to turn raw capacity into higher value relationships.
For investors watching catalysts, this type of contract helps test new services in a demanding setting before pushing them to enterprise and other venue clients. Execution risk remains. The business must convert technology wins into stable revenue streams at a time when earnings are forecast to decline and legacy wireline drag has not gone away.
AT&T's narrative projects US$136.1b revenue and US$18.3b earnings by 2029. This assumes 2.5% yearly revenue growth and an earnings decrease of US$3b from US$21.3b today.
Uncover why AT&T's fair value indicates a 14% potential upside to its current price that could narrow quickly.
Exploring Other Perspectives
One alternative view puts AT&T’s debt load and cash demands front and center. The most pessimistic analysts were modeling only 1.7% annual revenue growth to about US$134.0b and earnings of roughly US$17.2b by 2029. You can read that as a warning that dividend affirmations and the Cowboys deal might eventually reshape, or reinforce, those cautious assumptions.
Explore 7 other AT&T fair value estimates, including one that indicates as much as 17% downside from the current price.
Reach Your Own Conclusion
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your AT&T research is our analysis highlighting 3 key rewards and 4 important warning signs that could impact your investment decision.
- See our latest analysis for AT&T. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate AT&T's overall financial health at a glance.
Looking for more investment ideas beyond AT&T?
If the AT&T story has sharpened your thinking about income, risk and quality, you can use that same lens across the wider market with the Simply Wall St Screener. It helps you quickly filter for stocks that match your own priorities rather than someone else's model.
- If resilience is top of mind, you can focus on businesses that combine durable operations with conservative finances through our 30 resilient stocks with low risk scores.
- If you want balance sheet strength to sit alongside AT&T in your portfolio, you can start with a curated list of solid balance sheet and fundamentals (24 results) that emphasizes robust fundamentals.
- If you are hunting for less crowded ideas, you can widen the search to a 16 high quality undiscovered gems that pairs quality metrics with under-the-radar coverage.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com