


Undiscovered Gems in Asia to Explore This September 2026
As the Asian markets navigate a landscape shaped by recent rate hikes from central banks like the Bank of Japan, investors are closely watching small-cap stocks for their potential to outperform in an environment where major indices show mixed results. In this context, identifying promising stocks involves looking for companies that demonstrate resilience amid economic fluctuations and possess innovative capabilities to capitalize on emerging trends.
Top 10 Undiscovered Gems With Strong Fundamentals In Asia
| Name | Debt To Equity | Revenue Growth | Earnings Growth | Health Rating |
|---|---|---|---|---|
| Inner Mongolia Xingye Silver & Tin Mining | 37.31% | 28.46% | 51.65% | ★★★★★★ |
| Apex Mining | 22.02% | 24.39% | 37.14% | ★★★★★★ |
| Ad-Sol Nissin | NA | 7.22% | 15.60% | ★★★★★★ |
| Chongqing Machinery & Electric | 18.92% | 8.43% | 26.16% | ★★★★★★ |
| Taiyo KagakuLtd | 0.68% | 6.49% | 11.88% | ★★★★★★ |
| Forth Smart Service | 44.85% | -3.80% | 10.19% | ★★★★★☆ |
| Shanghai Fudan Microelectronics Group | 16.49% | 9.29% | -6.62% | ★★★★★☆ |
| Sing Investments & Finance | 0.10% | 5.85% | 7.00% | ★★★★☆☆ |
| Shengda ResourcesLtd | 57.58% | 8.61% | 9.90% | ★★★☆☆☆ |
| Primo Global Holdings | 70.93% | 9.87% | 28.79% | ★★★☆☆☆ |
Below we spotlight a couple of our favorites from our exclusive screener.
Chongqing Machinery & Electric (SEHK:2722)
Simply Wall St Value Rating: ★★★★★★
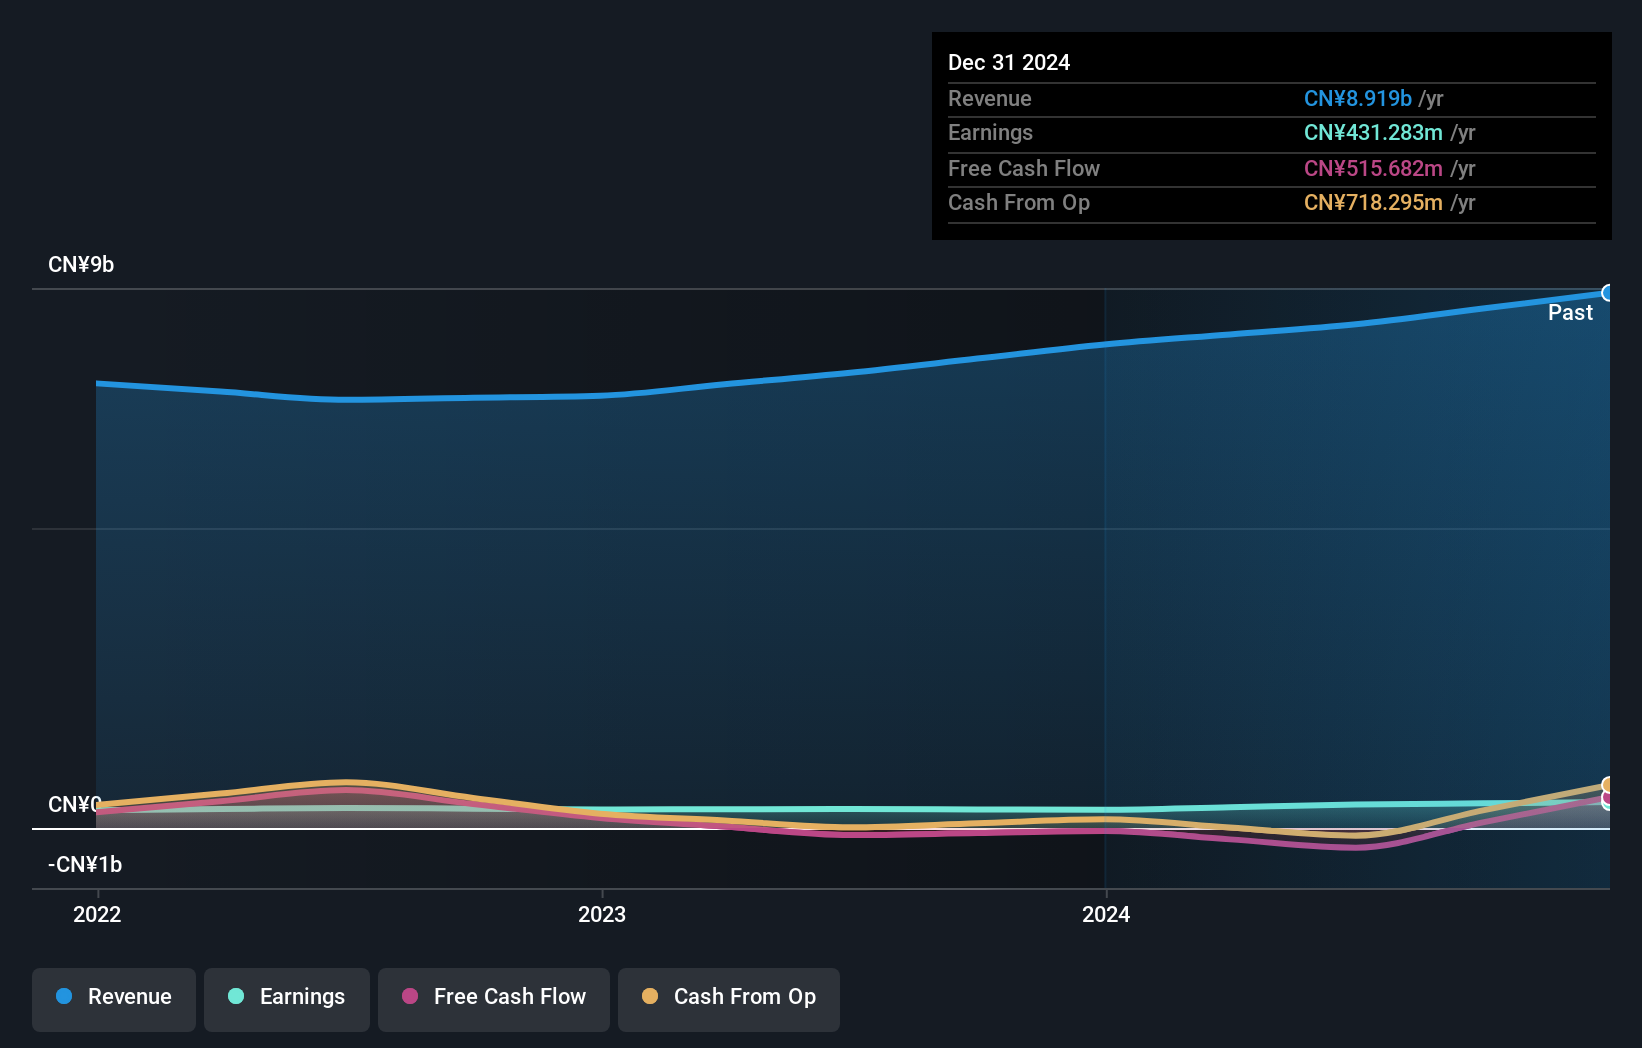
Overview: Chongqing Machinery & Electric Co., Ltd. engages in the design, manufacture, and sale of clean energy and high-end smart manufacturing equipment, with a market capitalization of HK$6.21 billion.
Operations: Chongqing Machinery & Electric generates revenue primarily from wind turbine blades (CN¥3.69 billion), wire and cable (CN¥2.56 billion), and general machinery (CN¥2.33 billion). The company also earns from CNC machine tools, intelligent manufacturing, and financial services, contributing to its diverse income streams.
Chongqing Machinery & Electric, a smaller player in the industrial sector, has shown promising growth with earnings surging 49.7% over the past year, outpacing the industry's 28.8%. The company is trading at an attractive value, around 91.8% below its estimated fair value. Recent financials reveal sales of CNY 5.36 billion for the first half of 2026 and net income reaching CNY 577 million, up from CNY 440 million in the previous period. With a proposed interim dividend and improved profitability in its smart machine tools business, Chongqing seems poised for continued expansion in key areas like wind power blades and high-horsepower engines.
Systena (TSE:2317)
Simply Wall St Value Rating: ★★★★★★
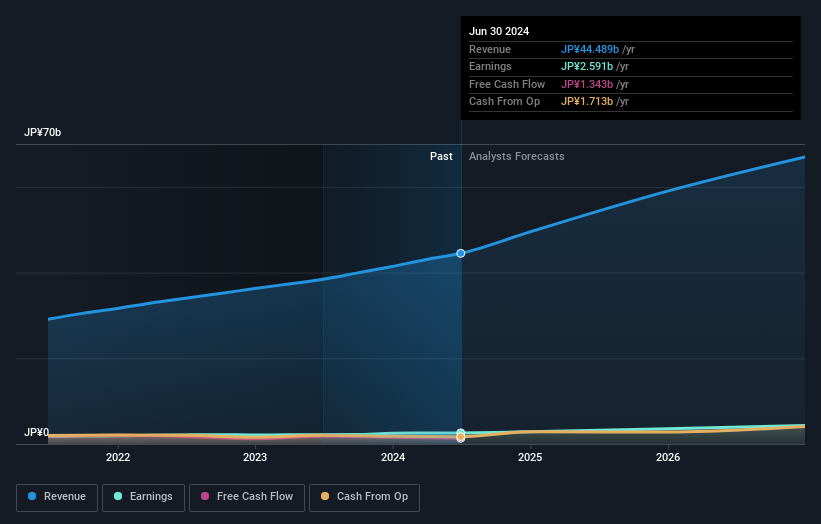
Overview: Systena Corporation operates in Japan, focusing on solution and framework design, IT services, business solutions, and cloud businesses with a market cap of ¥156.21 billion.
Operations: Systena generates revenue through its solution and framework design, IT services, business solutions, and cloud businesses. The company has a market cap of ¥156.21 billion.
Systena, a nimble player in the tech sector, has shown impressive earnings growth of 23.1% over the past year, outpacing the broader software industry at 13.3%. The company is trading at a compelling 34.6% below its estimated fair value, suggesting potential upside for investors. With a debt-to-equity ratio reduced from 5.9% to 4% over five years and more cash than debt on its books, financial stability seems solid. Recent leadership changes could steer strategic initiatives effectively as they prepare to announce Q1 results for fiscal year 2027 on July 30th, offering further insights into future performance prospects.
- Get an in-depth perspective on Systena's performance by reading our health report here.
Assess Systena's past performance with our detailed historical performance reports.

Elan (TSE:6099)
Simply Wall St Value Rating: ★★★★★☆
Overview: Elan Corporation operates in the nursing care sector mainly in Japan and has a market capitalization of approximately ¥44.22 billion.
Operations: Elan generates revenue primarily from its nursing care services in Japan. The company's market capitalization stands at approximately ¥44.22 billion.
Elan, an emerging player in the healthcare sector, is making waves with its robust earnings growth of 30.9% over the past year, outpacing the industry average of 3.9%. Trading at a significant discount of 30.1% below its estimated fair value, Elan offers a compelling investment case. The company boasts a strong financial position with cash exceeding total debt and interest payments well covered by EBIT at an impressive 4789 times coverage. Despite a slight increase in its debt-to-equity ratio to 4.6% over five years, Elan's high-quality earnings and positive free cash flow underscore its potential for sustained growth.
- Delve into the full analysis health report here for a deeper understanding of Elan.
Review our historical performance report to gain insights into Elan's's past performance.
Summing It All Up
- Click here to access our complete index of 113 Asian Undiscovered Gems With Strong Fundamentals.
- Hold shares in these firms? Setup your portfolio in Simply Wall St to seamlessly track your investments and receive personalized updates on your portfolio's performance.
- Invest smarter with the free Simply Wall St app providing detailed insights into every stock market around the globe.
Want To Explore Some Alternatives?
- Explore high-performing small cap companies that haven't yet garnered significant analyst attention.
- Fuel your portfolio with companies showing strong growth potential, backed by optimistic outlooks both from analysts and management.
- Find companies with promising cash flow potential yet trading below their fair value.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com