


Top Asian Growth Stocks With Strong Insider Backing
As Asian markets navigate a complex landscape of fluctuating oil prices and evolving geopolitical tensions, investors are increasingly focused on identifying opportunities that align with growth potential and solid backing. In this environment, companies with high insider ownership stand out as they often signal confidence in the firm's future prospects, making them appealing choices for those seeking robust growth stocks in Asia.
Top 10 Growth Companies With High Insider Ownership In Asia
| Name | Insider Ownership | Earnings Growth |
| Suzhou Dongshan Precision Manufacturing (SZSE:002384) | 33.5% | 74.9% |
| Seojin SystemLtd (KOSDAQ:A178320) | 18% | 112.1% |
| SEERS (KOSDAQ:A458870) | 33.8% | 37.8% |
| Meiko Electronics (TSE:6787) | 19.2% | 33.8% |
| Jiangxi Fushine Pharmaceutical (SZSE:300497) | 21.1% | 50.8% |
| HUMAN MADE (TSE:456A) | 23.9% | 29.8% |
| Great Microwave Technology (SHSE:688270) | 21.1% | 95.2% |
| Gold Circuit Electronics (TWSE:2368) | 29.8% | 43.6% |
| Fulin Precision (SZSE:300432) | 11.2% | 66.5% |
| Biocytogen Pharmaceuticals (Beijing) (SEHK:2315) | 14.1% | 39.2% |
Here we highlight a subset of our preferred stocks from the screener.
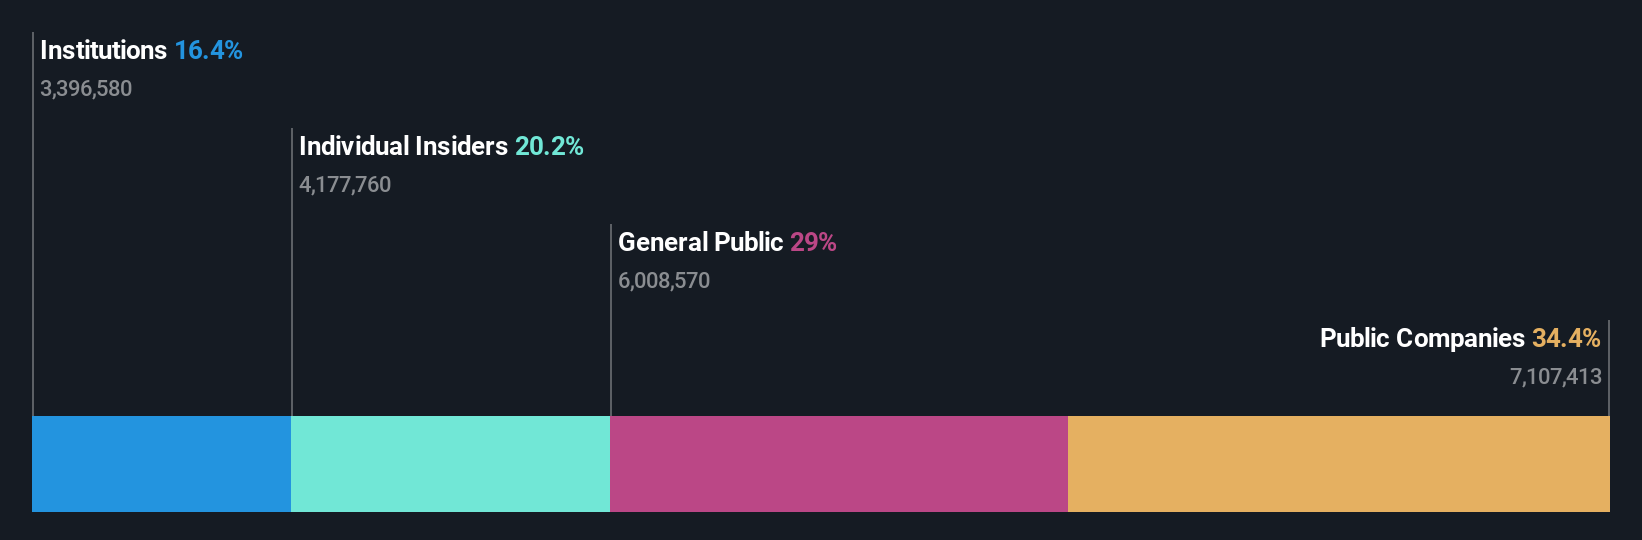
KCTech (KOSE:A281820)
Simply Wall St Growth Rating: ★★★★★★
Overview: KCTech Co., Ltd. is a South Korean company involved in the manufacture and distribution of semiconductor systems, display systems, and electronic materials, with a market cap of ₩1.71 trillion.
Operations: Revenue Segments (in millions of ₩): Semiconductor systems contribute ₩1,200,000, display systems account for ₩800,000, and electronic materials generate ₩500,000.
Insider Ownership: 20.6%
Revenue Growth Forecast: 25.2% p.a.
KCTech is poised for substantial growth with earnings projected to rise significantly at 31.6% annually over the next three years, outpacing the KR market. Revenue is also expected to grow robustly at 25.2% per year, surpassing market averages. Despite a highly volatile share price and limited financial data, KCTech offers high-quality earnings and trades at a significant discount below its estimated fair value, presenting potential opportunities for investors focused on growth companies in Asia.
- Click here to discover the nuances of KCTech with our detailed analytical future growth report.
- Upon reviewing our latest valuation report, KCTech's share price might be too pessimistic.
SenseTime Group (SEHK:20)
Simply Wall St Growth Rating: ★★★★★☆
Overview: SenseTime Group Inc. is an investment holding company that researches, develops, and sells artificial intelligence software platforms in Mainland China, Northeast Asia, Southeast Asia, and internationally with a market cap of HK$54.88 billion.
Operations: The company's revenue segments include Smart Business at CN¥1.99 billion, Smart City at CN¥1.89 billion, Smart Life at CN¥1.11 billion, and Smart Auto at CN¥0.13 billion.
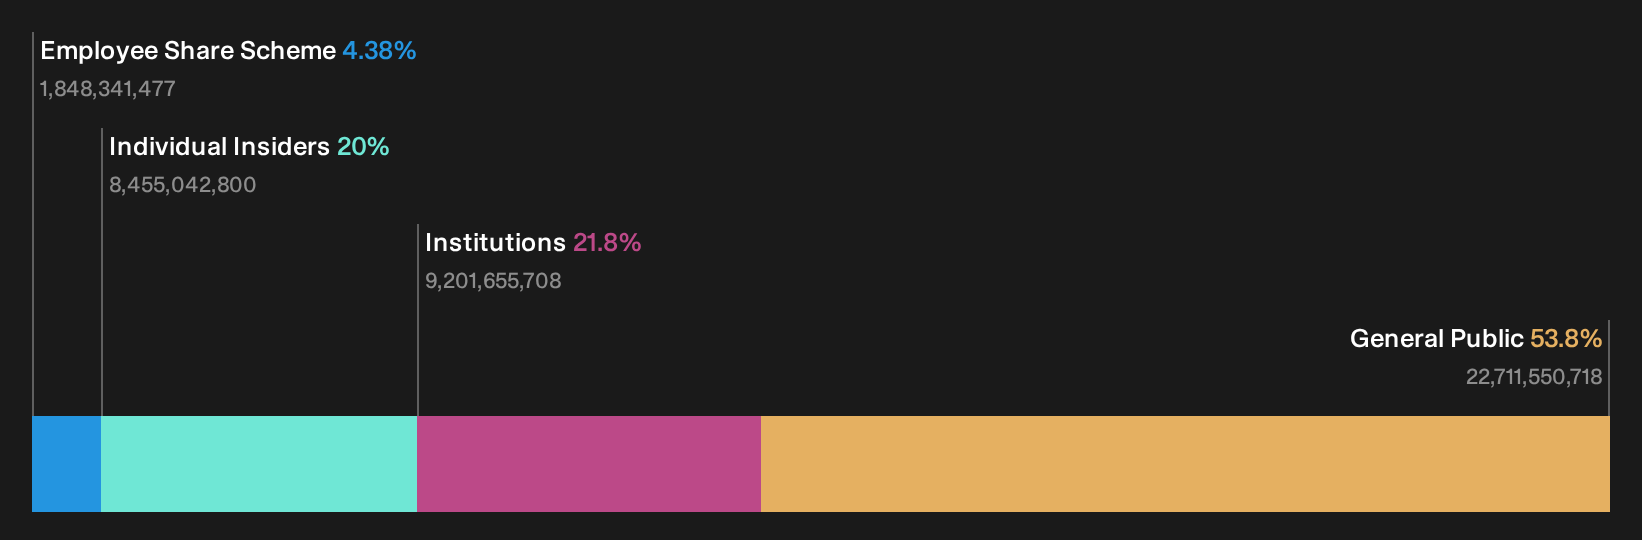
Insider Ownership: 20%
Revenue Growth Forecast: 23.8% p.a.
SenseTime Group demonstrates strong growth potential with its recent return to profitability, reporting a net income of CNY 607.42 million for H1 2026, compared to a loss last year. The company's revenue is forecasted to grow at 23.8% annually, outpacing the Hong Kong market. Analysts agree on a significant price appreciation potential of 66.1%. However, despite high revenue growth expectations, its forecasted Return on Equity remains low at 0.2% in three years.
- Click to explore a detailed breakdown of our findings in SenseTime Group's earnings growth report.
- Our comprehensive valuation report raises the possibility that SenseTime Group is priced higher than what may be justified by its financials.
ACES Electronics (TWSE:3605)
Simply Wall St Growth Rating: ★★★★★☆
Overview: ACES Electronics Co., Ltd. is engaged in the research, development, manufacture, and sale of electronic connectors across Taiwan, China, the Philippines, the United States, and internationally with a market cap of NT$32.06 billion.
Operations: The company's revenue is primarily derived from its Connector Department, which contributes NT$7.28 billion, followed by the Cables Segment at NT$2.71 billion and the Metal Stamping Department at NT$2.02 billion.
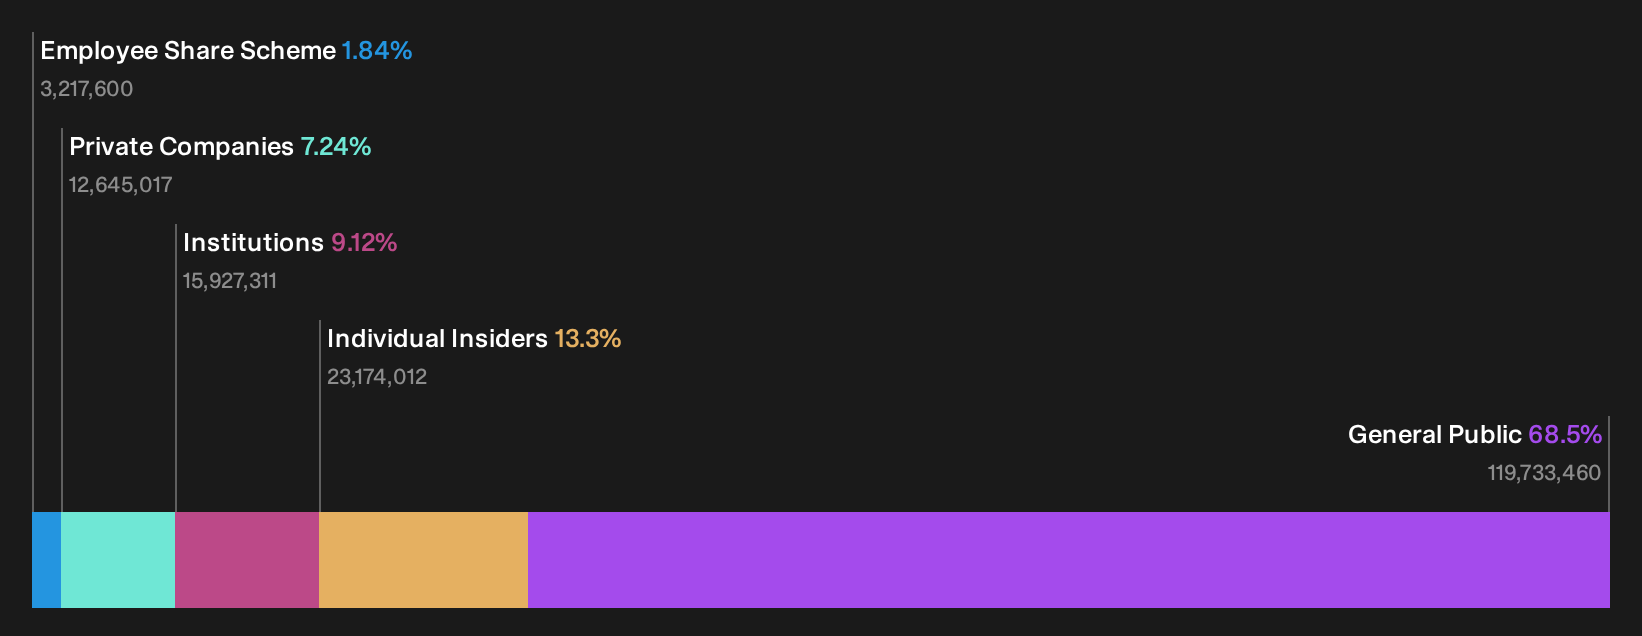
Insider Ownership: 13.3%
Revenue Growth Forecast: 23% p.a.
ACES Electronics shows strong growth potential with forecasted annual earnings growth of 47.73%, significantly outpacing the TW market. Despite recent shareholder dilution, its stock trades at 33% below estimated fair value. Recent results reveal substantial revenue and net income increases, with Q2 revenue rising to TWD 3.35 billion from TWD 2.79 billion a year ago, and net income doubling to TWD 200.77 million, indicating robust operational performance amidst high insider ownership dynamics in Asia.
- Click here and access our complete growth analysis report to understand the dynamics of ACES Electronics.
- Our valuation report unveils the possibility ACES Electronics' shares may be trading at a premium.
Summing It All Up
- Navigate through the entire inventory of 490 Fast Growing Asian Companies With High Insider Ownership here.
- Contemplating Other Strategies? The best AI stocks today may lie beyond giants like Nvidia and Microsoft. Find the next big opportunity with these 19 smaller AI-focused companies with strong growth potential through early-stage innovation in machine learning, automation, and data intelligence that could fund your retirement.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.The analysis only considers stock directly held by insiders. It does not include indirectly owned stock through other vehicles such as corporate and/or trust entities. All forecast revenue and earnings growth rates quoted are in terms of annualised (per annum) growth rates over 1-3 years.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com