


Will Drone Delivery Pilot Change Lowe's (LOW) Narrative
- Lowe's Companies has launched a drone delivery pilot with Wing and DoorDash from its Matthews, N.C. store. The service offers selected tools, paint supplies and everyday essentials of up to about 2.5 pounds for delivery in as fast as 20 minutes.
- The drone service extends Lowe's same day fulfillment toolkit, which already includes in store pickup, curbside and same day delivery. It targets a practical pain point for DIY and Pro customers whose projects can stall when small but essential items are forgotten.
- We will now assess how Lowe's push into rapid drone delivery could influence the broader investment narrative around its omnichannel focus.
Lowe's Companies Investment Narrative Recap
To own Lowe's Companies, investors need to believe the retailer can turn its larger exposure to Pro customers, construction markets and digital channels into steadier earnings, even while management guides to roughly flat 2026 comparable sales near US$92b. The drone pilot fits that omnichannel push, but given its narrow product range and weight limits, it does not change the near term story on its own.
The near term swing factor still sits in execution around margins, integration of FBM and ADG, and progress on debt reduction in a period of softer big ticket demand. The main risk is that housing turnover and large project activity stay muted longer, which would keep pressure on operating margin guidance already set at the low end of the range.
The most relevant recent update alongside drone delivery is management’s commentary on tuck in acquisitions at the Goldman Sachs Consumer and Retail Conference. Lowe's Companies is signaling interest in deals that fit within its existing model, while stressing discipline given a strong balance sheet and the risk of an overly complex portfolio.
For shareholders, that matters because integration of FBM and ADG is already a key execution test, with leverage elevated and margin pressure linked to these acquisitions. Any new transaction, even a smaller one, will feed into the same debate around capital allocation, earnings quality and whether Lowe's can convert a wider addressable market into durable, higher quality cash flows.
Lowe's Companies' narrative projects US$99.5b revenue and US$7.8b earnings by 2029. This incorporates forecast yearly revenue growth of 3.2% and an earnings increase of about US$1.2b from US$6.6b today.
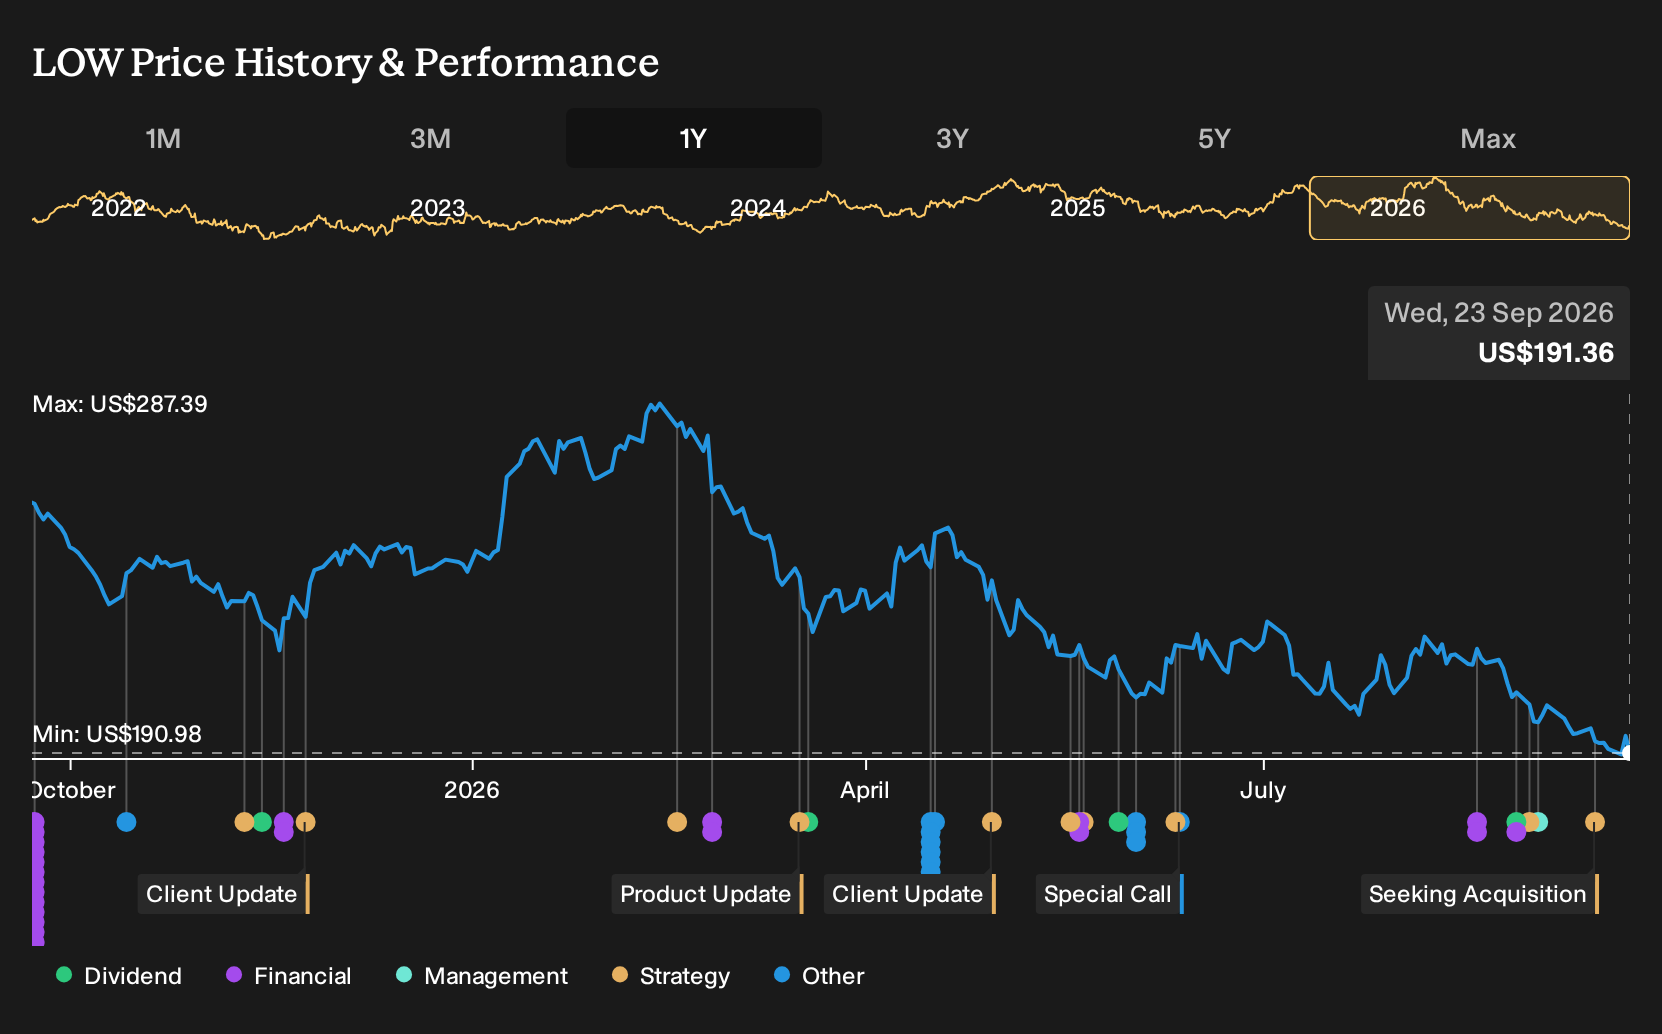
Uncover why Lowe's Companies' fair value indicates a 32% potential upside to its current price, which could narrow quickly.
Exploring Other Perspectives
The Simply Wall St Community currently supplies three fair value views on Lowe's Companies, clustering between US$230.13 and US$252.30. That tight band contrasts with recent option activity and earnings estimate revisions that point to caution. With drone delivery pilots and tuck in acquisitions on the table, you can see how widely opinions can differ. Explore the full spread of viewpoints before you decide where you stand.
Explore 2 other Lowe's Companies fair value estimates, including one that suggests it could be worth just $230.13!
Decide For Yourself
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd. Trust your own analysis and judgment.
- A great starting point for your Lowe's Companies research is our analysis highlighting 5 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for Lowe's Companies. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Lowe's Companies' overall financial health at a glance.
Looking For More Ideas Beyond Lowe's Companies?
If the Lowe's Companies story has sharpened your thinking on what you want from a business, use that momentum to widen your opportunity set with the Simply Wall St Screener. Filter for the traits that matter most to you and let the data do the heavy lifting.
- Prefer strong balance sheets and durable fundamentals over drama? Start by scanning a list of solid balance sheet and fundamentals (23 results) that can help anchor the core of your portfolio.
- If potential mispricing is what interests you, hunt through a 30 high quality undervalued stocks and see which businesses look priced for pessimism.
- For investors who value consistent income, check out a 7 dividend fortresses that might complement a holdings list built around names like Lowe's Companies.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com