


Healthpeak Properties (DOC) Could Be 11% Below Fair Value On Raised 2026 Guidance
Healthpeak Properties (DOC) drew fresh attention after raising its 2026 adjusted FFO guidance and lifting its same-store cash adjusted NOI outlook following Q2 results, prompting investors to reassess the healthcare REIT’s positioning.
Recent trading tells a mixed story. Healthpeak Properties’ share price has climbed 26.42% year to date despite a weaker 30 day move that left the stock down 5.32%. The 1 year total shareholder return of 17.32% and 3 year total shareholder return of 37.74% suggest longer term holders have seen steadier gains, even after a 5 year total shareholder return decline of 19.98% that still weighs on the bigger picture.
Scan how Healthpeak Properties stacks up against other income-focused real estate plays by reviewing the hand-picked 7 dividend fortresses.
Healthpeak Properties now trades with a strong year to date gain but a softer recent patch, raising a simple question: Are investors reacting to sturdier fundamentals or just swinging with changing sentiment ahead of any valuation work?
Most Popular Narrative: 11% Undervalued
Healthpeak Properties closed at $20.48, versus a widely followed fair value estimate of $23.05, so the valuation conversation hinges on whether its cash flows justify that gap.
The accelerating shift of surgical and specialty care from inpatient hospital settings to outpatient centers, supported by anticipated regulatory changes (CMS inpatient-only default reversal), is set to drive sustained tenant demand and pricing power for Healthpeak's modern, high-acuity outpatient medical buildings, which should translate into increased occupancy rates and same-store NOI growth.
See why 33 investors see Healthpeak Properties as 11% undervalued.
Result: Fair Value of $23.05 (UNDERVALUED)
Still, the Healthpeak Properties story can be knocked off course if tenant credit issues in the lab portfolio deepen or if capital markets stay tight and refinancing costs bite harder.
Find out about the key risks to this Healthpeak Properties narrative.
Another View: Market Pricing For Healthpeak Properties
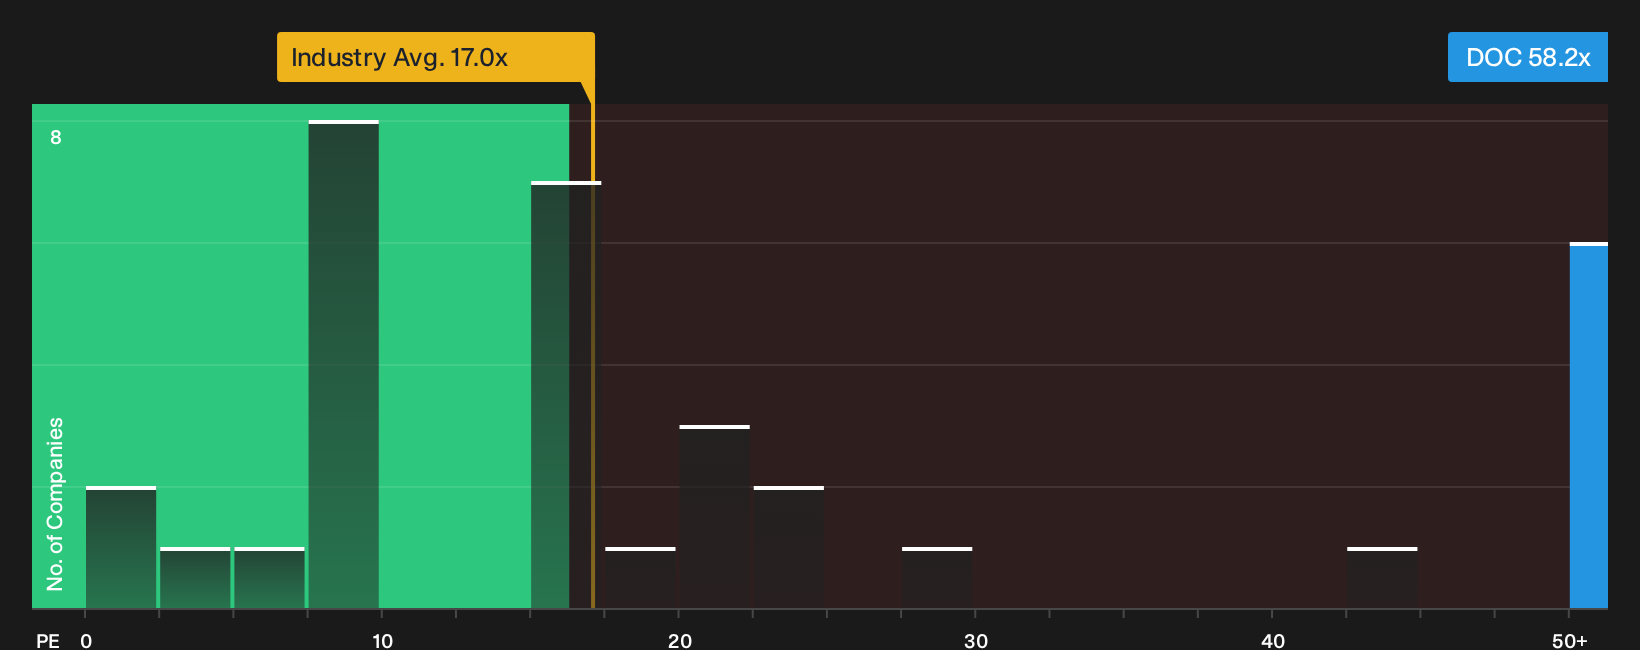
While the narrative fair value for Healthpeak Properties points to an 11% discount, the market is assigning a very different message through simple earnings multiples. The stock trades on a P/E of 58.2x, compared with a fair ratio of 22.8x and a global Health Care REITs average of 17x.
That gap suggests investors are paying a heavy premium relative to both the industry and where the fair ratio implies the market could move over time. The key question is whether this reflects durable quality or simply leaves less room for error.
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed signals on Healthpeak Properties can be confusing, so treat this as a prompt to dig in quickly and stress test your own thesis. Weigh the upside against the threats by reviewing the 2 key rewards and 4 important warning signs.
Looking for more investment ideas beyond Healthpeak Properties?
If Healthpeak Properties has you rethinking your portfolio, now is the moment to line up a few fresh ideas before the next round of moves catches you off guard.
- Spot potential overachievers early by scanning the 16 high quality undiscovered gems that combine solid fundamentals with room for the story to grow.
- Strengthen your defensive side by checking the 31 resilient stocks with low risk scores designed to highlight resilient businesses with more measured risk profiles.
- Tighten your focus on financial resilience by reviewing the list of solid balance sheet and fundamentals (23 results) and see which companies pair robust finances with healthier fundamentals.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com