


How Investors May Respond To Intuitive Surgical (ISRG) New Europe Surgery Approval
- Intuitive Surgical recently received CE mark approval for using its da Vinci SP single port system in transvaginal gynecologic procedures, adding a new natural orifice indication to its existing European approvals across multiple endoscopic and soft tissue surgeries.
- This new indication broadens the clinical use of da Vinci SP in Europe. It can influence procedure mix, hospital adoption decisions, and the durability of Intuitive Surgical’s recurring instrument, accessory, and service revenue streams.
- We will look at how Intuitive Surgical’s investment narrative is affected by expanded European SP indications for transvaginal gynecologic surgery.
Scan other robotics and automation leaders riding similar procedure trends with our curated list of 93 robotics and automation stocks as hospitals lean further into minimally invasive platforms such as Intuitive Surgical's da Vinci SP.
Intuitive Surgical Investment Narrative Recap
Owning Intuitive Surgical means believing robotic assisted and minimally invasive procedures keep gaining share across multiple specialties, and that higher utilization of the da Vinci and Ion platforms supports recurring instruments and services revenue. The transvaginal CE mark fits that story by broadening da Vinci SP procedures in Europe, although by itself it is not a major shift in the near term.
Over the next few quarters, the key catalyst still looks like sustained global procedure growth on existing systems alongside broader adoption outside the US. The biggest risk remains pressure in markets such as China and parts of Europe, where tighter hospital budgets, local competitors and pricing policies could temper new system placements.
The most relevant recent context is the reported 16% worldwide procedure growth in Q2 2026, with 38% of da Vinci procedures performed outside the US. That operating backdrop helps frame the new CE mark for transvaginal gynecologic use as another way for Intuitive Surgical to deepen usage on already installed SP systems in Europe.
For investors watching catalysts, the mix of higher growth regions such as India, Italy and Germany and a fuller SP procedure portfolio, now including transvaginal access, provides additional levers for volume. Execution risk centers on whether hospitals adopt these new indications at scale while competitors, including large new soft tissue platforms, increase pressure on pricing and capital decisions.
Intuitive Surgical Forecasts Behind The Expanded SP Story
Intuitive Surgical's long term story that sits behind the new European SP indication is already mapped out in analyst models. Those forecasts focus on revenue expectations, earnings projections and the valuation multiples investors are being asked to accept by 2029.
Analysts currently factor in revenue growth of 11.9% per year over the next 3 years. Current earnings sit at about US$3.1b, and consensus points to earnings of US$4.8b by 2029. That implies an earnings increase of roughly US$1.7b from today.
On those same assumptions, the analyst framework uses 2029 as the key forecast year. Consensus expects revenues of US$15.5b and earnings of US$4.8b in that period, with the stock trading on a P/E ratio of 43.5x that year, compared with 44.3x today and 24.8x for the wider US medical equipment group.
Intuitive Surgical's narrative projects US$15.5b revenue and US$4.8b earnings by 2029. This requires 11.9% yearly revenue growth and an earnings increase of roughly US$1.7b from current earnings of about US$3.1b.
Uncover why Intuitive Surgical's fair value indicates a 20% potential upside to its current price, which could narrow quickly.
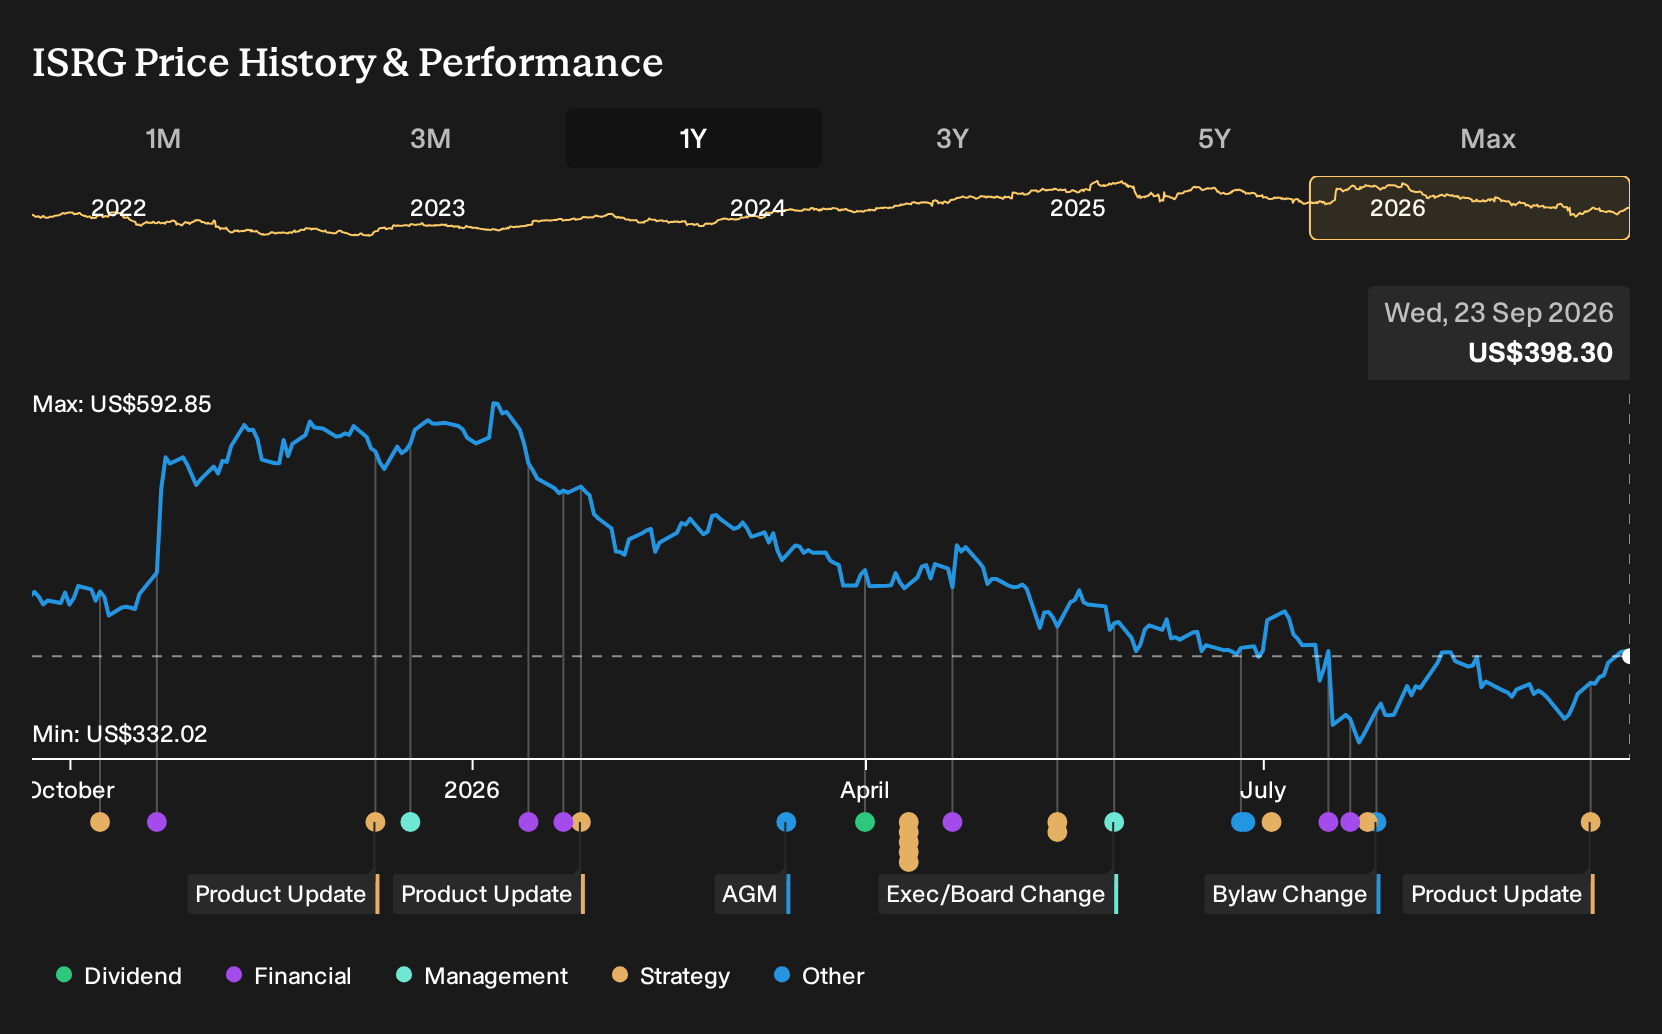
Exploring Other Perspectives
One bullish twist on the Intuitive Surgical story focuses on faster da Vinci 5 upgrades and digital tools. The most optimistic analysts already pencilled in about US$17.2b in 2029 revenue and US$4.9b in earnings before this CE mark. You now get to ask whether transvaginal SP approvals push their upbeat scenario even further or force a rethink.
Explore 9 other Intuitive Surgical fair value estimates, including one that suggests as much as 58% upside from the current price.
The Verdict Is Yours
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your Intuitive Surgical research is our analysis highlighting 3 key rewards that could impact your investment decision.
- See our latest analysis for Intuitive Surgical. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Intuitive Surgical's overall financial health at a glance.
Looking For More Ideas Beyond Intuitive Surgical?
If the Intuitive Surgical story has sharpened your thinking about procedure growth and recurring revenue, use that same lens to filter other opportunities with the Simply Wall St Screener.
- For investors who want potential upside without sacrificing quality, scan a curated set of 16 high quality undiscovered gems that combine strong fundamentals with lower market attention.
- If capital preservation and steadier profiles matter more to you, focus on companies screened for resilience through our 31 resilient stocks with low risk scores to see which businesses line up with that approach.
- For readers who care about balance sheet strength first, start with a list of solid balance sheet and fundamentals (23 results) and then narrow down to the sectors and themes that fit your own checklist.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com