


Is Terex (TEX) Cheap Or Pricey On Conference Day?
Terex (TEX) is set to present at Morgan Stanley's 14th Annual Laguna Conference on September 15, 2026, giving investors fresh commentary on the industrial equipment maker's operations and the backdrop for its US$6.7b business.
Terex comes into this conference after a difficult few months for the share price, which is down 21.95% over 90 days and 11.64% over 30 days. However, the 1-year total shareholder return of 13.74% and 5-year total shareholder return of 43.82% show a longer track record that still reflects gains for investors.
Scan for other industrial players with similar conference catalysts by running the hand picked 39 power grid technology and infrastructure stocks.
Bulls see Terex’s recent share price drop as a rare entry point into a US$6.7b industrial platform. Bears see a value trap forming. Which story do the current valuation signals support?
Most Popular Narrative: 27% Undervalued
Terex is trading at $58.21, while the most followed narrative pegs fair value at about $79.46 using a 9.18% discount rate, so the debate is whether current pricing reflects temporary pressure or a deeper reset in expectations.
The company's acceleration of electrified and digital product offerings (Environmental Solutions growth, expansion of 3rd Eye telematics and SaaS subscriptions) is unlocking higher-margin, recurring revenues and enabling Terex to benefit from stricter sustainability and efficiency regulations, which is supporting margin expansion and differentiated pricing for next-generation equipment.
See why 12 investors see Terex as 27% undervalued.
Result: Fair Value of $79.46 (UNDERVALUED)
Still, the narrative can crack if high interest rates keep rental customers on the sidelines, or if tariff driven cost pressure squeezes Terex segment margins harder.
Find out about the key risks to this Terex narrative.
Another View On Terex Valuation
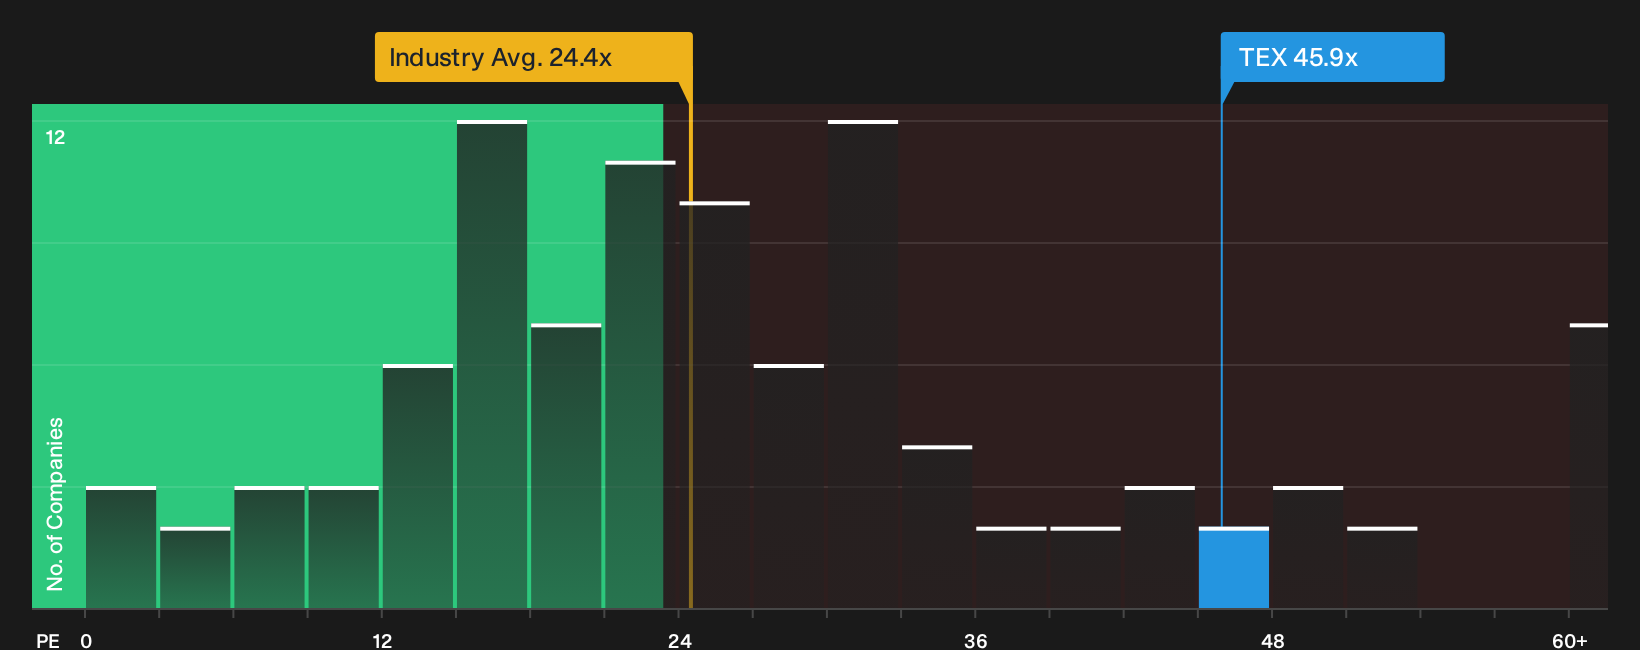
The fair value narrative for Terex leans heavily on future cash flows and discount rates. The market today is using a much simpler yardstick. At a P/E of 45.9x, the stock trades at a clear premium to both the US Machinery sector on 24.6x and its peer average on 18.5x. Even though the fair ratio sits higher at 62.4x, this raises a blunt question for investors: Is this current premium a margin of safety or a pricing risk if sentiment cools?
For a closer look at how that earnings multiple compares with the wider market and the fair ratio the market could move toward, See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed messages around Terex can be useful if you turn them into your own checklist and move quickly while sentiment is still this divided. To see both sides clearly in one place, start with the 3 key rewards and 3 important warning signs.
Looking for more Terex investment ideas?
If Terex has you thinking harder about where to put fresh capital next, do not stop at a single ticker. Use data driven stock lists to stress test your thinking and widen your opportunity set before the next move.
- Target potential bargains that pair resilient cash flows with quality fundamentals by scanning the 30 high quality undervalued stocks.
- Prioritise durability over drama by reviewing a 31 resilient stocks with low risk scores that focuses on businesses with stronger risk scores.
- Hunt for future leaders hiding in plain sight by working through a 16 high quality undiscovered gems that filters for underfollowed companies with solid numbers.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com