


Noble (NE) Could Be 7% Undervalued On Offshore Demand Optimism
Noble (NE) continues to attract attention as an offshore drilling contractor with a market value of about US$7.2b, following recent share price moves that have included gains over the past 3 months.
Recent trading has cooled slightly, with a 1-day share price return that declined 0.93% and a 30-day share price return down 2.96%. However, Noble’s 90-day share price return of 13.91% and year-to-date share price return of 53.86% point to momentum that has been strong overall. This is echoed by a 1-year total shareholder return of 59.87% and a 5-year total shareholder return of 94.60%.
Compare Noble's recent momentum with a hand picked group of energy names by scanning the 30 high quality undervalued stocks that combine strong balance sheets with solid cash generation.
After that kind of run, some investors will see Noble’s pullback as a fresh entry point, while others worry the easy money is gone. Does the current price still offer an appealing tradeoff between risk and reward?
Most Popular Narrative: 7% Undervalued
Noble’s most followed narrative pegs fair value at about $48.09, a touch above the latest close of $44.62, which points to modest upside if those assumptions play out.
Large offshore project pipelines in South America (notably Brazil), West Africa, and other regions are set to drive a rebound in ultra-deepwater drilling activity by late 2026 to 2027, driven by global energy demand growth. This is expected to support higher rig utilization and dayrates, which could in turn increase Noble's future revenue and EBITDA.
Persistent reliance on hydrocarbons amid a slow transition to renewables, together with intensified focus on energy security by major economies, supports sustained offshore investment. This is expected to help maintain medium to long-term demand for Noble's services, with a positive impact on revenue visibility and backlog.
See why 70 investors see Noble as 7% undervalued.
Result: Fair Value of $48.09 (UNDERVALUED)
Still, the Noble narrative could be challenged if offshore demand remains soft and rig oversupply keeps day rates under pressure for longer than analysts currently factor in.
Find out about the key risks to this Noble narrative.
Another View on Noble’s Valuation
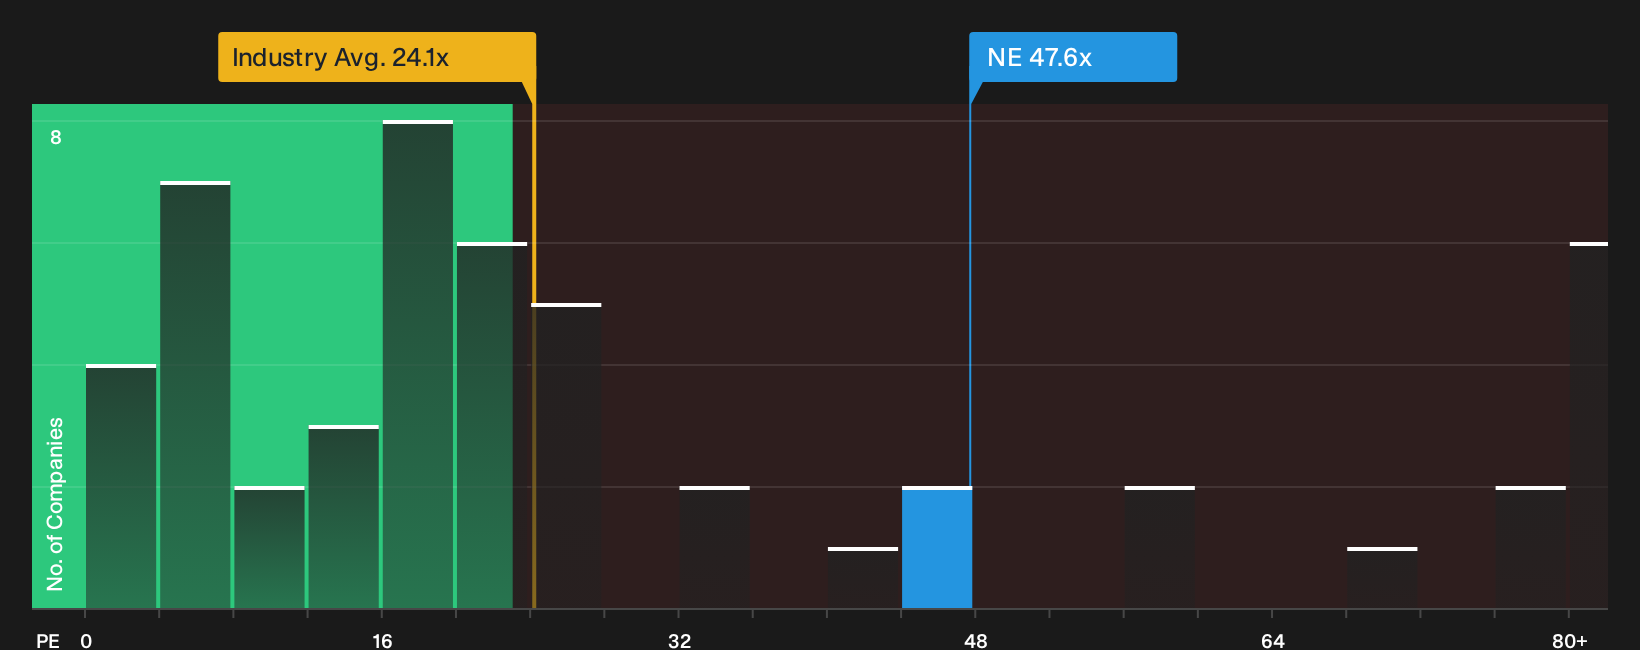
While the popular Noble narrative leans on fair value around $48 based on future earnings assumptions, the current P/E of 47.6x paints a different picture. That multiple is higher than both the US Energy Services sector at 23.8x and close peers at 29.4x, which suggests limited room for error if expectations slip.
The fair ratio for Noble is 52.9x, only slightly above where it trades today, so much of that potential rerating already appears reflected in the price. The question for investors is whether earnings can grow fast enough to justify paying nearly double the sector multiple, or whether patience is better rewarded elsewhere.
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
With Noble showing both optimism around potential rewards and unease about specific risks, it may be prudent to move quickly and inspect the details yourself. To evaluate both perspectives clearly, review the 2 key rewards and 2 important warning signs.
Looking for more investment ideas beyond Noble?
If Noble has sharpened your focus, do not stop here. Broaden your watchlist by scanning other opportunities that match your risk tolerance and return goals.
- Target income-first opportunities by reviewing companies in the 7 dividend fortresses that may suit investors who prioritize cash payouts.
- Hunt for resilient balance sheets through the list of solid balance sheet and fundamentals (23 results), where financial strength and fundamentals take center stage.
- Spot potential early movers by checking the 16 high quality undiscovered gems before they attract wider market attention.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com