


3 Japanese Undervalued Stocks Trading Up To 40% Below Fair Value
Global bond yields recently moved toward 4%, with Japan’s 10-year government bond yield reaching its highest level since 1996 as investors reassess the price of money. Higher discount rates can pressure lofty valuations, yet cash rich Japanese companies trading below estimated fair value may attract patient buyers. This article explores three such Japan undervalued cash flow stocks from our screener that could merit a closer look.
The three stocks covered below are just a small sample, with the wider screen surfacing 37 more Japanese companies where discounted cash flow estimates suggest similarly interesting stories that are not included here.
If you want to identify, analyze, and focus on the ideas that fit your own style, go straight to the Undervalued Stocks Based On Cash Flows screener.
Canon (TSE:7751)
Canon is a diversified Japanese industrial and imaging group that makes printers, cameras, semiconductor equipment, and a growing range of medical systems, where CT, MRI, digital radiography and healthcare IT contribute recurring cash flows from equipment, service and consumables. The business is sizable, with a market value of about ¥3.8t.
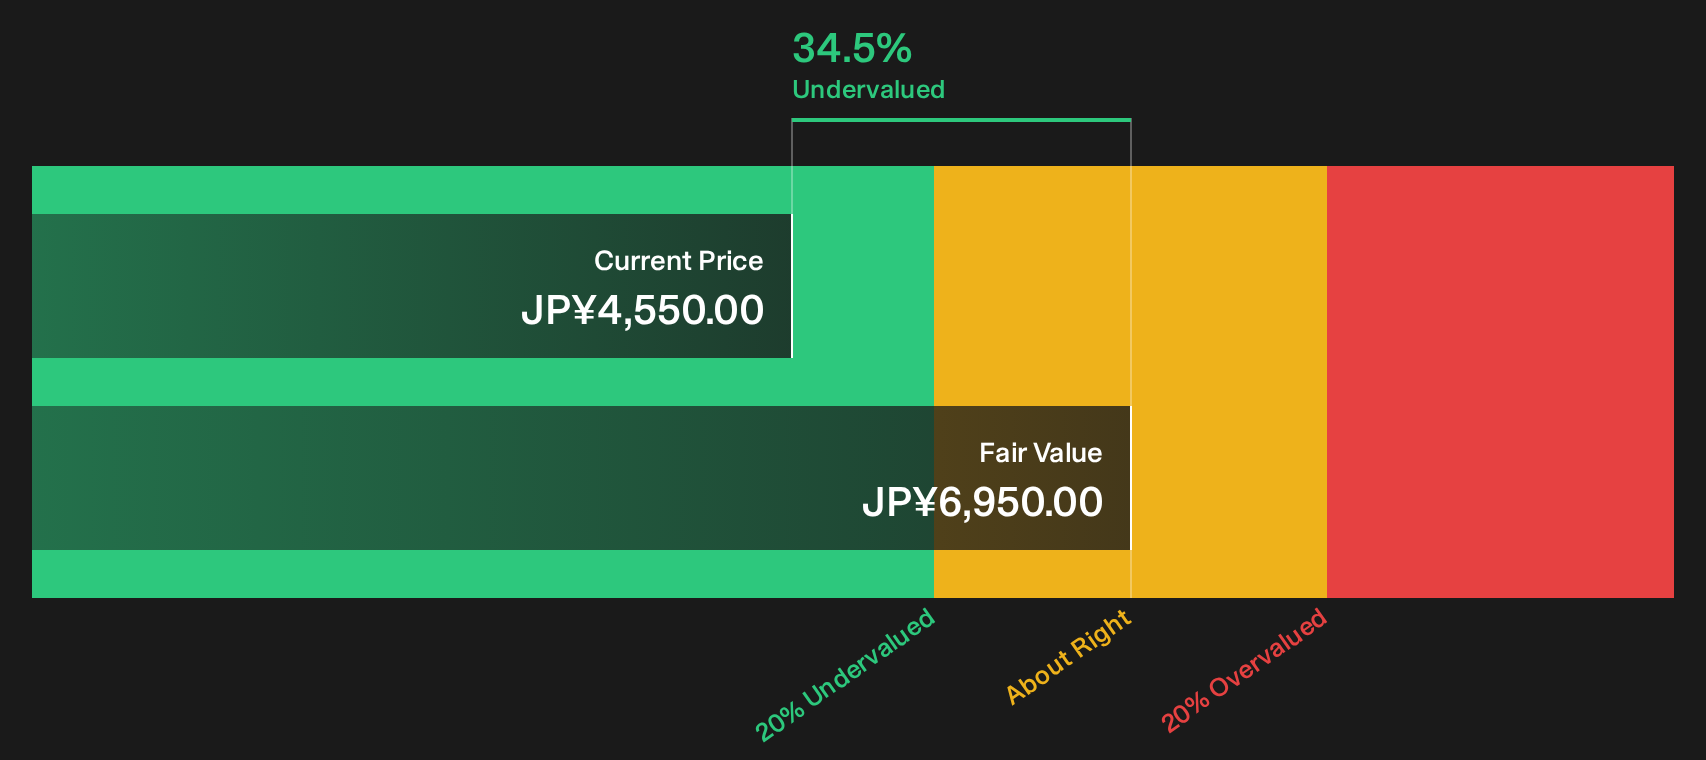
Canon appears in this cash-flow-focused screen because its medical segment generates repeat income from high-value scanners and IT contracts. The overall stock trades around 34.5% below an SWS DCF estimate of fair value at roughly 11.1x P/E. The appeal for value investors rests on whether that recurring medical cash engine fully translates into sustained earnings strength if a single key assumption breaks.
If that assumption matters to you, go straight to the 4 key rewards and 1 important warning sign for a clearer view of how Canon’s cash engine and risks line up.
Astellas Pharma (TSE:4503)
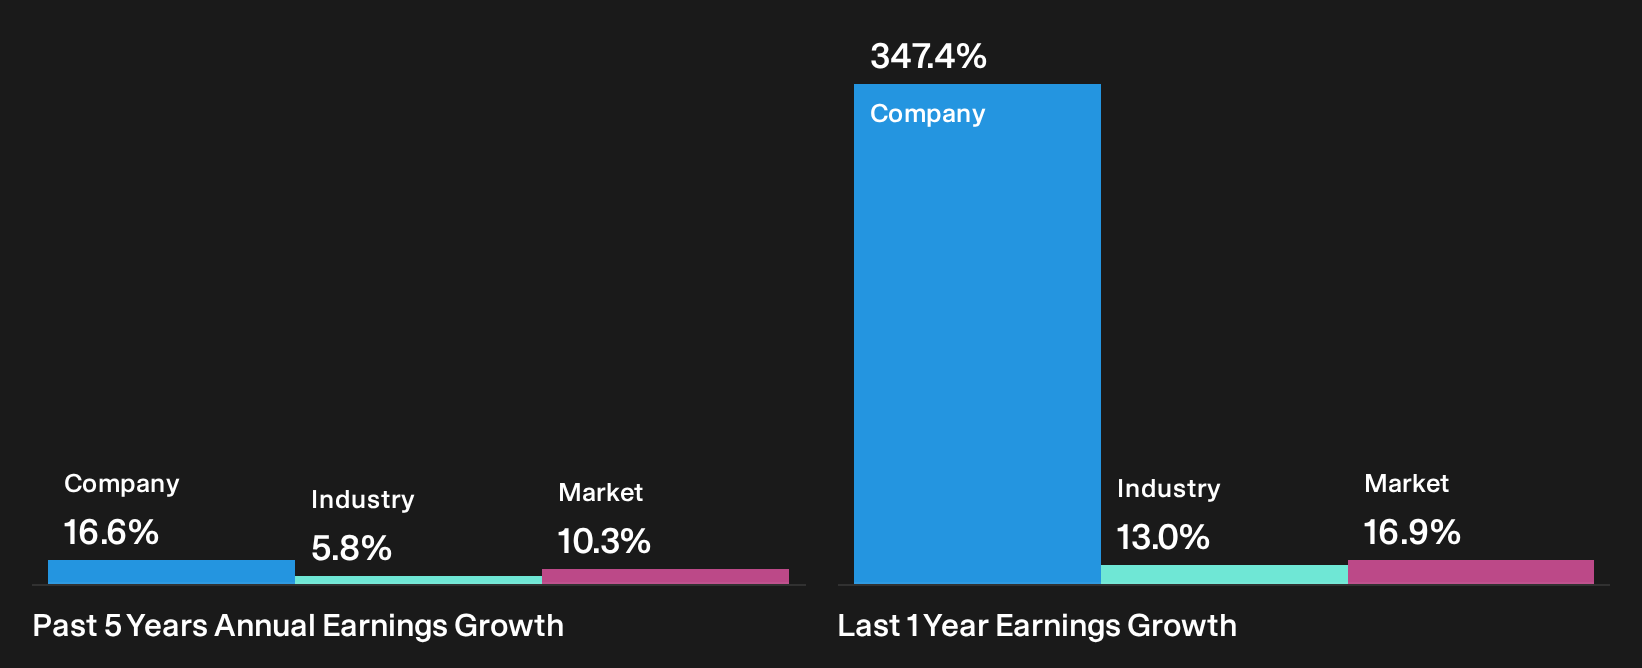
Astellas Pharma is a global drug maker focused on oncology and specialty medicines such as XTANDI, XOSPATA, PADCEV and VYLOY. Marketed therapies provide the recurring cash flows that link it to this cash flow screener, generating about ¥2.3t in pharmaceutical revenue on a roughly ¥4.3t market value.
For cash flow focused investors, Astellas Pharma is interesting because marketed oncology treatments already generate solid recurring income, while a large late stage pipeline could shape how durable those cash streams really are over the coming years.
"Patent expirations for key drugs such as XTANDI and mirabegron threaten to create substantial revenue and earnings losses as generic entrants erode Astellas' market share in critical therapeutic areas over the next several years."
What ultimately matters is how one less visible shift in the cash mix affects pricing power, profitability and trust in those long range forecasts.
That quiet shift is the real story behind Astellas Pharma’s cash mix, and the full narrative for Astellas Pharma shows how patent cliffs and new launches could be decoupling expectations.
Terumo (TSE:4543)
Terumo is a global medical equipment group. Its Cardiac and Vascular segment, which sells stents, catheters and other interventional devices, is central to its cash-flow-focused appeal, with that division producing about ¥706.7b of the ¥1.2t segment total and supporting a roughly ¥3.3t market value.
For investors tracking cash flow driven value, Terumo offers a mix of high margin cardiovascular hardware and recurring consumables that fits this screener’s focus on discounted cash streams. Recent operational progress in key regions provides additional context for how those future cash inflows might develop.
"Expansion of sales channels and volume commitments in China, especially in Neurovascular products, has enabled Terumo to gain market share and increase prices, counteracting typical negative VBP effects and positioning the company for future revenue growth in this key emerging market."
The real test for Terumo will come if a single unseen pressure on pricing power or product mix begins to chip away at those margins.
If that unseen pressure on Terumo’s pricing power has your attention, the full narrative for Terumo lays out how the current momentum could still accelerate from here.

Seeking Alternatives Before The Crowd?
Fresh ideas move fast. Breakout themes, shifting momentum, and stocks still flying under the radar for now can get caught quickly, so review these while it matters and consider your options in a timely way.
- Spot resilient businesses before headlines catch up by scanning the curated 21 resilient stocks with low risk scores that aim to keep portfolio swings contained while others chase every spike.
- Track structural trends in automation by following the hand picked 93 robotics and automation stocks that could benefit as factories, warehouses, and producers upgrade aging systems.
- Prepare for potential infrastructure tailwinds through the focused 39 power grid technology and infrastructure stocks that highlights companies tied to grid upgrades, reliability, and smarter energy networks.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com