


How Investors Are Reacting To PepsiCo (PEP) Electric Truck Order
- PepsiCo has moved on several fronts, including joining a 2,500 electric truck order with other shippers, expanding beverage distribution through The Great Greek Mediterranean Grill partnership, and advancing non sugar drinks and recyclable packaging while also closing a Cheverly, Maryland bottling plant.
- These actions highlight how PepsiCo is reworking its product mix and supply chain to address changing demand, regulatory pressure on packaging, and health focused consumer habits.
- We will look at how PepsiCo's investment narrative is shaped by its large scale electric truck commitment and broader portfolio shifts.
Scan how PepsiCo's mix of electric trucking, packaging shifts, and changing snack demand compares with other potential opportunities by starting with the 16 high quality undiscovered gems in this space.
What Is PepsiCo's Investment Narrative?
For PepsiCo to make sense in a portfolio, you need to be comfortable with a slow growing, cash generative consumer giant that relies on pricing power, a broad snack and beverage mix, and steady dividend income rather than rapid expansion. Recent moves speak to that reality. The 2,500 truck electric fleet commitment, paper bottle work, and the Cheverly plant closure all tie back to capital heavy supply chain and packaging adjustments that aim to keep margins intact while unit volumes come under pressure.
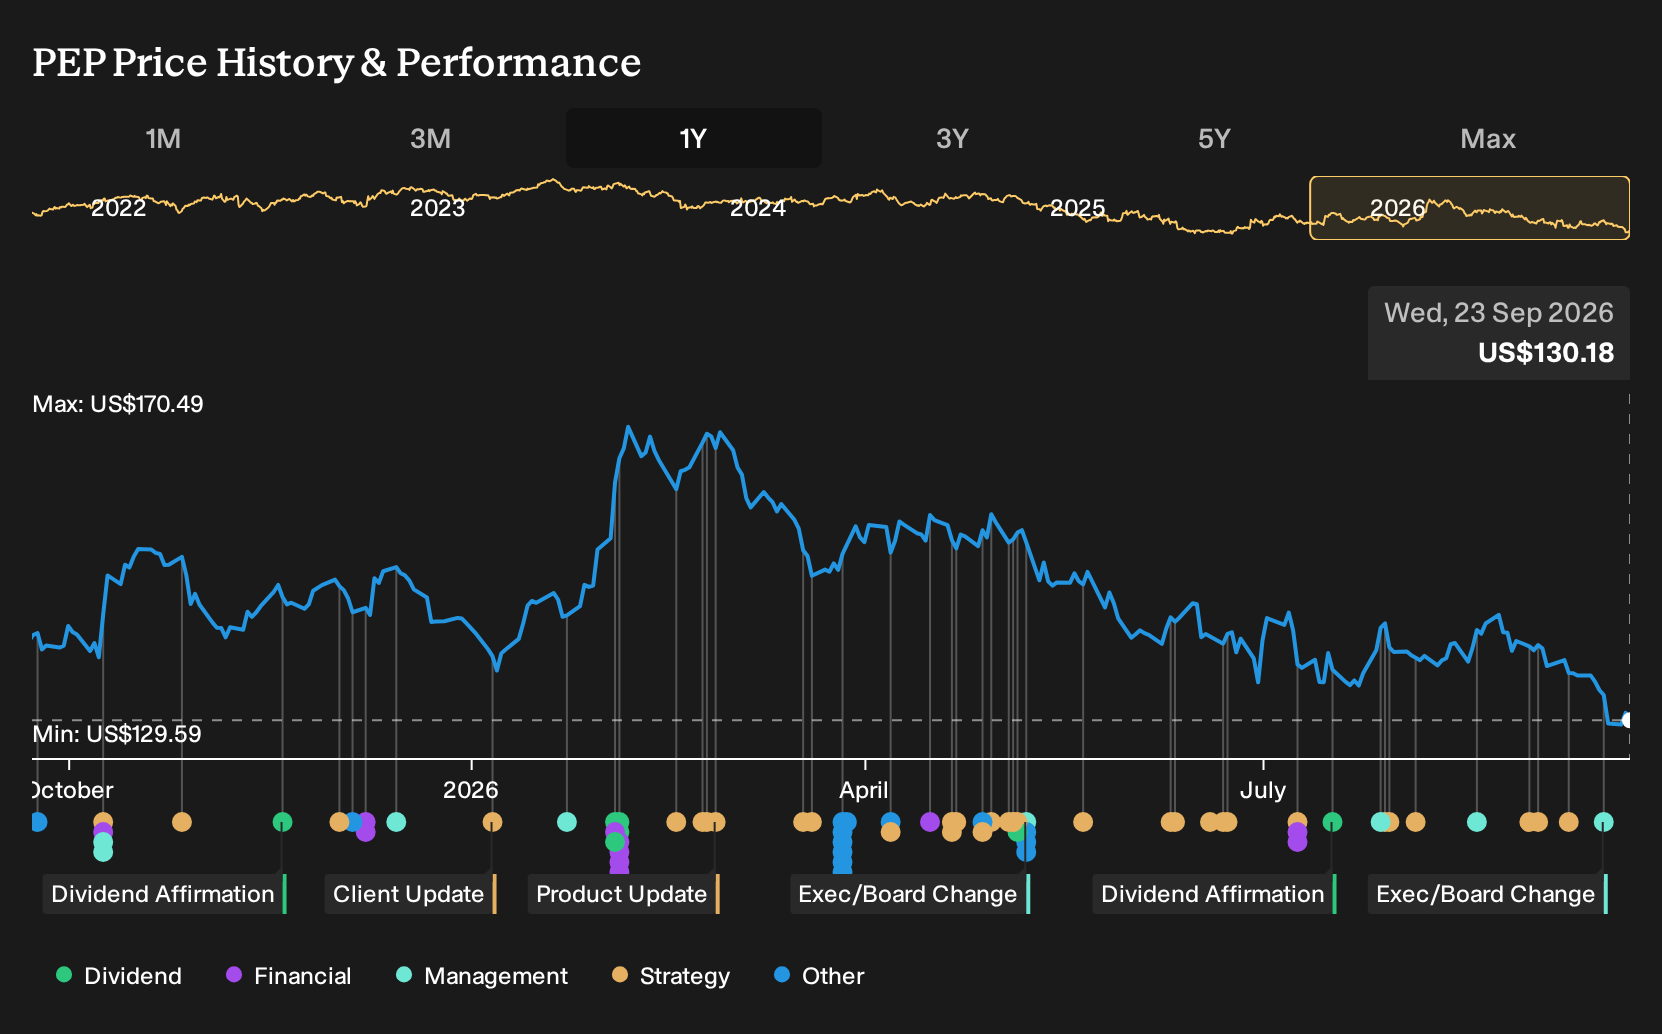
The big swing factor in the near term is still demand for snacks and sugary drinks as GLP 1 use rises and retailers push back on pricing. The exclusive beverage agreement with The Great Greek Mediterranean Grill and the focus on non sugar beverages both lean into health oriented consumption. Joaquin Duato joining the board and Audit Committee adds healthcare and regulatory experience, although that appointment alone is unlikely to shift earnings drivers. With the share price down 24% from its 2026 high and 1 year total return down 3.2%, execution on productivity, debt management and portfolio mix matters more than any single contract win.
Yet there is a less comfortable angle to the PepsiCo story that only really shows up when you look at ...
There's only one way to know the right time to buy, sell or hold PepsiCo. Head to Simply Wall St's company report for the latest analysis of PepsiCo's Fair Value.
Exploring Other Perspectives
The Simply Wall St Community has produced 9 PepsiCo fair value estimates that run from US$116.35 up to about US$172, with views spread across the range. That breadth of opinion sits alongside fresh questions about GLP 1 weight loss drugs, packaging regulation and electric truck spending, so you are weighing health, sustainability and capital intensity at the same time.
Explore 8 other PepsiCo fair value estimates, including one that suggests as much as 32% upside from the current price.
Form Your Own Verdict
Disagree with this assessment? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your PepsiCo research is our analysis highlighting 4 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for PepsiCo. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate PepsiCo's overall financial health at a glance.
Looking For More Investment Ideas Beyond PepsiCo?
Once you have a view on PepsiCo, it can help to compare that thesis with other businesses that have different risk, income and balance sheet profiles. The Simply Wall St Screener gives you a structured way to scan for those contrasts without drowning in data.
- If you care most about resilience and capital preservation, start with a 31 resilient stocks with low risk scores that may suit a more cautious approach.
- For investors who want income as well as potential capital gains, a 7 dividend fortresses can help you focus on cash returns alongside share price moves.
- When you are hunting for quality that the market may be overlooking, the 16 high quality undiscovered gems is a useful way to surface ideas that sit off the usual radar.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com