


How Investors May Respond To FormFactor (FORM) Rising AI Hardware Demand
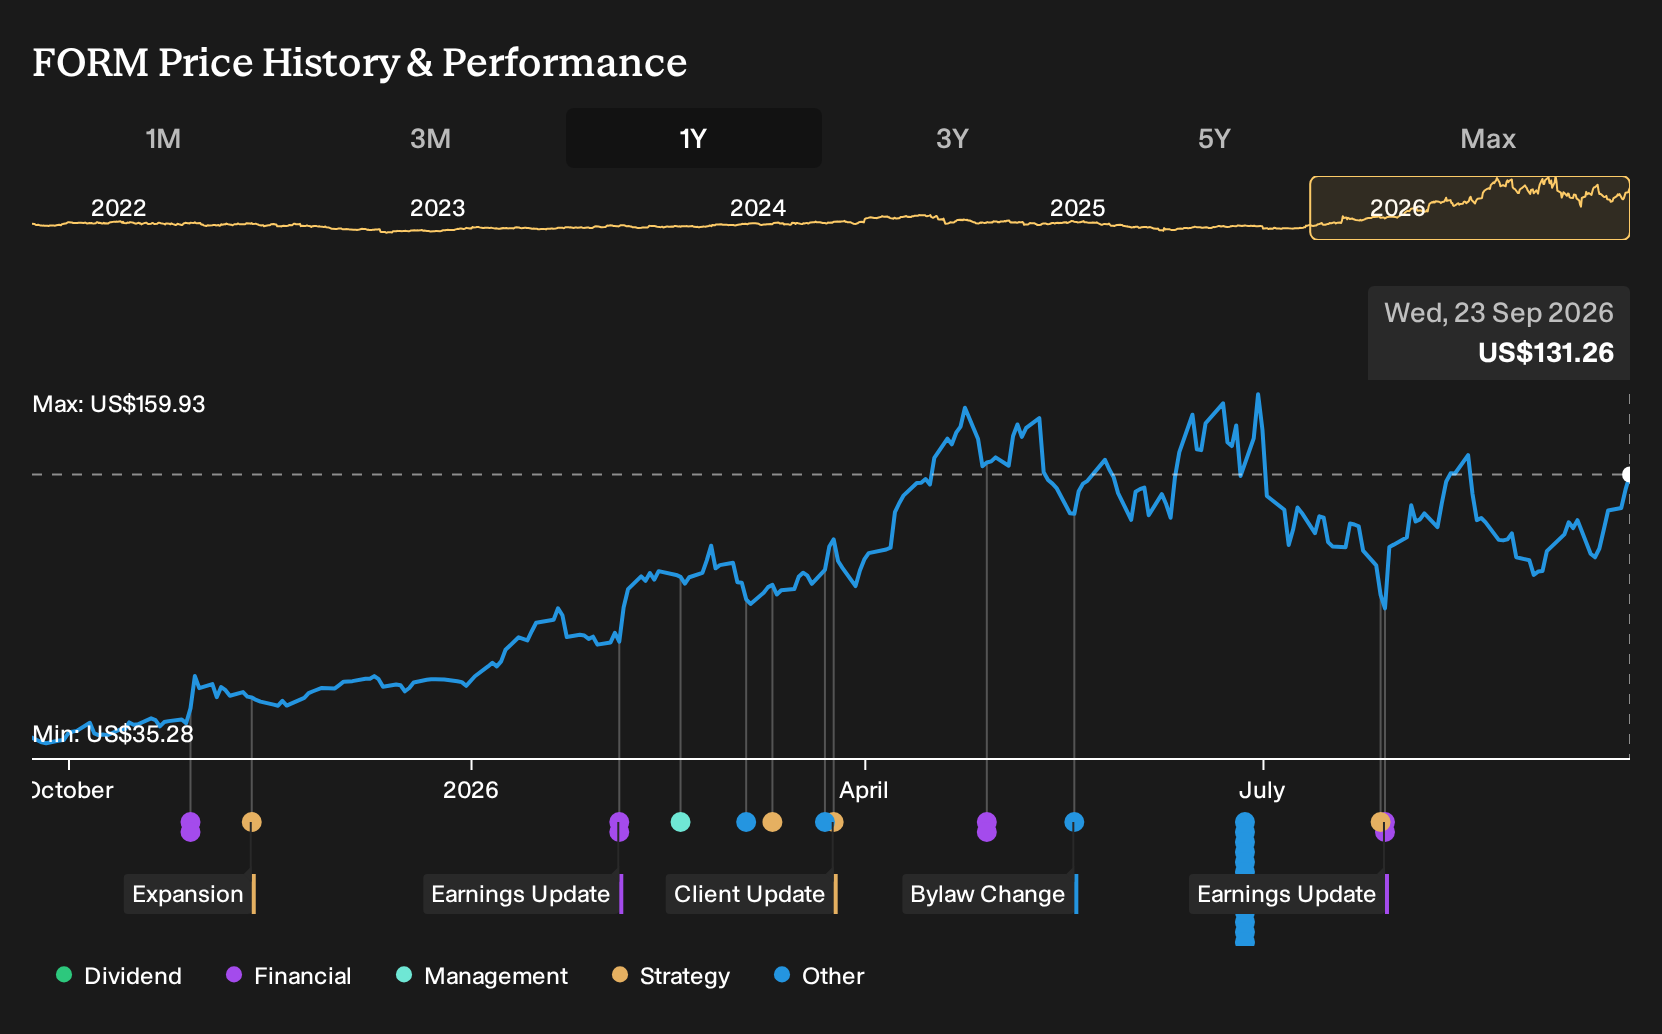
- FormFactor recently drew attention as investor interest in agentic artificial intelligence and Meta Platforms' Muse application pointed to stronger demand expectations for central processing units and related semiconductor testing hardware. At the same time, CEO Mike Slessor sold 17,510 shares on 16 September 2026 under a prearranged Rule 10b5-1 plan and retained a stake valued at about US$49 million.
- The twin developments highlight how rising AI-focused workload expectations could support demand for FormFactor's probe and test solutions. Insider transactions also remind investors to scrutinize execution, capital allocation, and long-term alignment rather than reading any single sale as a simple signal.
- The next section considers how FormFactor's investment narrative could evolve as AI optimism raises hardware demand expectations across testing workloads.
Scan how AI hardware optimism is rippling beyond FormFactor by reviewing a curated 85 AI infrastructure stocks that could also be gearing up for heavier testing and data center workloads.
FormFactor Investment Narrative Recap
To own FormFactor, you need to believe its probe cards and systems remain central as AI, HBM and data center testing workloads become more complex. The recent spike in AI optimism supports that thesis, but the short term story still hinges on how quickly higher value AI related test demand offsets exposure to more volatile DRAM cycles and customer concentration.
The biggest near term swing factor is execution on mix and cost. Management is trying to line up higher complexity AI and custom ASIC work against ongoing gross margin pressure, while absorbing higher operating expenses from the Texas facility ramp. The news driven share price move does not materially change that core risk reward balance.
The clearest tie between the news and fundamentals is the AI hardware angle. FormFactor already generates the majority of its US$902.2m revenue from Probe Cards, which serve GPUs, CPUs, custom ASICs and HBM DRAM. Rising interest in agentic AI and applications like Meta’s Muse points to heavier test intensity on exactly these kinds of devices.
That backdrop makes execution on the current capacity buildout more important. Higher complexity AI oriented probing can support better pricing and help FormFactor work toward its long term margin goals, but this depends on product mix not drifting back toward historically lower margin DRAM and on overhead from Farmers Branch, Texas, being brought into line as volumes ramp.
FormFactor's current earnings sit at US$115.5 million, with analysts forecasting US$452.8 million in profit on US$1.5 billion of revenue by 2029. This implies revenue growth of 17.5% per year and an earnings increase of about US$337 million from today.
Uncover why FormFactor's fair value indicates a 6% potential upside to its current price, which could narrow quickly.
Exploring Other Perspectives
One alternate angle focuses less on AI upside and more on margin strain. Before this Muse driven spike, the most optimistic analysts were still baking in US$1.7b of 2029 revenue and US$465.9m of earnings. That is far above the lowest US$199.9m view, which shows how widely opinions on FormFactor can swing. Narratives are likely to react as fresh AI data and insider activity filter through, so explore several viewpoints before deciding what feels reasonable to you.
Explore 3 other FormFactor fair value estimates, including one that suggests as much as 57% upside from the current price!
The Verdict Is Yours
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your FormFactor research is our analysis highlighting 3 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for FormFactor. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate FormFactor's overall financial health at a glance.
Looking for more FormFactor investment ideas?
If the FormFactor story has sharpened your thinking and you want to broaden your watchlist, the Simply Wall St Screener can help you quickly filter for other opportunities that match your risk profile and income goals.
- For investors who care most about resilience and capital preservation, scan a focused 31 resilient stocks with low risk scores that may better match your tolerance for volatility.
- If dependable income is a priority, zero in on businesses with stronger payout profiles through a curated 7 dividend fortresses that could complement a core holding like FormFactor.
- When the aim is to get ahead of the crowd, review a hand picked 16 high quality undiscovered gems that might offer exposure to quality stories before they appear on most radars.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com